WPI-8 Windstorm Certification in Texas: A Homeowner Q&A Guide

Brad Spurgeon Insurance Agency • July 20, 2026
WPI-8 Windstorm Certification graphic showing a house on stilts and a gold checkmark badge over ocean waves

WINDSTORM & HAIL INSURANCE  ·  TWIA  ·  TEXAS GULF COAST

If you own a home along the Texas coast, you have probably heard the term "WPI-8" from your roofer, your lender, or your insurance agent —

usually right when you need an answer fast. A WPI-8 is the Certificate of Compliance issued by the Texas Department of Insurance (TDI) that

confirms a home meets windstorm building code standards required for coverage through the Texas Windstorm Insurance Association (TWIA).

Below, we answer the questions we hear most often from policyholders in Galveston, Brazoria, Nueces, Cameron, and the other designated coastal

counties, covering both when a WPI-8 is required and what happens when repairs are made without one.


In a hurry? The short version: most new construction, full re-roofs, additions, and any repair touching the roof deck or structural envelope in a

designated coastal county require a WPI-8 before TWIA will insure the property. Skipping it can leave a home ineligible for windstorm coverage,

jeopardize future claims, and complicate a sale or refinance.

When Is a WPI-8 Required?

  • What is a WPI-8 certificate?

    It is a Certificate of Compliance issued by TDI confirming that a home's construction, addition, or repair in a designated coastal catastrophe area meets the windstorm building code standards required to qualify for windstorm and hail coverage through TWIA. Related variants include the WPI-8E, issued for completed improvements inspected after the fact by a licensed engineer, and the older WPI-8C, which TWIA issued for completed work submitted between January 2017 and May 2020.

  • Which Texas counties require a WPI-8 certificate?

    TDI designates 14 first-tier coastal counties as catastrophe areas: Aransas, Brazoria, Calhoun, Cameron, Chambers, Galveston, Jefferson, Kenedy, Kleberg, Matagorda, Nueces, Refugio, San Patricio, and Willacy, plus certain areas of Harris County east of Highway 146. Homes in these areas generally need a WPI-8 on file to be eligible for TWIA coverage.

  • Do I need a WPI-8 for a full roof replacement?

    Yes. A complete re-roof in a designated catastrophe area requires an inspection and WPI-8 certification, since the roof deck and covering are structural

    components tied directly to windstorm resistance.

  • Does a small roof repair after a storm require a WPI-8?

    Not always. TDI exempts roof repairs under 100 square feet that do not involve the decking, along with non-structural items like painting, carpet, cabinets, fences, gutters, shutters, and screen doors. Once decking is disturbed or the repair exceeds that threshold, certification is generally required.

  • Do window and door replacements require a WPI-8?

    Replacing glass alone typically does not require certification, but replacing entire window or door units that affect the structural opening or building envelope usually does, since these components are part of the windstorm-rated envelope.

  • I'm adding a room or garage to my coastal home. Does that require certification?

    Yes. Additions, along with new construction and remodels involving exterior walls or structural reinforcement, require a WPI-1 application and inspection before and during the work, followed by a WPI-8 upon approval.

  • My home was built between 1988 and June 18, 2009 without a windstorm inspection. Am I exempt?

    There is a limited exception for some homes built in that window that were never inspected, but it typically comes with a 15 percent premium surcharge on TWIA coverage rather than a full exemption from the certification requirement. It's worth confirming your specific property's status with our office rather than assuming coverage is automatic.

Consequences When Repairs Lack Certification

  • My roof was damaged by a hurricane and needs immediate repair. Can I fix it first and get certified later?

    TWIA advises against making permanent repairs, such as a full roof replacement, before the adjuster has inspected the damage. Beyond the claims risk, TDI inspectors must inspect work during construction, not before or after, so repairing first and certifying later removes the free inspection option and forces a more expensive path through a licensed professional engineer.

  • What happens if repairs are completed without scheduling a TDI inspection during construction?

    The homeowner must then hire and pay a Texas-licensed professional engineer to inspect the completed work and issue a WPI-8E certificate for completed improvements. This route can be more expensive than a free TDI inspection and may require opening up finished walls or roofing so the engineer can verify what is otherwise hidden from view.

  • What are the consequences of skipping WPI-8 certification on repairs altogether?

    Without a Certificate of Compliance, TWIA has no evidence the structure conforms to the applicable building code, and the structure may be considered ineligible for TWIA coverage. That can mean an existing policy is not renewed, a new policy cannot be issued, and the homeowner is left

    to cover future wind and hail damage out of pocket.

  • Can TWIA deny a future claim because a past repair was never certified?

    Yes, this is a real risk. If a prior repair, such as a roof replacement, was never inspected or certified, TWIA may determine the structure does not meet

    eligibility requirements when a new claim is filed, which can delay or jeopardize payment on damage that is otherwise covered.

  • Will an uncertified home affect selling or refinancing?

    It can. Buyers and lenders in coastal counties routinely ask for proof of windstorm coverage or a valid WPI-8 before closing. A home without

    certification on file can become difficult or impossible to insure through TWIA, which complicates financing, slows down a sale, and can affect resale value.

Getting Certified

  • Who can perform a WPI-8 inspection, and does it cost anything?

    A TDI inspector or a TDI-appointed, Texas-licensed professional engineer can perform the inspection. TDI inspectors do not charge a fee and generally respond within about 48 hours of a requested inspection date, excluding weekends and holidays. Professional engineers set their own rates, which TDI does not regulate, and are typically used when work is already complete or in areas TDI inspectors do not cover.

  • How do I start the WPI-8 application process?

    Before work begins, the builder or homeowner files Form WPI-1, Application for Certificate of Compliance, with TDI's Windstorm Inspection Program. Inspections are then scheduled at the appropriate construction stages, and once all required inspections are approved, TDI issues the WPI-8 certificate, which can be viewed and printed online.

Not Sure Whether Your Project Needs a WPI-8?

Our team helps Texas Gulf Coast homeowners navigate WPI-8 certification, TWIA eligibility, and windstorm claims every day. Whether you are

planning a re-roof, recovering from storm damage, or preparing to sell, we are grateful for the chance to help you get it right the first time.


Call us at (409) 945-4746 or email brad@bradspurgeonins.com.

Related Reading


Thank you,

Brad Spurgeon

www.privatewindstorm.com

Main Phone: (409) 945-4746

This article is provided for general educational purposes and does not constitute legal, engineering, or insurance advice. WPI-8 requirements, exemptions, and county designations are set by the Texas Department of Insurance and TWIA and are subject to change. Contact our office or TDI directly at (800) 248-6032 to confirm requirements for your specific property.

October 15, 2026
Strong winds from thunderstorms, hurricanes, and tropical storms can cause significant property damage. Missing roof shingles, broken windows, damaged siding, and fallen trees are just a few problems homeowners may discover after severe weather.
October 15, 2026
Flooding can happen quickly, leaving families with little time to protect their homes and reach safety. Heavy rainfall, overflowing waterways, tropical storms, and storm surge can create dangerous conditions, particularly in coastal communities.
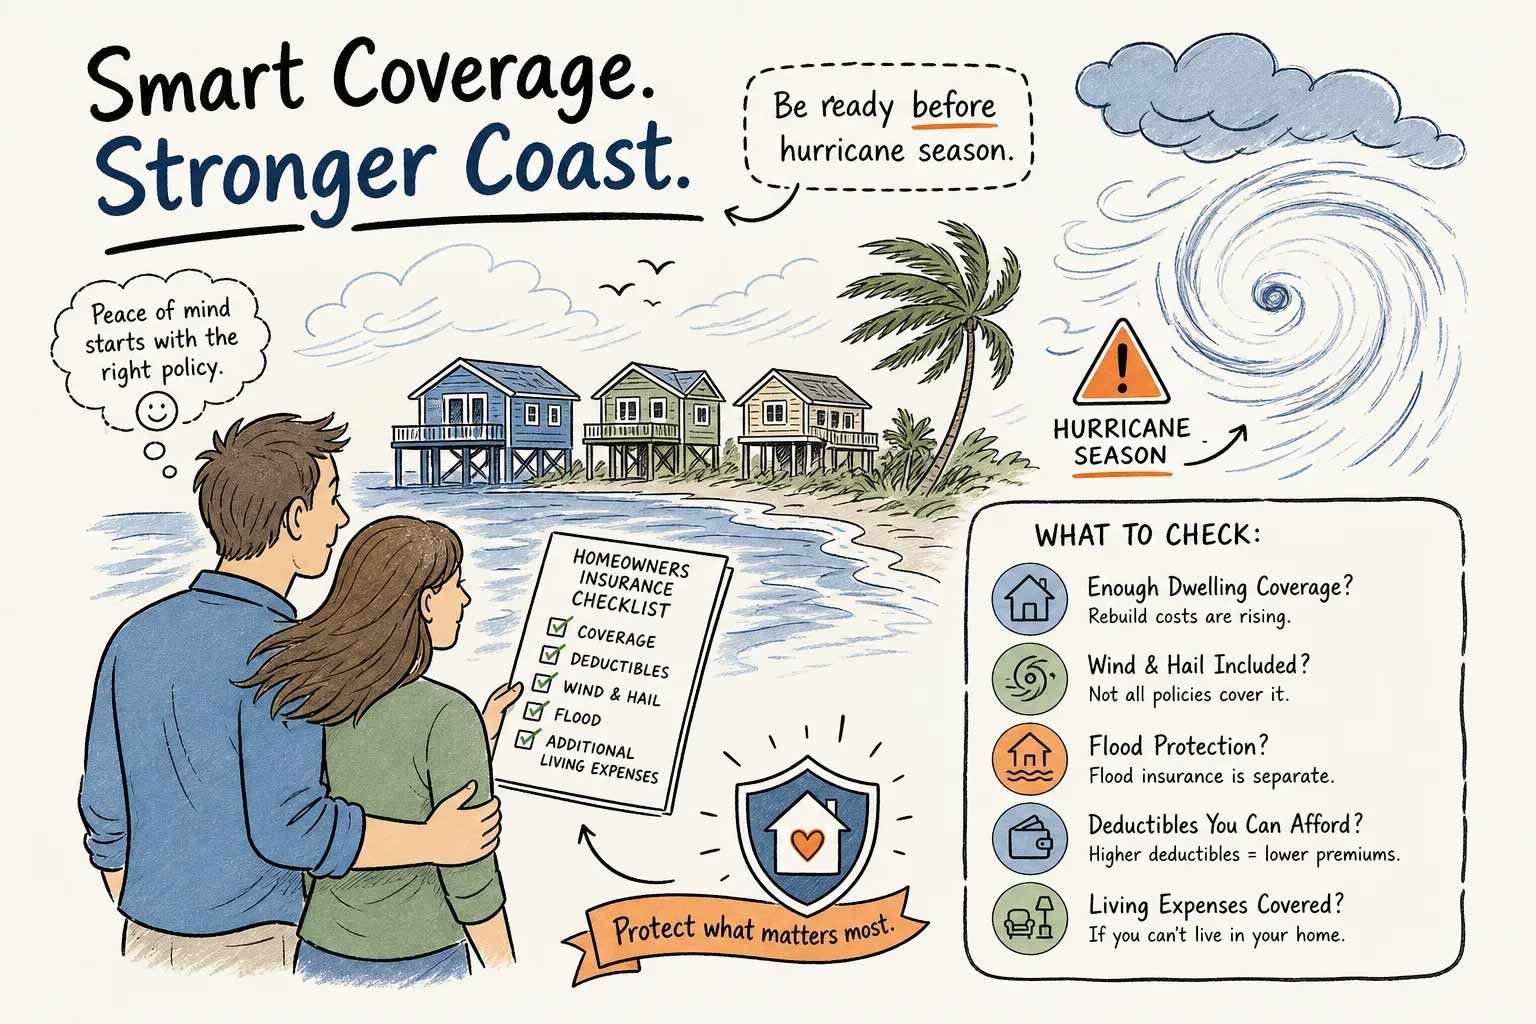
Coastal flood-preparedness infographic with couple, storm clouds, rising water, and checklist for home protection
By Brad Spurgeon • October 12, 2026
A homeowner in Texas City had been paying her homeowners insurance premiums faithfully for years. When a named storm rolled through Galveston County and tore shingles off her roof, she filed her claim confident her policy had her back. What she didn't know, and what nobody had told her, was that windstorm damage had been quietly excluded from her standard policy. The payout she expected? It wasn't coming. That conversation, the one that happens after a hurricane instead of before it, is exactly what we work to prevent at Brad Spurgeon Insurance Agency Inc. We're a family agency that has been serving Texas City and the Gulf Coast for decades, and we've seen this scenario more times than we'd like. The good news: once you understand how homeowners insurance actually works on the coast, protecting yourself completely is straightforward. This article walks you through what's covered, what's not, and the specific steps to get fully protected before hurricane season starts.
Texas Windstorm Certification banner with house, checklist form, and orange moon on blue background
By Brad Spurgeon • October 9, 2026
How to get, find or fix a Texas windstorm certificate (WPI-8 / WPI-8-E) for TWIA coverage. Updated for the 2024 building code. Local agent guide.
September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
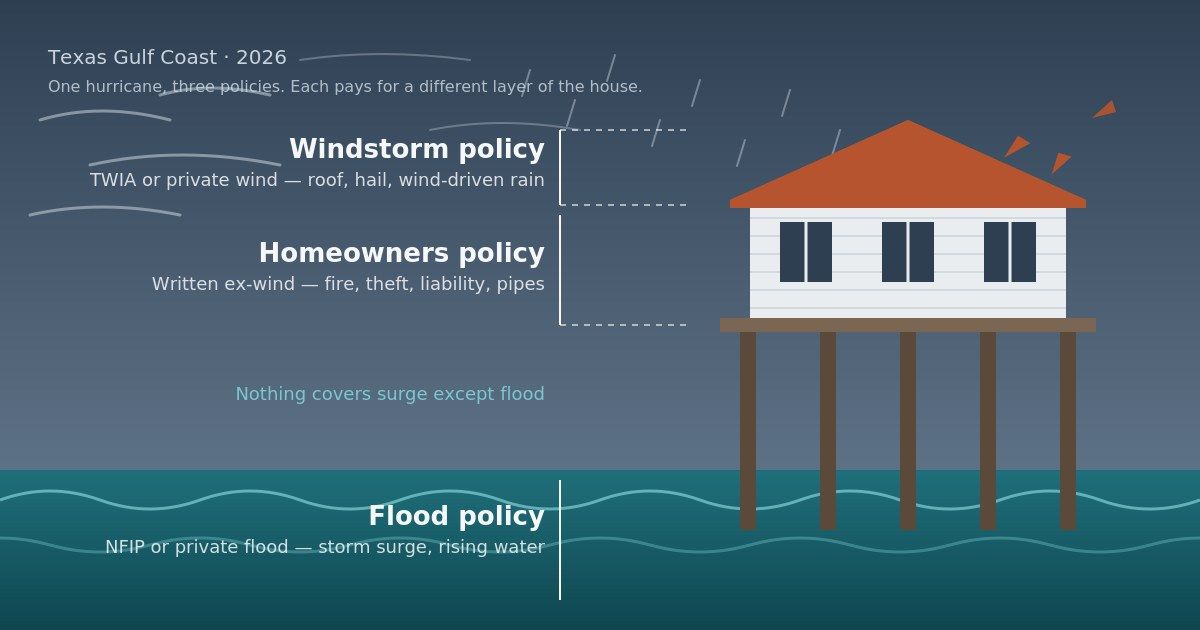
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
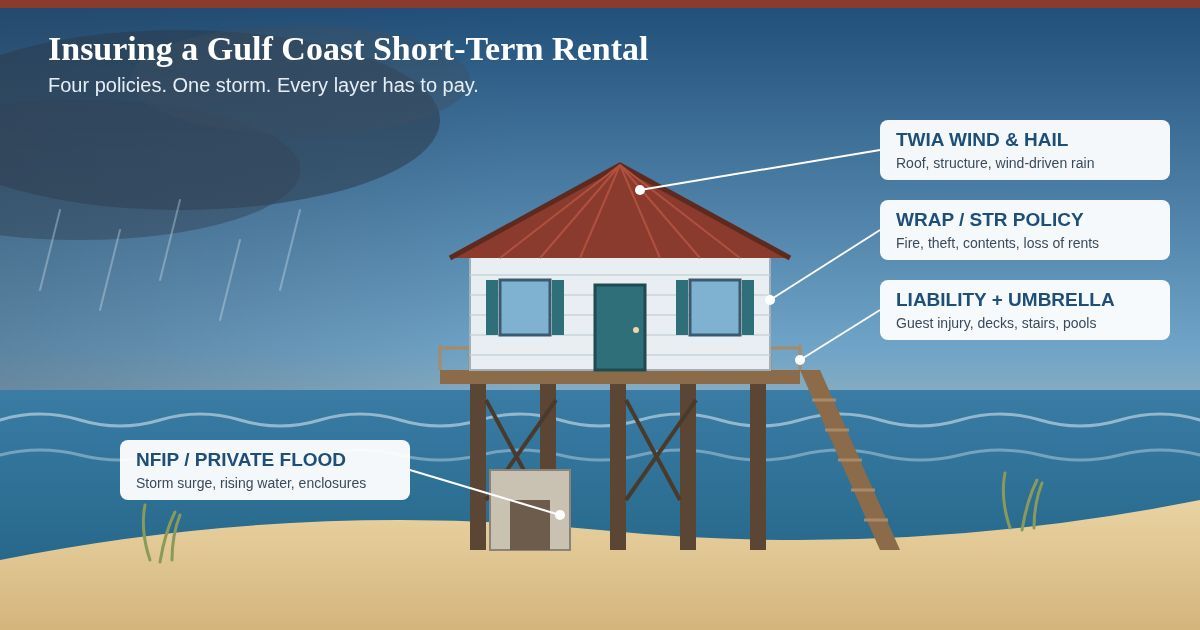
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
Show More