How to Determine If Your Property Requires Flood Insurance in the Texas Gulf Coast

Brad Spurgeon • November 16, 2026
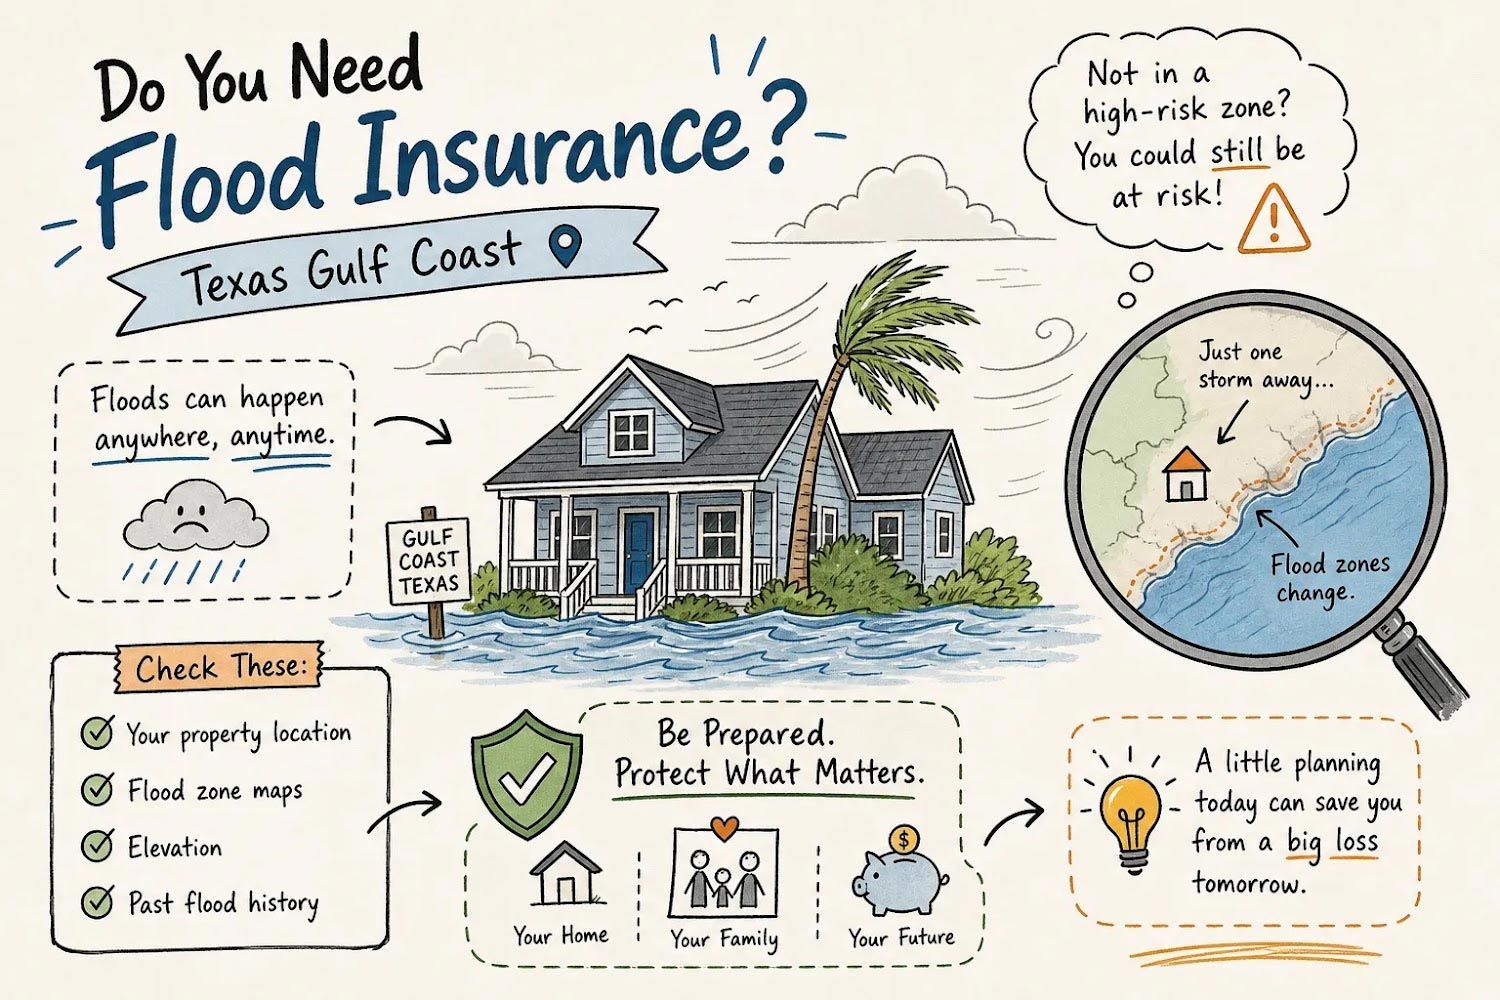
Flood insurance infographic for Texas Gulf Coast homes, with storm and flood risk tips.

Does my property require flood insurance? If you have a federally backed mortgage and your home sits in a FEMA-designated AE or VE flood zone, flood insurance is required by federal law. That is the short answer. If you are not sure which zone your property falls into, or you have heard conflicting things from your lender, your real estate agent, and your neighbor, conflicting guidance is common along the Texas Gulf Coast due to frequent remapping and local ordinance variability.


The Gulf Coast carries unique flood exposure. Roughly 23,000 to 25,000 residential properties in Galveston County alone are mapped inside FEMA Special Flood Hazard Areas, according to a residence-level FEMA-zone analysis. The question homeowners here face is rarely as simple as "do I need it?" More often, it is "does the law require it, and is what I have actually enough?" This guide walks through the exact steps to check your flood zone, understand your lender's requirements, weigh NFIP against private coverage, and figure out your next move.

Key Takeaways

  • Zone determines mandate: Federal law requires flood insurance if your home has a federally backed mortgage and sits in a FEMA AE or VE flood zone.
  • Lenders can go further: Even Zone X properties can be subject to lender-required flood insurance as a loan condition.
  • FEMA maps are the starting point: Use FEMA's Flood Map Service Center to find your official flood zone designation before making any coverage decisions.
  • Elevation certificates matter: They affect your NFIP premium significantly and support a LOMA application, but they do not automatically remove your insurance requirement.
  • NFIP has a $250,000 building cap: Higher-value Gulf Coast properties are more likely to need private flood insurance or an excess policy to cover the full replacement value.
  • Map changes can trigger new requirements: If FEMA remaps your property into an SFHA during your loan term, your lender will notify you and require coverage within a window defined by federal lender guidance; timing may vary by lender and servicer.

Does My Property Require Flood Insurance? How to Check Your FEMA Flood Zone

Start with FEMA's Flood Map Service Center, which is the official source for current flood-hazard information. Go to the Map Service Center search tool, enter your complete street address, and review the flood-zone layer covering your parcel. From there, select "View Map," "Interactive Map," or "Print Map/FIRMette" to pull the applicable FIRM panel and save a copy for your records.

Use FEMA's Map Service Center

When you have the map in front of you, record four things: the FIRM panel number, the effective date, the zone label, and the base flood elevation where it appears. These details matter at closing, at refinance, and in any dispute with your lender about coverage requirements.

What to Record from Your FIRMette

A printed FIRMette is the document to have in hand if you are heading into a closing or refinance. The zone label itself does most of the work. AE zones are high-risk, with a mapped base flood elevation and a 1% annual chance of flooding. VE zones are coastal high-hazard areas with the same 1% annual flood chance but with added wave-action risk and stricter construction rules. Zone X (shaded) is moderate risk. Zone X (unshaded) carries lower mapped risk, but lower is not zero. The zone label determines whether the federal mandatory purchase rule applies and is one of the primary factors in how premiums are calculated.

When Federal Law Requires You to Carry Flood Insurance

The federal mandatory purchase requirement applies when three conditions are true: your building secures a federally regulated or federally backed mortgage, it sits in a FEMA-designated Special Flood Hazard Area (a zone starting with A or V), and your community participates in the NFIP. When all three apply, the lender must require flood insurance before or at loan closing. This requirement covers new loans, renewals, refinances, and increases to existing loans.


The required coverage amount is set at the lesser of three figures: the outstanding loan balance, the building's insurable value excluding land, or the NFIP maximum. The insurance must stay in place while the mortgage remains outstanding or while the property remains in an SFHA, whichever ends first.


What many homeowners do not realize is that lenders are not limited to the federal rule. A lender can require flood insurance on a property in Zone X or any other lower-risk zone as a contractual underwriting condition. If you let coverage lapse, the lender can force-place insurance and charge you for it, often at a significantly higher cost than voluntarily purchased coverage, a practice documented by the FDIC and FEMA. This is a common and expensive surprise for first-time buyers and homeowners refinancing on the Gulf Coast.

Does Your Flood Zone Guarantee You Are Off the Hook?

Many Texas Gulf Coast homeowners assume that an X designation means no flood insurance requirement. The federal mandate does not apply in Zone X, but the lender still might require it. Beyond lender discretion, Zone X properties account for a significant share of flood claims nationally because flooding does not stop at FEMA map boundaries. A storm surge event does not check zone designations before it moves inland.


The scenario that catches buyers off guard most often: a property is in a moderate-risk zone at the time of purchase, the lender does not require flood insurance, and then FEMA updates the Flood Insurance Rate Map mid-loan and moves the property into an SFHA. When that happens, the lender must notify you and require flood insurance within a specific window.


Landlords and homeowners who refinanced before a remapping are particularly vulnerable to this scenario. Newly mapped properties may qualify for certain NFIP rating protections depending on their history, but coverage still becomes mandatory. The lesson is straightforward: check the map yourself, do not assume your lender checked it thoroughly, and do not assume Zone X means permanently safe.

Can an Elevation Certificate or LOMA Remove Your Flood Insurance Requirement?

An elevation certificate documents your building's lowest floor elevation relative to the base flood elevation. It does not, by itself, remove the federal insurance requirement. If your property is still mapped inside the SFHA, insurance is generally still required regardless of how high the structure sits. Where the elevation certificate directly helps is in NFIP premium calculation: a well-elevated property in an AE zone can pay substantially less than a poorly elevated one. According to current Texas NFIP data reported by MoneyGeek, the average annual premium for AE-zone properties is $1,217 and for VE-zone properties is $1,849, though those are broad averages and individual properties vary based on elevation, construction, and other factors.


If you believe your property was mapped into the SFHA by error because the land is naturally above the base flood elevation, you can apply to FEMA for a Letter of Map Amendment through FEMA's Online LOMC system. The process involves gathering a certified elevation certificate and survey data from a licensed Texas Registered Professional Land Surveyor, submitting the application online, and waiting for FEMA's official determination. FEMA states that most determinations are issued within about 35 days after a complete application is received. In the Texas City and Galveston County area, budget $400 to $900 for a simple existing home's elevation certificate, or $600 to $1,200 or more for a complex coastal structure, according to surveying cost data from surveyors.io and other Texas sources.


Once a final LOMA is issued, provide a copy to your lender immediately. At that point, the federal mandatory purchase requirement is typically removed. Note that the lender may still require flood insurance as a contractual loan condition even after a LOMA is issued, so confirm in writing what your lender's specific policy is before you cancel coverage.

NFIP vs. Private Flood Insurance: Which One Fits Your Situation?

The right answer depends on your property's value, your lender's requirements, and what coverage gaps matter most to you.

Feature NFIP Private flood insurance
Contents valuation Typically actual cash value Replacement cost available with some policies
Loss of use / living expenses Not included Available with some policies
Waiting period 30 days (narrow exceptions for loan closings) Often 10 to 14 days, varies by insurer
Who sets rates FEMA; rate does not vary by agent or company Each insurer uses its own models and underwriting
Lender acceptance Generally accepted when federally required Usually accepted if policy meets federal requirements; lender must approve
Basement coverage Limited May be broader, policy-specific

For many Texas Gulf Coast properties, particularly those with higher rebuilding values, the NFIP's $250,000 building cap does not come close to covering a total loss. VE-zone properties with significant coastal construction value, landlords with rental income at risk, and owners of higher-value homes are the most likely candidates for private flood insurance or an excess policy layered on top of NFIP.

If My Property Requires Flood Insurance, What Are My Options? Steps to Take Right Now

Flood insurance is not complicated once you know what to look for. Work through these steps in order.


  1. Run your address through FEMA's Flood Map Service Center and record your zone, FIRM panel number, effective date, and base flood elevation.
  2. Pull your mortgage documents or call your loan servicer to get their specific flood insurance requirement in writing, not just a verbal summary.
  3. If you are in an AE or VE zone, confirm you have a current flood policy that meets your lender's coverage floor.
  4. If you believe your property was incorrectly mapped, obtain an elevation certificate from a licensed Texas RPLS and evaluate whether a LOMA application makes sense before paying for coverage you may not legally need.
  5. Compare NFIP and private options before renewing or purchasing a new policy, paying close attention to building limits, contents valuation, waiting periods, and loss-of-use coverage.


Brad Spurgeon Insurance Agency Inc. has worked with Texas Gulf Coast homeowners on flood, windstorm, and home insurance since 1986. We are a third-generation family agency in Texas City, and the Gulf Coast is the only market we serve. If you want to know whether your current coverage is adequate, whether your flood zone designation looks correct, or whether a private policy or our Windstorm Included Home Policy would better fit your property, reach out to our team through our online tools or contact us directly for personalized advice on your specific property and lender requirements.


If you are still asking "does my property require flood insurance," run the FEMA map check, talk to your lender, and get a quote from someone who knows the Gulf Coast. Those three steps answer most of the flood insurance questions we hear from homeowners every year.

Frequently Asked Questions

  • Does my property require flood insurance?

    Your property is required to carry flood insurance if it secures a federally backed mortgage and sits in a FEMA-designated Special Flood Hazard Area (any zone beginning with A or V) in an NFIP participating community. Your lender may also require it as a loan condition even if your property is in a lower-risk Zone X designation.

  • How do I find my flood zone?

    Use FEMA's Flood Map Service Center and enter your property address. The tool displays your official Flood Insurance Rate Map panel and zone designation. Record the zone label, panel number, effective date, and base flood elevation for your records.

  • What is the mandatory purchase requirement?

    The federal mandatory purchase requirement is the law that obligates lenders to require flood insurance on properties that secure federally regulated or backed loans and are located in a FEMA-designated Special Flood Hazard Area. The requirement applies at origination and throughout the life of the loan.

  • Can a LOMA remove my flood insurance requirement?

    Yes. If FEMA issues a Letter of Map Amendment confirming your property is naturally above the base flood elevation and was incorrectly included in the SFHA, the federal mandatory purchase requirement is typically lifted once you provide the LOMA to your lender. Your lender may still require coverage as a contractual condition, so confirm their policy in writing before canceling.

  • Does my property require flood insurance if it is in Zone X?

    The federal mandate does not apply in Zone X, but your lender may require coverage anyway as a loan condition. Zone X properties also experience flood losses, storm surge and heavy rainfall do not follow map boundaries, so voluntary coverage is worth evaluating regardless of legal obligation.

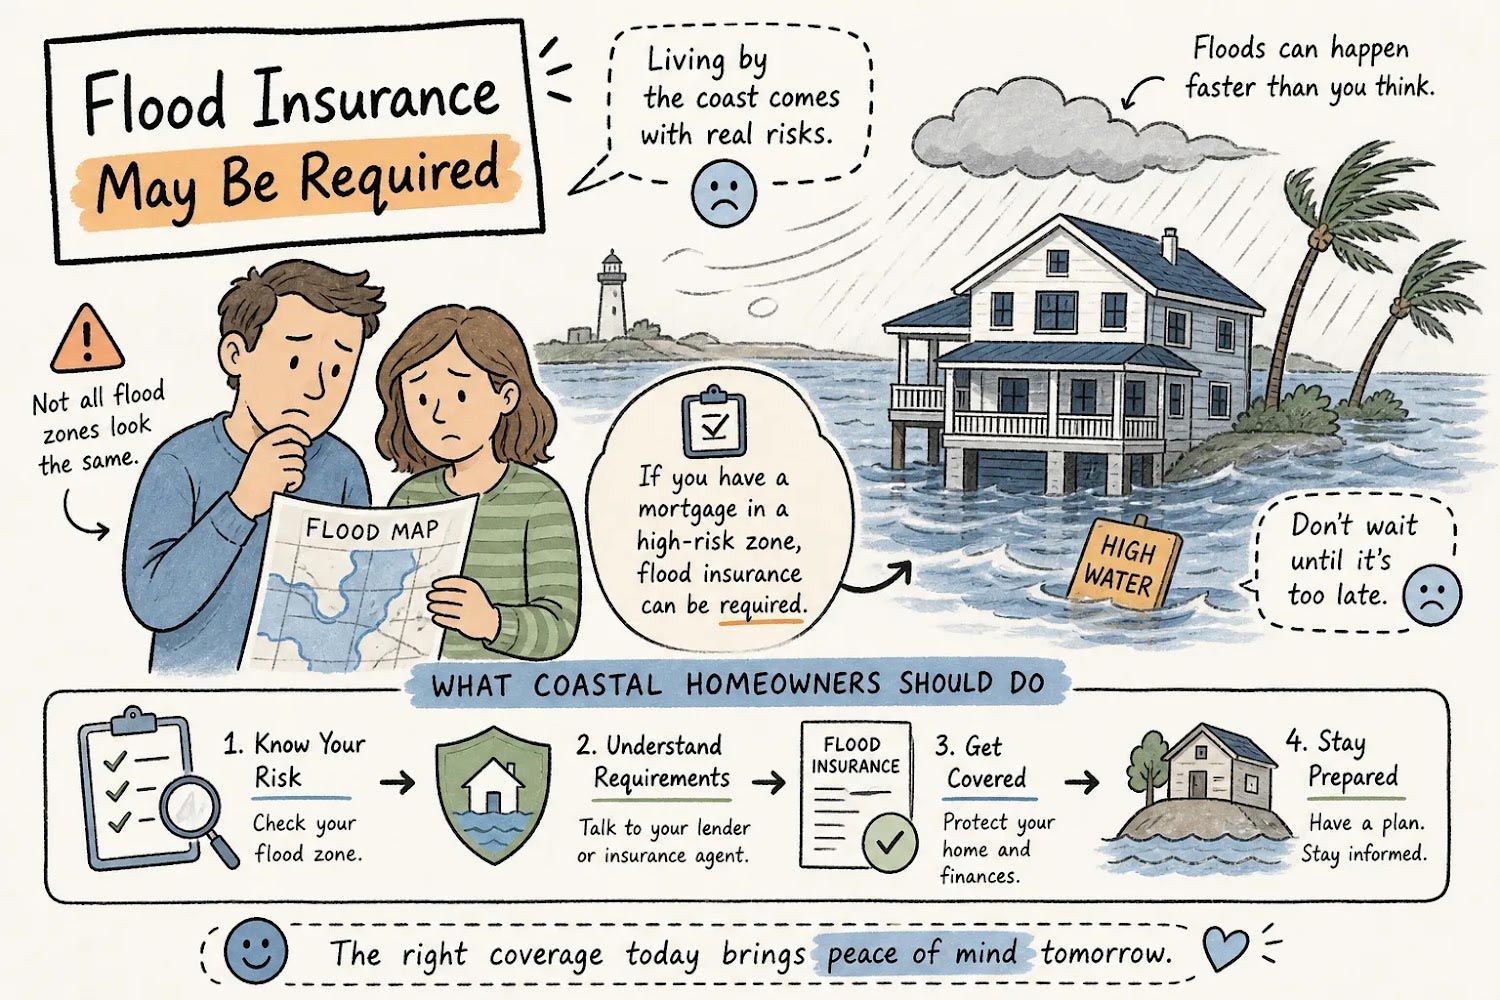
Flood insurance explainer infographic with a house, worried couple, and tips about flood risk and coverage
By Brad Spurgeon • November 16, 2026
Flood insurance is required for properties located in a FEMA-designated Special Flood Hazard Area when the mortgage is federally backed or made by a federally regulated lender. Both conditions must be true at the same time. Having a federally backed loan does not trigger the requirement on its own, and being in a high-risk flood zone does not trigger it either if your financing is fully private. When both boxes are checked, coverage is mandatory for the life of the loan, and your lender enforces it. For Texas Gulf Coast homeowners, flood risk does not arrive alone. Storm surge, windstorm exposure, and hurricane activity all layer on top of the basic flood question, and the gaps between standard insurance policies can leave a claim partially or entirely uncovered. This article walks through the key situations that trigger mandatory flood coverage, how to verify your flood zone, and how to build a complete coastal insurance strategy.
Collage of travel scrapbook pages with “Cover the Gap,” a couple by the sunset, and a desert road trip theme
By Brad Spurgeon • November 16, 2026
Gap coverage insurance pays the difference between what you still owe on your car loan or lease and what your insurer actually pays out after a total loss. Guaranteed asset protection, the full name behind the acronym, is the product that closes that hole. If you financed or leased a vehicle in the last few years, this article is worth reading before you assume you're fully covered.
November 11, 2026
Flooding can cause extensive property damage, leaving homeowners with important decisions about repairs, documentation, and insurance claims. For residents of Texas City, TX, understanding when to report flood damage is especially valuable because coastal storms and heavy rainfall can create unexpected flooding risks.
November 11, 2026
Living along the Texas Gulf Coast means preparing for powerful winds, hurricanes, and unpredictable weather conditions. For homeowners in Texas City, TX, having windstorm insurance is an important step, but understanding additional coverage options can make a meaningful difference. Windstorm insurance riders may provid
November 10, 2026
A burst pipe can release significant amounts of water into a home, damaging floors, walls, furniture, and personal belongings within minutes. For homeowners in Texas City, TX, understanding how insurance responds to unexpected plumbing problems is an important part of protecting their property. Knowing which types of w
November 10, 2026
Protecting a home along the Texas Gulf Coast requires understanding how different insurance policies respond to property damage. For homeowners in Texas City, TX, comparing homeowners insurance and windstorm insurance is especially important because coastal properties may have unique coverage requirements. Knowing how
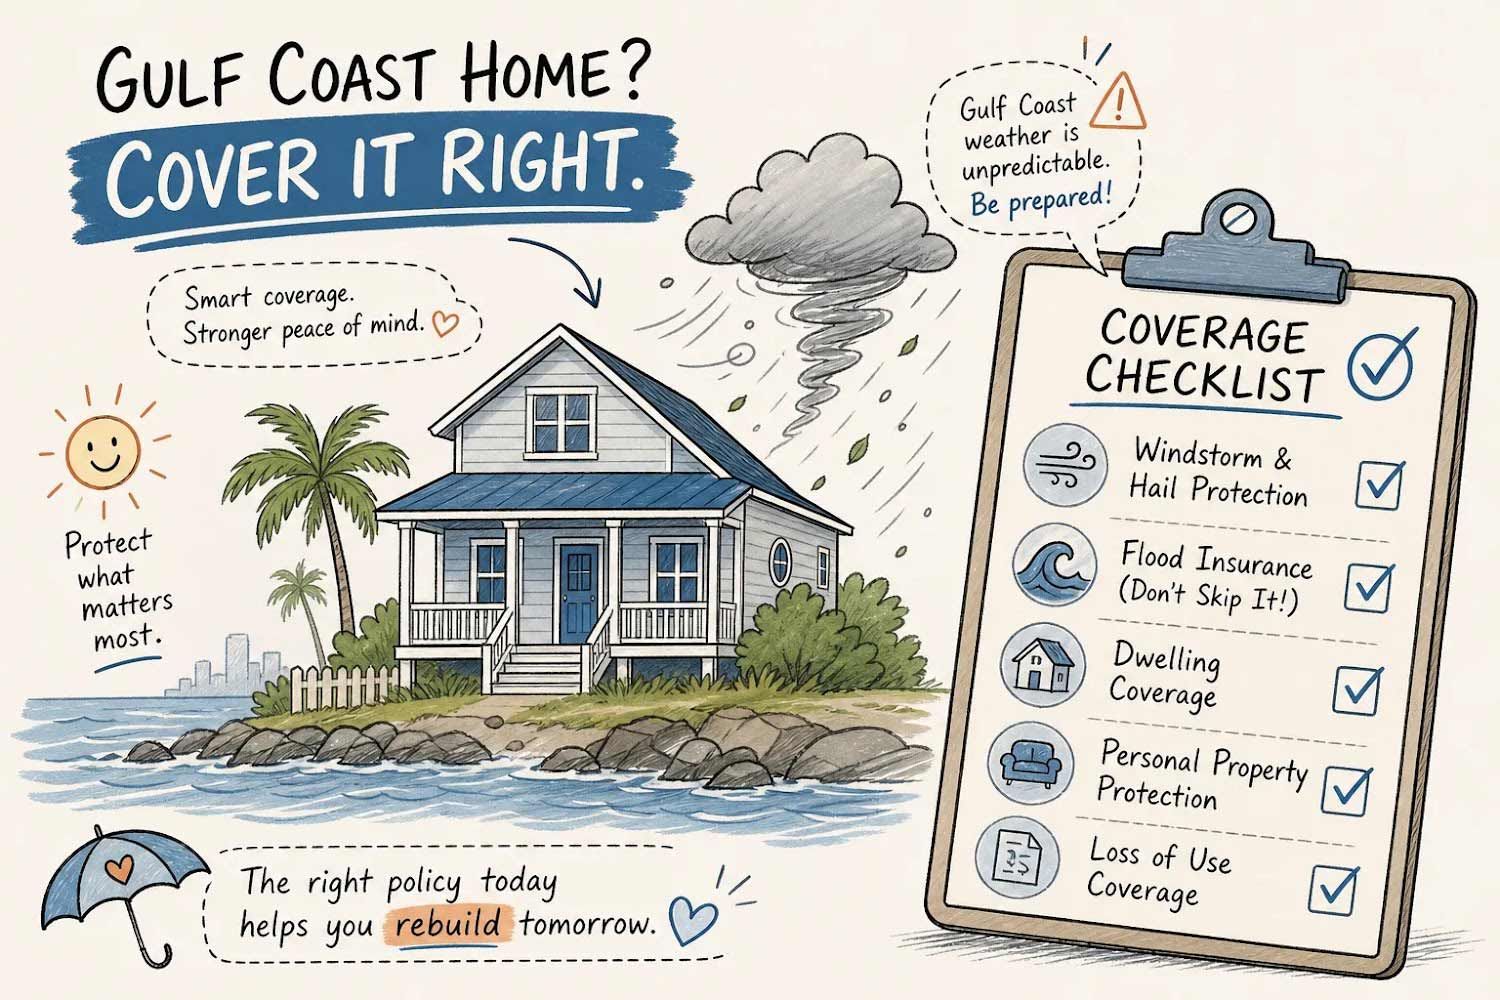
Illustrated coastal home under storm clouds with roof and drainage checklist for hurricane preparedness
By Brad Spurgeon • November 2, 2026
When buying on the Gulf Coast, understanding home owners insurance in Texas is essential, because a standard HO-3 policy covers fire, theft, and many everyday perils, but excludes windstorm, hail, and flood in most coastal counties. That means a single hurricane can trigger three separate claims under three separate policies, and if you only carry one policy, two of those losses come out of your own pocket. This checklist walks through what each layer covers, what it costs in 2026, and which option closes all three gaps most efficiently. Whether you're closing on a home next week or reviewing a policy you've had for years, the sequence below gives you a clear path forward.
TW login screen with woman at laptop, smiling and pointing at a sign-in panel with security icons and house illustration
By Brad Spurgeon • November 2, 2026
If you're searching for a TW login and you live on the Texas Gulf Coast, you're likely trying to reach one of two portals: the Texas Windstorm Insurance Association (TWIA) policyholder site or your insurance agency's online client account. TWIA uses "TW" prominently in its name and branding, and it's the essential portal for managing windstorm and coastal home coverage. Knowing which portal you need, and what to expect at the sign-in screen, makes the whole process much simpler. This guide covers the most common TW portals Gulf Coast homeowners land on, how to log into each one, how to fix errors that block access, how to recover a forgotten password, and how to verify you're on a legitimate page before you type a single credential. And if you still can't get through, Brad Spurgeon Insurance Agency Inc., a third-generation family-owned agency serving the Texas Gulf Coast since 1986, can walk you through it directly.
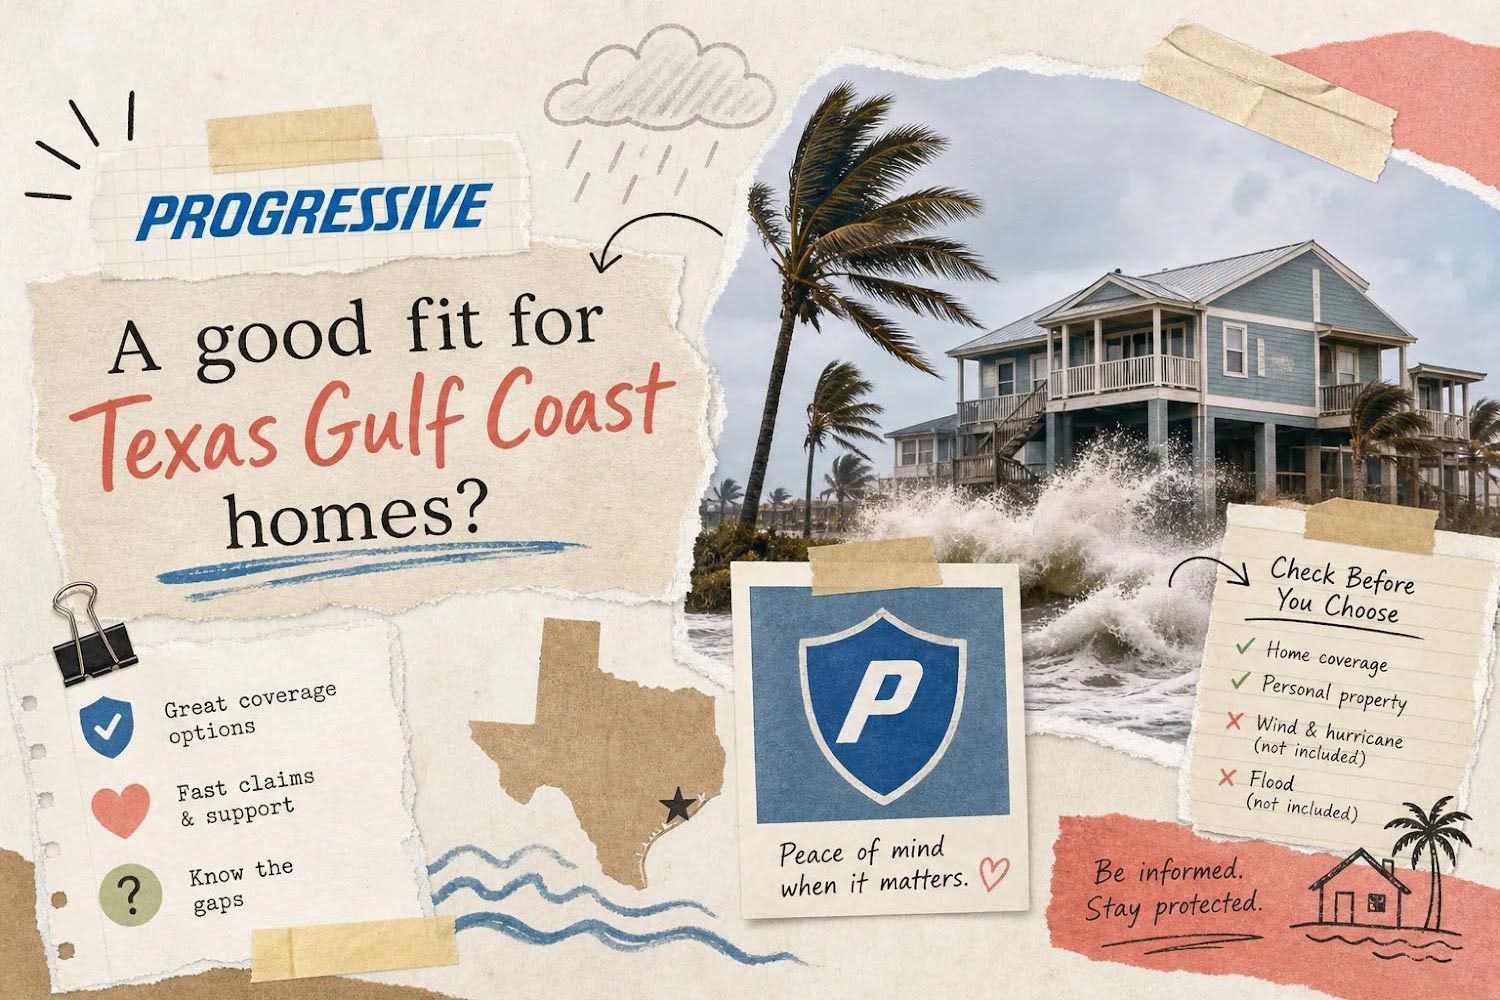
Progressive ad: “A good fit for Texas Gulf Coast homes?” with beach house, storm surf, and map graphic
By Brad Spurgeon • October 29, 2026
Progressive home insurance offers standard HO-3 coverage that works well for most American homeowners, but for Texas Gulf Coast properties, that base policy typically excludes the two biggest threats in the region: windstorm damage and flooding. Those aren't minor omissions for a home in Galveston County or along the Brazoria coastline. They're exactly what a hurricane or tropical storm delivers. Texas already carries some of the highest home insurance premiums in the country, and coastal ZIP codes push that figure even further above the national average. Spending that much on a policy that leaves windstorm and flood damage uncovered is a critical mistake. This article breaks down what progressive home insurance actually includes, where it falls short for coastal properties, and what a complete coverage picture looks like.
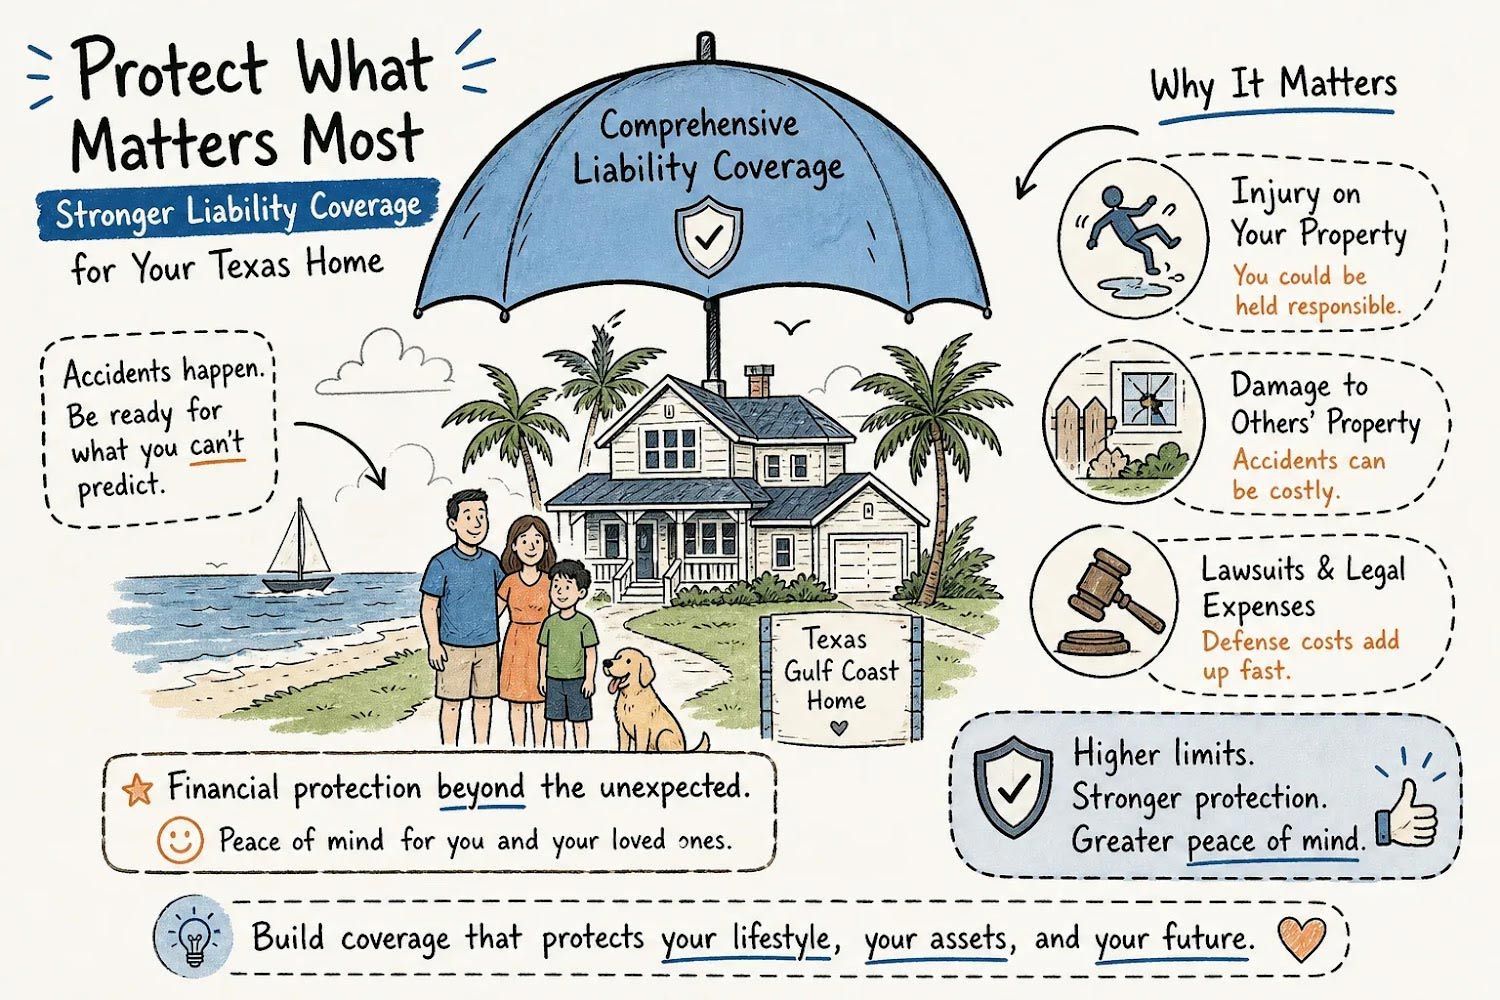
Infographic on flood insurance, showing a house, umbrella, and hurricane tips for protecting belongings and finances.
By Brad Spurgeon • October 29, 2026
Comprehensive personal liability coverage, known as Coverage E in your homeowners or renters policy, pays when someone else is injured on your property or you accidentally damage their property and you're legally responsible. It also covers your legal defense costs, attorney fees, and court judgments up to your policy limit. This guide breaks down exactly what you're covered for, what slips through the gaps, and how to build a comprehensive liability protection stack that actually holds up when a claim lands. Whether you're a first-time buyer in Texas City or a long-time Gulf Coast homeowner juggling a boat, a dog, and a rental unit, getting these limits right matters more here than almost anywhere else in the country.
Show More