Windstorm damage can leave homeowners dealing with roof problems, broken windows, fallen debris, and urgent repair decisions all at once. For homeowners in Texas City, TX, knowing what to do immediately after a storm can make the claim process clearer, better documented, and less stressful.
Start With Safety First
After a
windstorm, the first priority is safety. Before checking damage, make sure everyone in the household is accounted for and away from immediate hazards. Strong winds can leave behind loose power lines, unstable trees, damaged roofs, broken glass, and weakened structures.
Do not climb onto the roof or enter areas that appear unsafe. Even if the damage looks manageable from the ground, hidden structural problems can make inspection dangerous. If you smell gas, see sparks, notice major structural movement, or suspect electrical damage, leave the area and contact the proper emergency service provider.
In our work with clients, a common issue we see is that homeowners try to inspect or fix damage too quickly. It is understandable to want answers right away, but safety should come before documentation, repairs, or cleanup.
Prevent Further Damage When Possible
Most
insurance policies require homeowners to take reasonable steps to prevent additional damage after a covered loss. This does not mean making permanent repairs immediately. It means taking practical temporary measures when it is safe to do so.
Examples may include:
- Placing a tarp over a damaged roof area
- Boarding up a broken window
- Moving undamaged belongings away from water intrusion
- Covering exposed openings
- Drying wet areas when safe
- Turning off water if plumbing was affected
- Securing loose items that could cause more damage
Keep receipts for materials, labor, emergency services, tarps, storage, or temporary repairs. These expenses may be considered during the claim, depending on the policy.
Document The Damage Thoroughly
Good documentation can make a major difference in a windstorm claim. Take photos and videos before making temporary repairs, if it is safe. Capture wide shots of the property and close-up images of specific damage.
Focus on areas such as:
- Roof shingles, tiles, flashing, gutters, and vents
- Siding, trim, soffits, and fascia
- Windows, doors, screens, and shutters
- Fences, sheds, detached structures, and carports
- Interior ceiling stains or water intrusion
- Damaged personal property
- Fallen trees, limbs, or debris
- Outdoor equipment and furniture
When possible, include date-stamped photos and notes describing what happened. If neighbors near Galveston Bay or Moses Lake experienced similar storm impact, that can provide useful context, but your claim should still focus on your own property damage.
Review Your Insurance Policy
Before filing or during the early claim process, review your
policy carefully. Windstorm coverage can vary by carrier, property location, deductible type, and policy form.
Pay close attention to:
- Whether windstorm or hail damage is included
- Whether you have a separate windstorm policy
- Your windstorm deductible
- Roof coverage terms
- Exclusions or limitations
- Other structures coverage
- Personal property coverage
- Loss of use coverage
- Claim reporting deadlines
For homeowners in Texas City, TX, windstorm coverage deserves special attention because coastal exposure can affect how
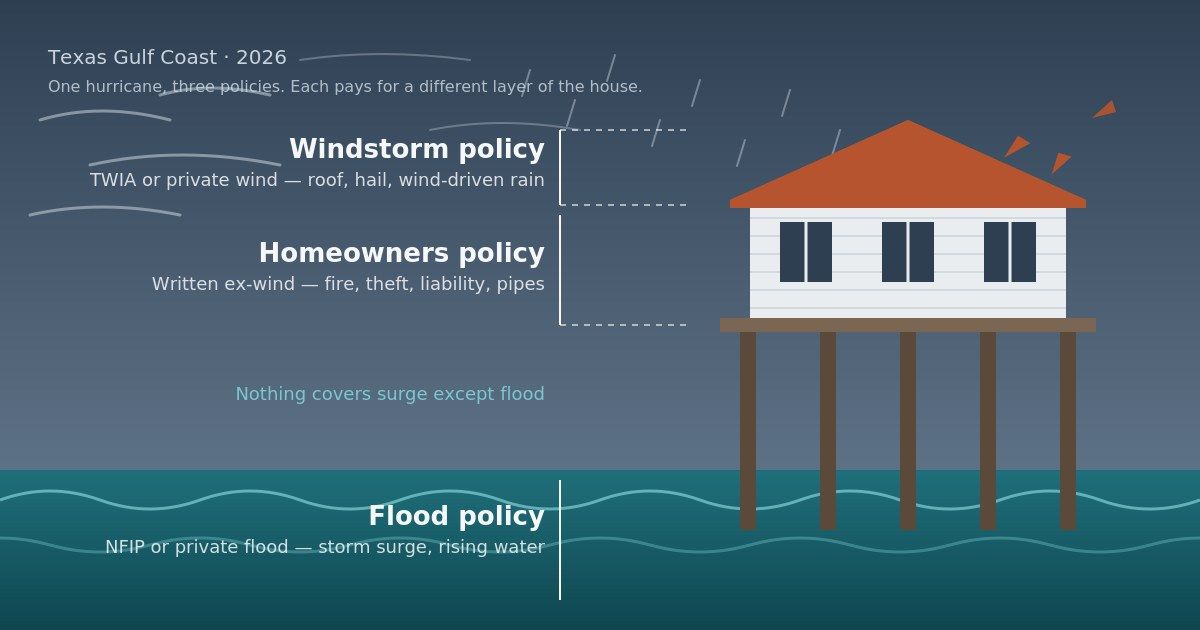
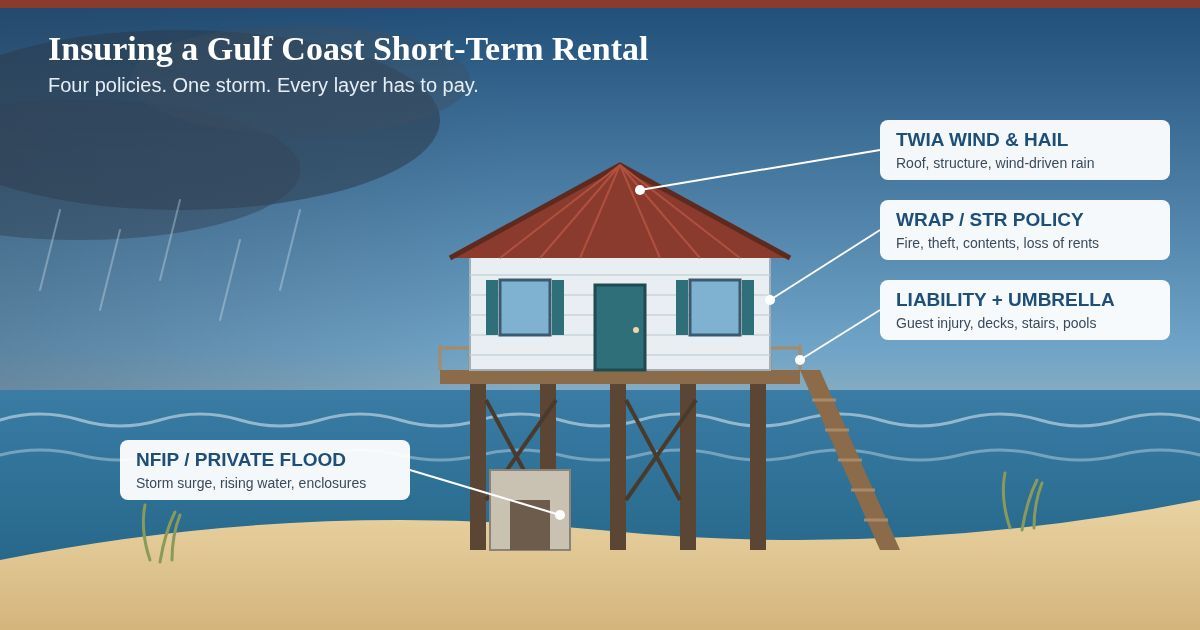
coverage is written. Some homeowners may have wind coverage through a separate policy rather than their standard homeowners policy.
Understand Your Windstorm Deductible
A windstorm deductible may work differently from a standard deductible. Some policies use a flat deductible, such as a set dollar amount. Others use a percentage deductible based on the insured value of the home.
For example, if your home is insured for a certain amount and your wind deductible is a percentage, your out-of-pocket responsibility could be higher than expected. This is why it is important to review the deductible before a storm, not after damage occurs.
A common misunderstanding is assuming the deductible will be the same for every type of claim. Fire, theft, water damage, hurricane, hail, and windstorm claims may have different deductible rules depending on the policy.
Contact Your Insurance Agent Or Carrier Promptly
Once the property is safe and you have initial documentation, contact your
insurance agent or insurance company to report the damage. Provide clear details about the date of the storm, the type of damage, and any temporary steps taken to prevent further loss.
Be prepared to provide:
- Policyholder name
- Policy number, if available
- Property address
- Date and approximate time of damage
- Description of visible damage
- Photos or videos
- Receipts for temporary repairs
- Contractor estimates, if available
Ask what the next steps are and whether an adjuster will inspect the property. Also ask whether there are specific forms, deadlines, or documentation requirements.
Avoid Permanent Repairs Too Soon
Temporary repairs are usually encouraged when needed to prevent further damage. Permanent repairs should generally wait until the
insurance company has had an opportunity to inspect the damage or provide claim guidance.
If emergency permanent work is unavoidable, document everything carefully. Take photos before, during, and after the work. Keep detailed invoices, contractor notes, and material receipts.
Do not discard damaged materials until the adjuster has reviewed them or until you are told it is acceptable. If damaged items must be removed for safety or sanitation, photograph them clearly first.
Be Careful With Contractors After A Storm
After major storms, contractors may go door to door offering inspections or quick repairs. Many are legitimate, but homeowners should still be cautious.
Before hiring a contractor:
- Verify licensing and insurance
- Check reviews and references
- Avoid signing blank contracts
- Be cautious with high-pressure sales tactics
- Ask for written estimates
- Understand payment terms
- Confirm who is responsible for permits
- Do not assign claim benefits without understanding the document
A professional contractor can be helpful during recovery, but the homeowner should remain in control of the claim process and policy communication.
Track Communication And Expenses
Keep a claim folder with all important information. This can be digital, physical, or both.
Include:
- Claim number
- Adjuster contact information
- Dates and times of calls
- Emails and letters
- Photos and videos
- Repair estimates
- Temporary repair receipts
- Hotel or temporary housing receipts, if applicable
- Contractor invoices
- Notes from inspections
This record can help if there are questions about timing, scope, costs, or claim decisions. Organized documentation also makes it easier to compare estimates and understand what is being paid.
Watch For Hidden Damage
Windstorm damage is not always obvious immediately. A roof may look acceptable from the ground but still have lifted shingles, damaged flashing, or compromised seals. Water intrusion may appear later as ceiling stains, bubbling paint, soft drywall, or musty odors.
After a storm, monitor the home for several days or weeks. If you notice new signs of damage, document them and notify the insurance company promptly.
Hidden damage may be especially important after strong gusts, flying debris, or wind-driven rain. Delayed reporting can make it harder to connect the damage to the storm event.
Know What May Not Be Covered
Windstorm insurance does not cover every storm-related issue. Flooding from rising water is typically handled separately through flood insurance. Damage from poor maintenance, wear and tear, old roof conditions, or pre-existing problems may be limited or excluded.
For example, if wind damages the roof and rain enters through the storm-created opening, the resulting interior damage may be evaluated under windstorm coverage. But if water enters because of long-term deterioration or an unrepaired leak, coverage may be more limited.
This distinction is important for homeowners in Texas City, TX because severe weather can involve multiple causes of damage. Wind, rain, flood, and maintenance-related issues may be handled differently.
Conclusion
A windstorm claim is easier to manage when homeowners act quickly, document thoroughly, prevent further damage, and understand their
policy. The most important steps are to stay safe, take photos and videos, make reasonable temporary repairs, report the claim promptly, and keep detailed records.
Windstorm coverage can be complex, especially when deductibles, roof terms, separate policies, and flood exclusions are involved. Reviewing your coverage before storm season and following a clear checklist after damage can help protect your home and reduce claim confusion.
At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by
CLICKING HERE.
Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.
Brad Spurgeon Insurance Agency
Texas City, TX
(409) 945-4746
https://www.privatewindstorm.com/