Sheds, fences, and detached garages may be covered by windstorm insurance, but coverage depends on how the policy defines other structures, the cause of loss, and any exclusions or separate deductibles that apply. The key is to confirm whether those structures fall under your policy’s covered property and whether wind or wind-driven damage is insured in your specific situation.
Why This Question Matters More Than Homeowners Expect
Many property owners focus on the main house when reviewing
windstorm coverage, but detached structures often represent a meaningful part of the property’s total value. A fence line, storage shed, workshop, or detached garage may be expensive to repair or rebuild after a severe storm, especially when multiple structures are damaged at once.
A common issue we see is that homeowners assume anything sitting on the same lot is automatically covered the same way as the main dwelling. That is not always true. Insurance policies often separate the dwelling from “other structures,” and the coverage rules, limits, and deductibles may not work the way people expect.
In Texas City, TX, that distinction matters because strong wind events can damage not only roofs and siding, but also gates, fences, detached storage buildings, carports, and garages that are more exposed to uplift or flying debris.
What Counts As An Other Structure
In many property policies, detached structures are grouped into a separate coverage category. This often includes buildings or fixtures on the property that are not physically attached to the home.
Examples may include:
- Detached garages
- Storage sheds
- Fences
- Gazebos
- Workshops
- Detached carports
- Small guest structures, depending on the policy
- Driveway gates and similar exterior features in some cases
That category matters because
insurance usually assigns a separate limit for these structures rather than treating them as part of the main house. Even when windstorm damage is covered, the amount available for a detached structure claim may be capped well below the dwelling limit.
How Windstorm Coverage Usually Applies
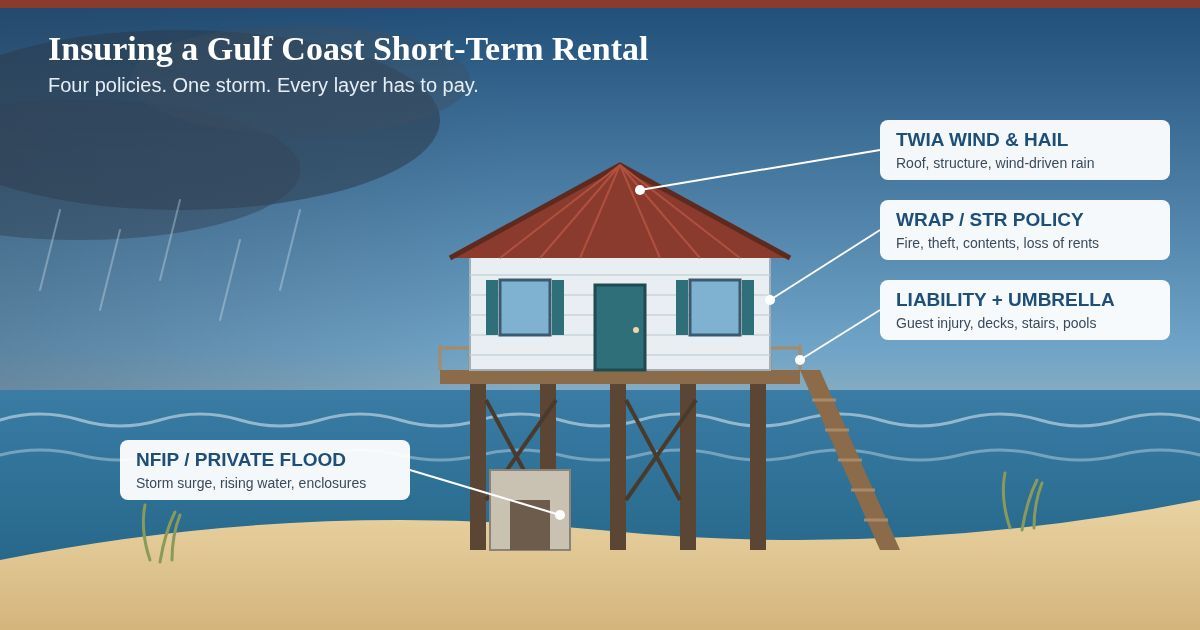
Windstorm insurance generally covers direct physical damage caused by covered wind events, subject to the terms of the policy. If a detached garage loses part of its roof during a windstorm, or if a shed is damaged by wind-thrown debris, the loss may be covered if the structure falls within the policy’s insured property categories and no exclusion applies.
The details, however, matter. Coverage questions often turn on issues such as:
- Whether the structure is specifically considered an other structure under the policy
- Whether the damage was caused by wind alone or by another excluded event
- Whether the structure was in sound condition before the storm
- Whether policy endorsements or regional wind exclusions apply
- Whether cosmetic damage is treated differently from structural damage
In our work with clients, one of the biggest misunderstandings is assuming that “wind damage” is always one simple category. In practice, the claim outcome may depend on whether the damage came from straight-line wind, a named storm, wind-driven rain entering through an existing opening, fallen trees, or a mix of causes.
Detached Garages Are Often The Clearest Example
Detached garages are among the most commonly covered non-dwelling structures, but they still are not insured the same way as the house itself. In most cases, they fall under the other structures portion of the policy, which means the claim is still subject to that separate coverage limit.
That can become a problem when the detached garage is large, finished out, or used for more than simple vehicle storage. A detached garage with cabinetry, tools, workbenches, electrical upgrades, or hobby equipment may cost much more to restore than the policyholder realizes.
We often see homeowners underestimate replacement cost here. They think of the detached garage as a simple outbuilding, but rebuilding it after wind damage may involve concrete work, framing, roofing, wiring, doors, and code-related improvements. The coverage may exist, but the limit may not be high enough.
Fences Are Commonly Covered, But With Important Limits
Fences are often one of the first things damaged in a strong storm, and they are also one of the areas where expectations and policy language can clash. Many policies do include fences under other structures coverage, but the payout depends on the cause of loss, the policy wording, and the amount of damage.
A common issue we see is a
homeowner expecting full fence replacement when the policy or adjuster determines only a portion of the fence sustained direct storm damage. Another frequent issue is age and condition. If a fence was already deteriorated, leaning, or poorly anchored before the storm, that can affect how the damage is evaluated.
Near Galveston Bay or around the Bay Street area, fence claims may become more complicated because repeated exposure to salt air, moisture, and prior wear can raise questions about what portion of the loss was sudden storm damage versus pre-existing condition.
Sheds Can Be Covered, But Construction Quality Matters
Sheds are often covered if they are permanently located on the
insured property and fit the policy definition of other structures. Still, not all sheds are treated equally.
A well-built shed on a proper foundation may present a clearer claim than a lightweight structure, temporary kit building, or partially anchored storage unit. If wind damage occurs, the insurer may look closely at how the shed was constructed, whether it was secured properly, and whether the damage reflects storm force or inadequate installation.
This matters because some homeowners buy prefab sheds, place them on-site, and assume full protection applies automatically. The policy may provide some coverage, but the condition, age, and method of attachment can all matter when a claim is reviewed.
What Can Limit Or Affect Coverage
Even when sheds, fences, and detached garages are generally covered, several factors can reduce or complicate recovery.
Common issues include:
- Coverage limits for other structures being too low
- Separate windstorm deductibles
- Exclusions tied to certain storm events
- Wear and tear or deferred maintenance concerns
- Damage that is partly caused by flooding rather than wind
- Failure to document the condition of the structure before the storm
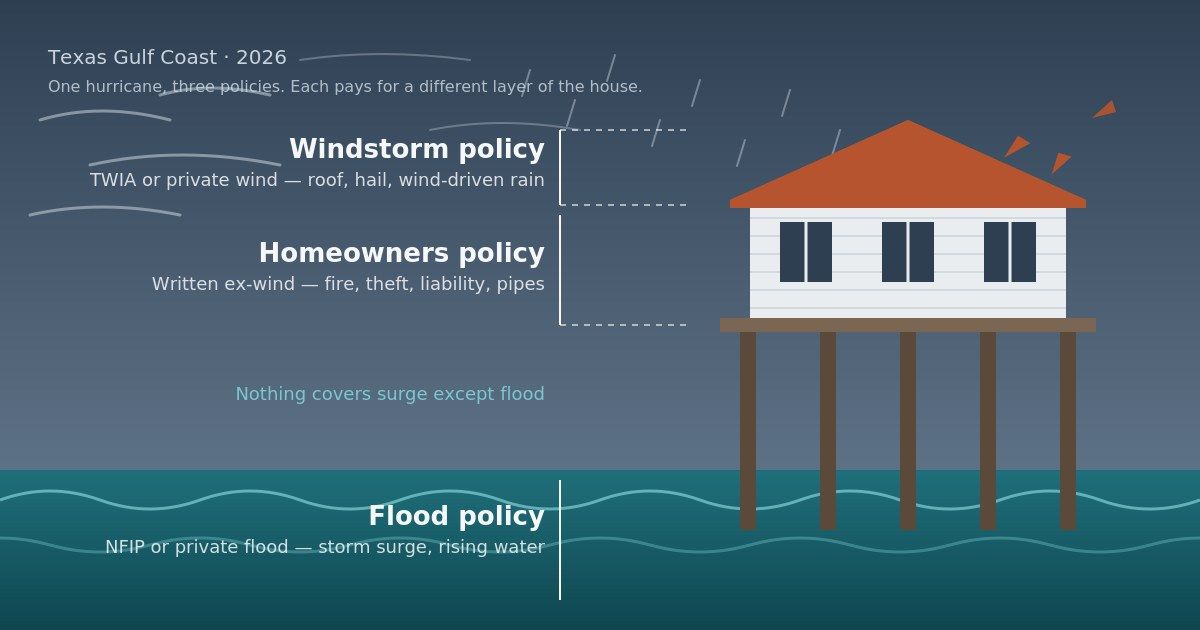
In Texas City, TX, one of the most important distinctions is wind versus flood. If a detached garage is damaged by storm surge or rising water rather than wind, that may fall outside a
windstorm policy
and into flood coverage territory instead. The same can apply to sheds and fences located in more exposed portions of the property.
What Homeowners Should Review Before The Next Storm
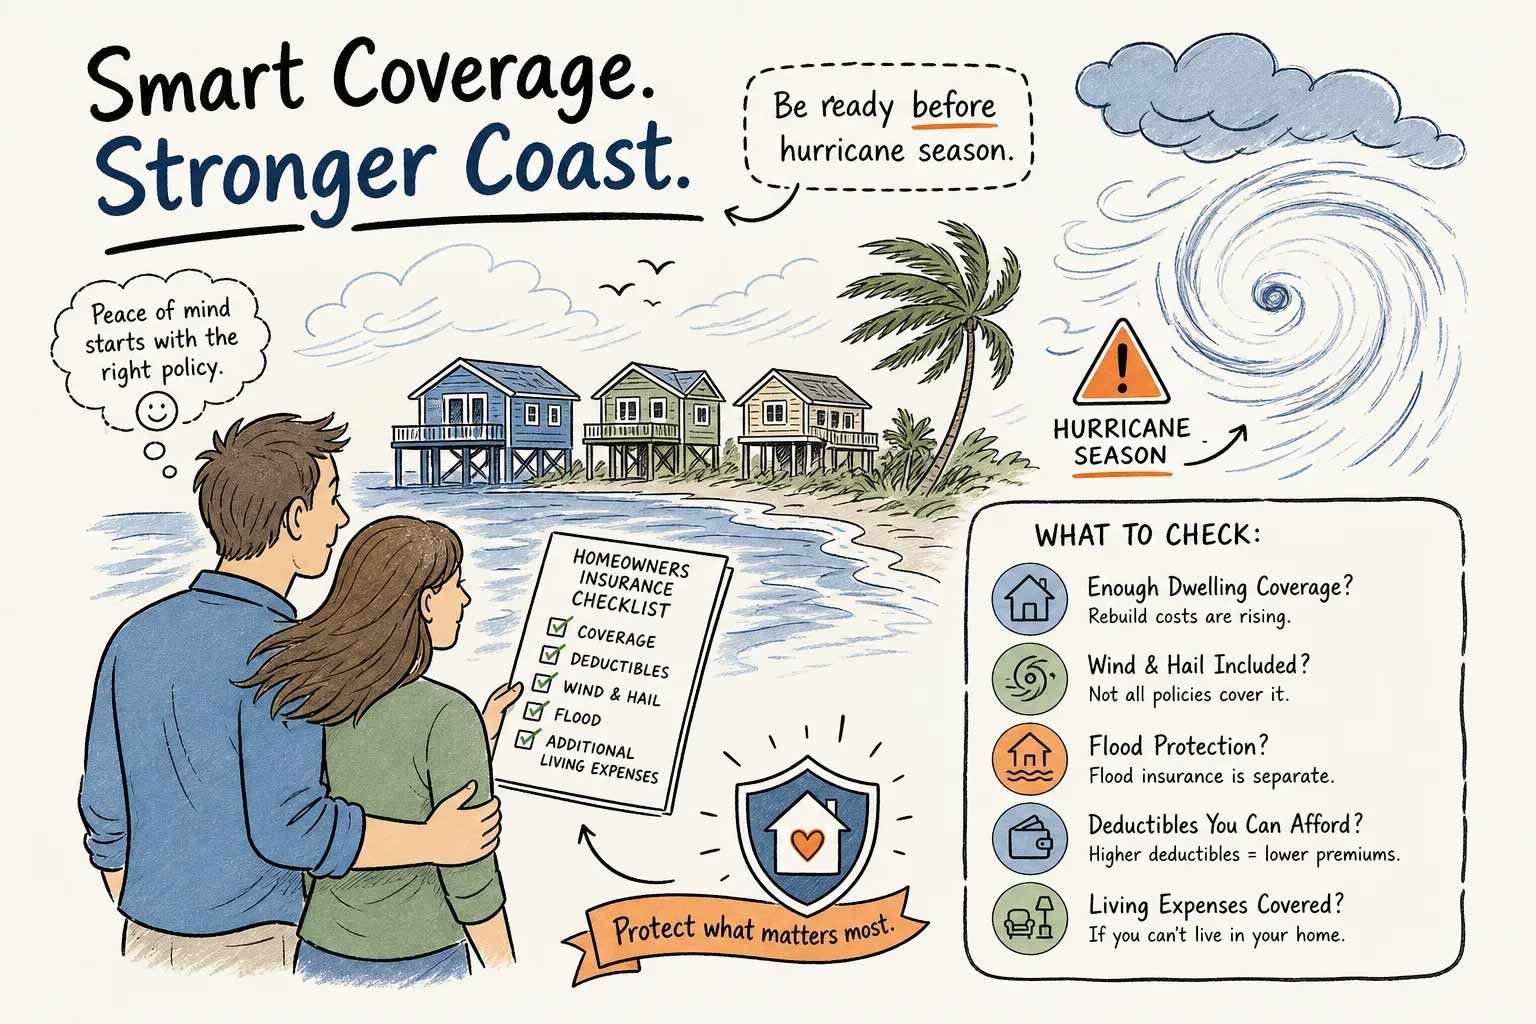
The best time to check this coverage is before damage happens. Waiting until after a storm usually means the policyholder is reading technical language while also trying to deal with cleanup and repairs.
A practical review should include:
- Whether other structures are covered under the policy
- The exact coverage limit for those structures
- The windstorm deductible
- Whether any endorsements change the scope of coverage
- Whether detached structures have been added, upgraded, or rebuilt since the policy was written
- Whether photos and records exist to show pre-loss condition
A common mistake we see is improving a detached garage or replacing fencing without ever updating the insurance conversation. The property changes, but the coverage review does not.
Conclusion
Sheds, fences, and detached garages are often covered by
windstorm insurance, but that coverage is rarely automatic in the broad way homeowners assume. The structure must fit the policy definition of covered property, the cause of loss must be covered, and the available limit has to be enough to make the protection meaningful.
At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by CLICKING HERE.
Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.
Brad Spurgeon Insurance Agency
Texas City, TX
(409) 945-4746
https://www.privatewindstorm.com/