Why Windstorm Insurance Rates Vary: Key Pricing Factors Revealed

January 14, 2026
Stormy ocean background

Windstorm insurance rates can vary widely from one homeowner to another because pricing is based on risk, construction details, and policy structure—not just location alone. Factors such as roof type, building materials, deductibles, and coverage limits all play a role in determining premiums. In our years of professional service, we’ve found that understanding these variables helps homeowners in Texas City, TX make smarter, more cost-effective coverage decisions.


What Windstorm Insurance Is Designed to Cover

Windstorm insurance is intended to protect homes from damage caused by high winds, including hurricanes, tropical storms, and severe wind events. Along the coast, this coverage is often excluded from standard homeowners policies and must be purchased separately or through a specialized program.


Because wind damage can result in large-scale losses, insurers assess risk carefully. This is why premiums can differ significantly—even between homes that appear similar on the surface.


Location Risk Is Only the Starting Point

Geographic exposure is one of the first pricing considerations, but it is not the only one.


How Insurers Evaluate Wind Exposure

Insurance carriers consider:

  • Proximity to the coastline or open water
  • Historical storm frequency and severity
  • Regional wind maps and catastrophe models


Homes closer to areas like the Texas City Dike or other exposed coastal infrastructure are generally considered higher risk, but location alone does not determine the final rate.


In Texas City, TX, two neighboring homes can have very different premiums depending on how well they are built and protected.


Construction Features That Impact Windstorm Rates

The way a home is built has a major influence on windstorm insurance pricing.


Key Structural Factors Insurers Review

Common construction-related factors include:

  • Roof shape (hip roofs often perform better than gable roofs)
  • Roof covering material and age
  • Roof-to-wall attachment methods
  • Wall construction (masonry vs. frame)
  • Presence of storm shutters or impact-resistant windows


In our professional experience, newer construction or homes that have been upgraded to meet modern wind-mitigation standards often qualify for lower premiums.


Roof Condition and Materials Matter More Than Many Realize

The roof is one of the most critical components in windstorm risk evaluation.


Why Roof Details Affect Pricing

Insurers closely examine:

  • Roof age and remaining useful life
  • Type of roofing material
  • Installation method and maintenance history


An older roof—even on an otherwise well-maintained home—can significantly increase windstorm insurance costs or limit carrier options. We frequently advise homeowners that roof improvements can have a direct and measurable impact on premiums.


Deductibles Play a Major Role in Pricing

Windstorm policies often use percentage-based deductibles rather than flat dollar amounts.


Understanding Windstorm Deductibles

Key points to consider:

  • Deductibles are commonly based on a percentage of the dwelling limit
  • Higher deductibles usually result in lower premiums
  • Lower deductibles increase premiums but reduce out-of-pocket exposure


In our years of professional service, we’ve found that many homeowners underestimate how percentage deductibles work until a claim occurs. Choosing the right deductible is a balance between affordability and financial preparedness.


Coverage Limits and Policy Structure

The amount of coverage you choose directly affects your premium.


How Coverage Choices Influence Cost

Insurers factor in:

  • Dwelling coverage limits
  • Extended or guaranteed replacement cost options
  • Ordinance or law coverage
  • Additional endorsements


Policies with broader protection and higher limits naturally cost more, but they also reduce the risk of underinsurance after a major storm.


Claims History and Insurance Score

Your personal insurance profile also plays a role.


Personal Factors That Can Affect Rates

These may include:

  • Prior windstorm or property claims
  • Length of insurance history
  • Overall insurance score


While these factors don’t outweigh construction or exposure risks, they can influence which carriers are available and how competitively a policy is priced.


Why Rates Can Change Over Time

Even if nothing about your home changes, windstorm rates can still increase.


Common Reasons for Rate Changes

  • Rising reinsurance costs for insurers
  • Increased frequency or severity of storms
  • Changes in building codes or loss data
  • Market shifts affecting carrier participation


In our professional experience, regular policy reviews help homeowners stay ahead of these changes rather than reacting after a premium spike.


Using Knowledge to Control Windstorm Costs

While no one can control the weather, homeowners do have influence over many pricing factors. Upgrading roof materials, maintaining the property, selecting appropriate deductibles, and reviewing coverage regularly can all help manage windstorm insurance costs.


We’ve worked with homeowners near Bay Street Park and surrounding neighborhoods who were able to improve their pricing position simply by understanding how insurers view risk.


Making Informed Windstorm Insurance Decisions

Windstorm insurance rates vary because risk varies. The more accurately your policy reflects your home’s true risk profile, the more likely you are to secure appropriate coverage at a reasonable cost. Understanding these pricing factors puts you in a stronger position to protect your home and finances.


At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by CLICKING HERE.


Brad Spurgeon Insurance Agency Inc.

Address: Texas City, TX

Phone: (409) 945-4746

Website: www.privatewindstorm.com


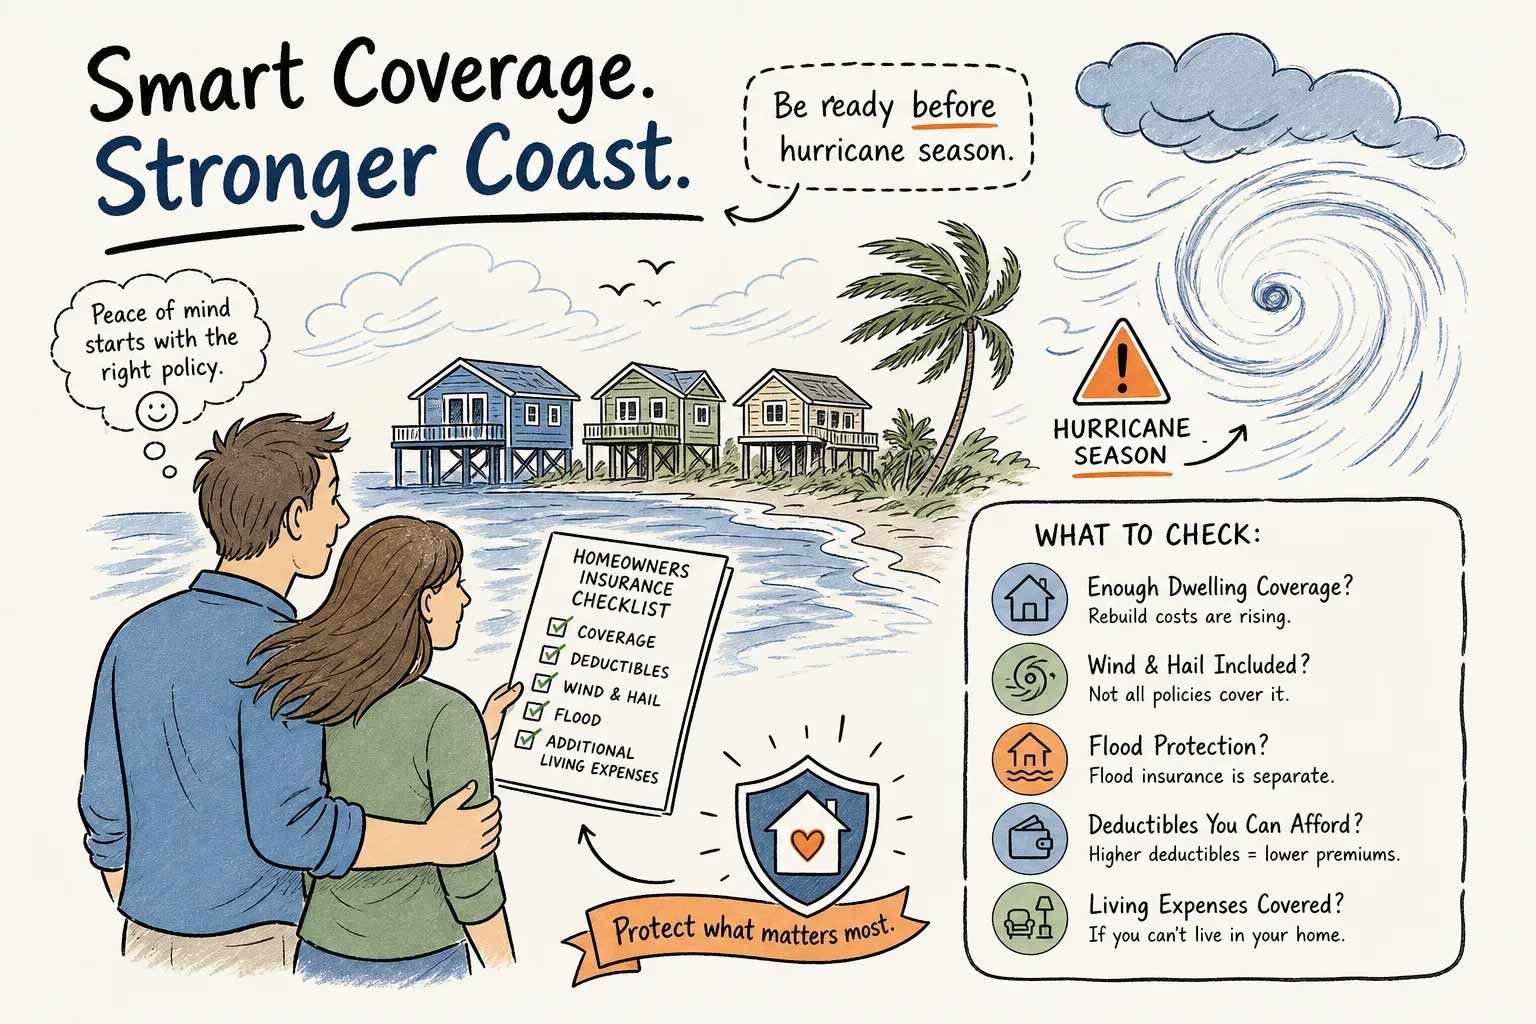
Coastal flood-preparedness infographic with couple, storm clouds, rising water, and checklist for home protection
By Brad Spurgeon • October 12, 2026
A homeowner in Texas City had been paying her homeowners insurance premiums faithfully for years. When a named storm rolled through Galveston County and tore shingles off her roof, she filed her claim confident her policy had her back. What she didn't know, and what nobody had told her, was that windstorm damage had been quietly excluded from her standard policy. The payout she expected? It wasn't coming. That conversation, the one that happens after a hurricane instead of before it, is exactly what we work to prevent at Brad Spurgeon Insurance Agency Inc. We're a family agency that has been serving Texas City and the Gulf Coast for decades, and we've seen this scenario more times than we'd like. The good news: once you understand how homeowners insurance actually works on the coast, protecting yourself completely is straightforward. This article walks you through what's covered, what's not, and the specific steps to get fully protected before hurricane season starts.
September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
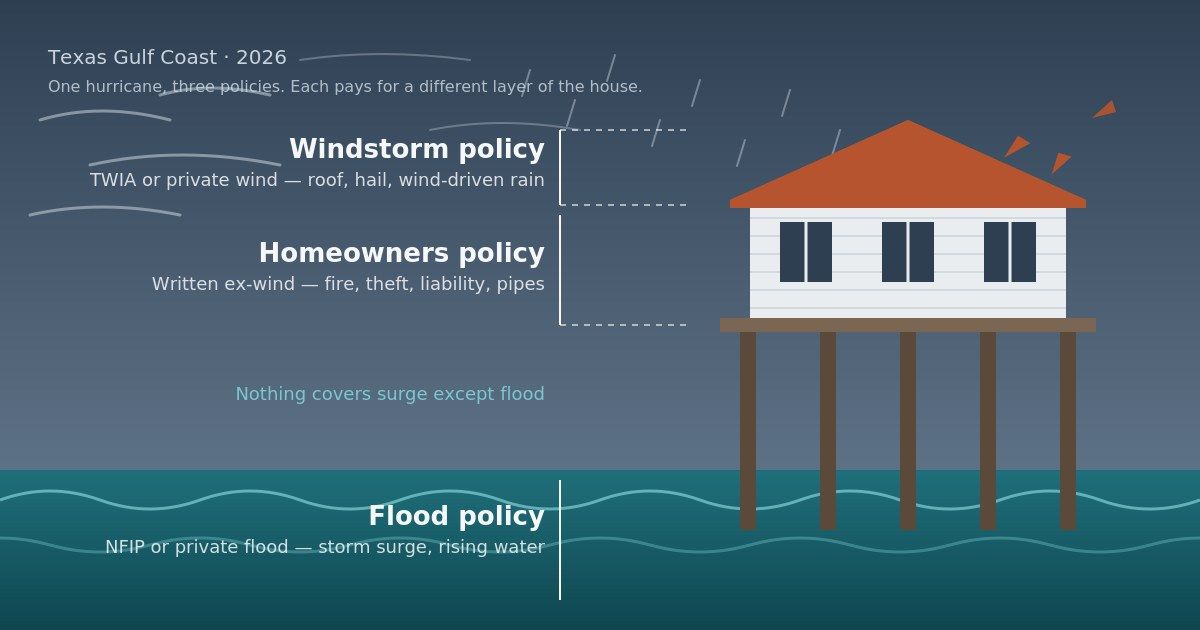
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
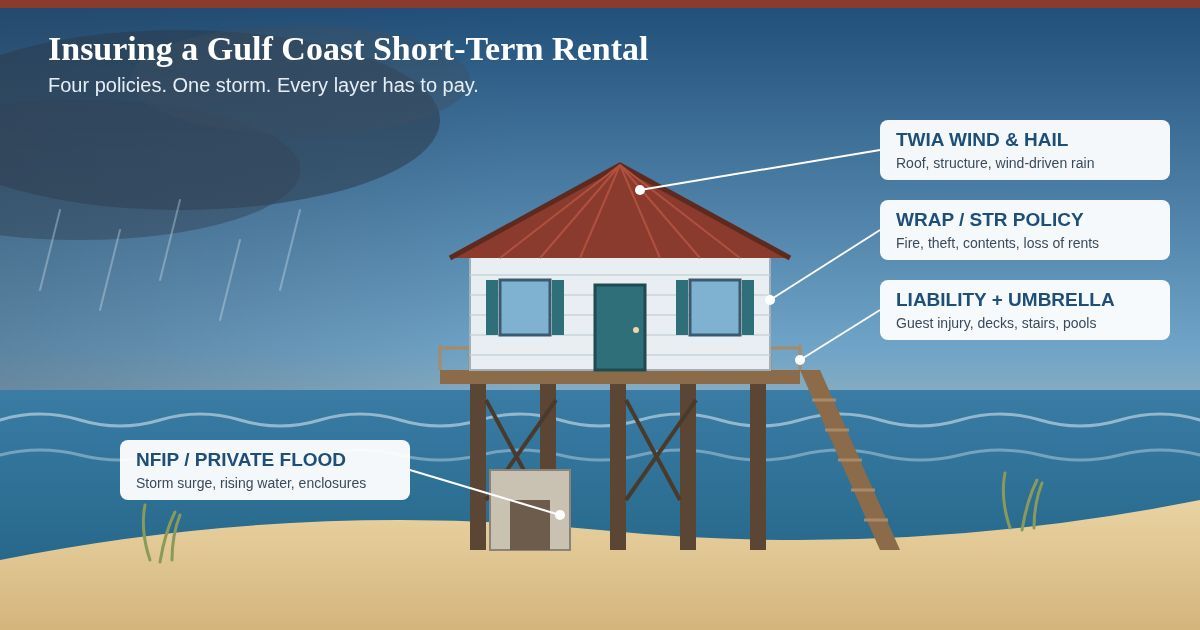
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
August 25, 2026
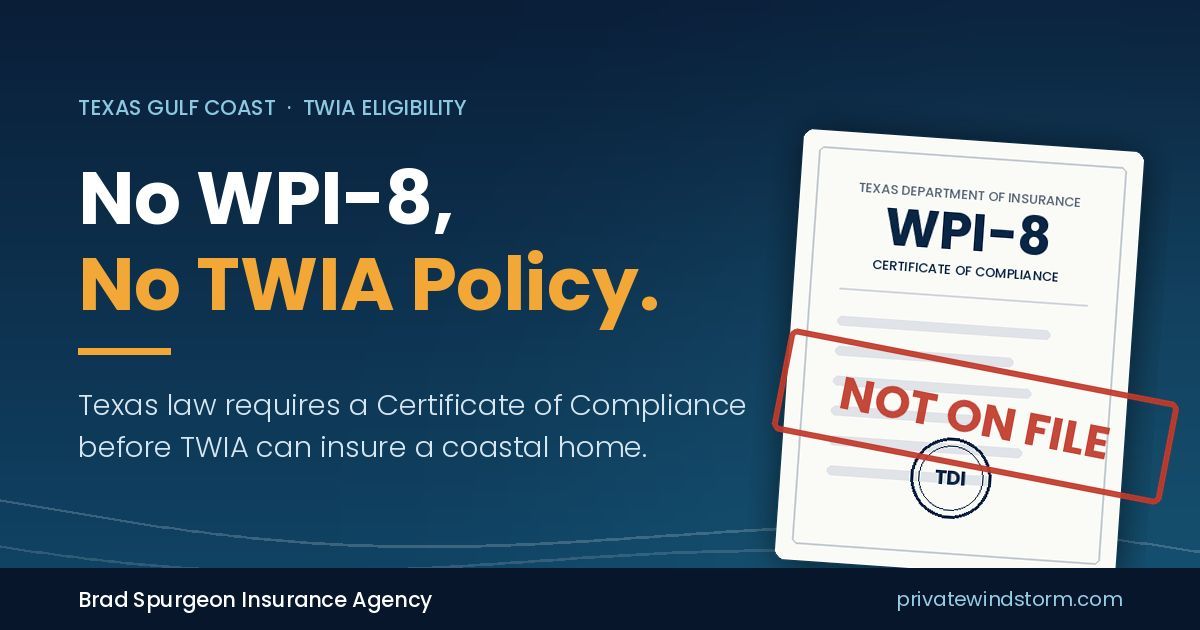
Learn why TWIA requires WPI-8 certification, which Texas coastal homes need it, key exceptions, and what to do if your certificate is missing.
A smiling parent sits on a couch and lifts a happy young child
August 19, 2026
Kids explore everything, and that curiosity is part of what makes childhood fun — but it also means everyday spaces in your home can hide risks you might not think twice about as an adult. A few thoughtful changes around the house can prevent the kinds of accidents that send families to the emergency room every year.
A view of two suburban houses
August 17, 2026
It's a question we hear often in Texas City, especially once a tropical system starts showing up in the forecast: can I still get flood insurance now, or is it too late? The honest answer is that it depends on your policy type and timing, and understanding how flood insurance waiting periods work can save you from a co
Show More