Avoid Coverage Gaps: Adjusting Windstorm Insurance After Renovations

February 10, 2026
A person in a hard hat inspects a construction site.

Renovations can quietly create windstorm insurance gaps because they change what your property would cost to rebuild and can introduce new materials, roof shapes, and structural features that affect how a claim is settled. The safest approach is to update your windstorm coverage immediately after major upgrades—especially roofs, additions, and exterior improvements—so your policy limits, deductibles, and endorsements match the home you actually have today.


After a renovation, most homeowners feel more protected—new roof, stronger windows, upgraded siding, improved finishes. In our years of professional service, we’ve seen the opposite happen on paper: the home becomes more expensive to repair or rebuild, but the insurance still reflects the “before” version. For property owners in Texas City, TX, this mismatch is one of the most common reasons a windstorm claim becomes stressful—because the policy wasn’t adjusted after the value and risk profile changed.


Renovations don’t just increase value. They can change:

  • Replacement cost (materials and labor
  • Building code requirements (especially if a large portion of the home is touched)
  • Wind resistance (positively or negatively, depending on workmanship and design)
  • Claim settlement outcomes if coverage limits and endorsements are outdated


This article explains what typically triggers windstorm gaps, what to update, and how to document improvements so your insurance responds as expected.


What “coverage gap” really means after you renovate. 
A coverage gap is any situation where your policy doesn’t match your current rebuild exposure. That could mean you’re underinsured, missing endorsements, or stuck with claim limits that don’t reflect upgraded materials.


Common renovation-driven gaps include:

  • Dwelling limit is too low to rebuild the renovated home
  • Roof coverage is restricted or scheduled incorrectly (older roof endorsements, cosmetic exclusions, or replacement settlement differences)
  • Deductible is now too high for your new replacement cost
  • Ordinance or law coverage is insufficient after major work triggers code upgrades
  • Added structures or features weren’t disclosed (detached garage upgrades, covered patios, outdoor kitchens, fences)
  • Higher-value finishes are not accounted for (custom cabinets, stone counters, premium flooring)


Experience-based insight: Most people focus on “Did the renovation increase my home’s value?” The better question is “Did the renovation increase what it would cost to rebuild after a windstorm?” Those are not the same number.


Renovations that most often require windstorm insurance updates

Some upgrades create minor changes. Others materially alter risk and rebuild cost—meaning your windstorm setup should be reviewed.


The biggest triggers:

Roof replacement or major roof modifications

  • Changing roof shape, pitch, decking, underlayment, vents, or materials
  • Adding skylights or solar (roof penetrations and attachment methods matter)


Impact windows, doors, and shutter

  • These can improve resistance, but only if properly installed and documented


Additions and expansions

  • New square footage increases replacement cost and often triggers code issues


Exterior envelope upgrades

  • New siding, soffits, fascia, garage doors, and reinforced openings


Structural work

  • Changes to trusses, framing, load-bearing walls, or attached structures


Detached structures and property features

  • Upgraded garages, sheds, fencing, pergolas, and patios


Homes closer to the bay-facing side of the area—especially where storm gusts and wind-driven rain can punish roofs and openings—tend to experience “hidden damage” scenarios. Strong documentation and correct coverage make a major difference in claim handling.


Why roof updates are the #1 reason windstorm claims go sideways

Windstorm claims often revolve around the roof because it’s both expensive and highly scrutinized. After renovations, roof-related gaps show up in a few predictable ways:

  • The insurer still has the old roof age/material on file
    If your policy thinks you have an older roof, settlement may be reduced or coverage may be restricted

  • The roof upgrade raised replacement cost, but your dwelling limit wasn’t increased
    Underinsurance can reduce the amount paid, even when the loss is covered

  • Your policy has cosmetic damage limitations or specific roof endorsements
    Some endorsements limit payment for certain roof damage types unless specific criteria are met

  • Deductibles weren’t recalculated against new rebuild costs
    A percentage-based wind deductible on a higher-value home means you pay much more out of pocket


Practical takeaway: If you replace a roof, you should treat your insurance update as part of the project closeout—just like final inspections and warranty paperwork.


What to update after you renovate (the windstorm insurance essentials)

To prevent gaps, your review should cover the full windstorm picture, not just one number.


Key updates to request:

1. Rebuild-focused dwelling limit update

  • Confirm the dwelling limit is based on replacement cost, not market value
  • Make sure the updated limit reflects:
    New square footage
    Higher-grade finishes
    Current labor/material pricing
    Debris removal and contractor demand after storms


2.Wind deductible review

  • Many windstorm setups use a separate wind/hurricane deductible
  • Confirm:
    Whether it is a flat dollar amount or a percentage
    What the percentage applies to (often the dwelling limit)
    Whether you can adjust it to better fit your risk tolerance


  • Example of why this matters:
    A 2% deductible on a $400,000 dwelling limit is $8,000 out of pocket
    If your dwelling limit should be $550,000 after renovations, that same 2% becomes $11,000


3.Roof settlement terms and endorsements

  • Confirm whether roof losses are settled at replacement cost or actual cash value
  • Ask about endorsements that may apply to:
    Older roofs
    Cosmetic damage limitations
    Percentage of replacement cost
    Material-specific restrictions


4.Ordinance or law coverage

Renovations can increase the chance that rebuilding will require code upgrades. Ordinance or law coverage helps pay for:

  • Code-required upgrades during rebuild
  • Bringing parts of the home up to current standards
  • Additional costs beyond basic “like kind and quality” replacement


5.Other structures and exterior upgrades

  • Update coverage for detached garages, sheds, fences, pools, and upgraded patios
  • If you added an outdoor kitchen or specialty structures, make sure they’re included and valued appropriately


6.Personal property and special items (if relevant)

A renovation often comes with new furnishings, electronics, appliances, and tools.

  • Update personal property limits if you upgraded significantly
  • Consider scheduling high-value items if they exceed standard sub-limits


In Texas City, TX, where wind events can produce widespread damage and contractor demand spikes after storms, correct limits and clear roof terms help you avoid paying thousands more than expected.


Documentation: the difference between a smooth claim and a frustrating one

In our years of professional service, the homeowners who experience the least claim friction are the ones who can prove what was installed, when it was installed, and how it was installed.


Keep a digital folder with:

  • Contractor invoices and paid receipt
  • Permits and inspection sign-offs
  • Roof warranty documents (manufacturer + workmanship)
  • Product specs (impact windows, garage doors, shutters)
  • “Before and after” photos (especially roof decking/underlayment and attachment points)
  • Any engineering reports (if you reinforced roof-to-wall connections or did structural work)


Why it matters:

  • It helps confirm material grade and age
  • It supports accurate valuation and settlement
  • It reduces “we need more info” delays during claims


Common mistakes after renovations (and how to avoid them)

These are the pitfalls we see repeatedly:

  • Waiting until renewal to update the policy
    Renovations should trigger an immediate review, not a “we’ll deal with it later” approach

  • Assuming your agent or insurer “will know”
    Insurers rely on reported changes and periodic inspections; they don’t automatically know what you upgraded

  • Not reviewing wind deductibles after increasing dwelling limits
    Your deductible can quietly become much larger than you expect

  • Focusing only on the roof and forgetting ordinance/law coverage
    Code upgrades can be a major portion of rebuild costs after a windstorm loss

  • Not keeping documentation
    If you can’t prove it, it can be harder to get paid for it the way you expect


Conclusion

Renovations can strengthen your home, but they can also create expensive coverage gaps if your windstorm policy isn’t updated to match the new rebuild cost and risk profile. The best time to review your windstorm setup is immediately after major projects—especially roof work, additions, and exterior upgrades—so your limits, deductibles, and endorsements reflect today’s reality. For homeowners in Texas City, TX, this step can be the difference between a manageable out-of-pocket expense and an unexpected financial hit after the next major wind event.


At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by CLICKING HERE. 


Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.


Brad Spurgeon Insurance Agency

Texas City, TX

(409) 945-4746

https://www.privatewindstorm.com/

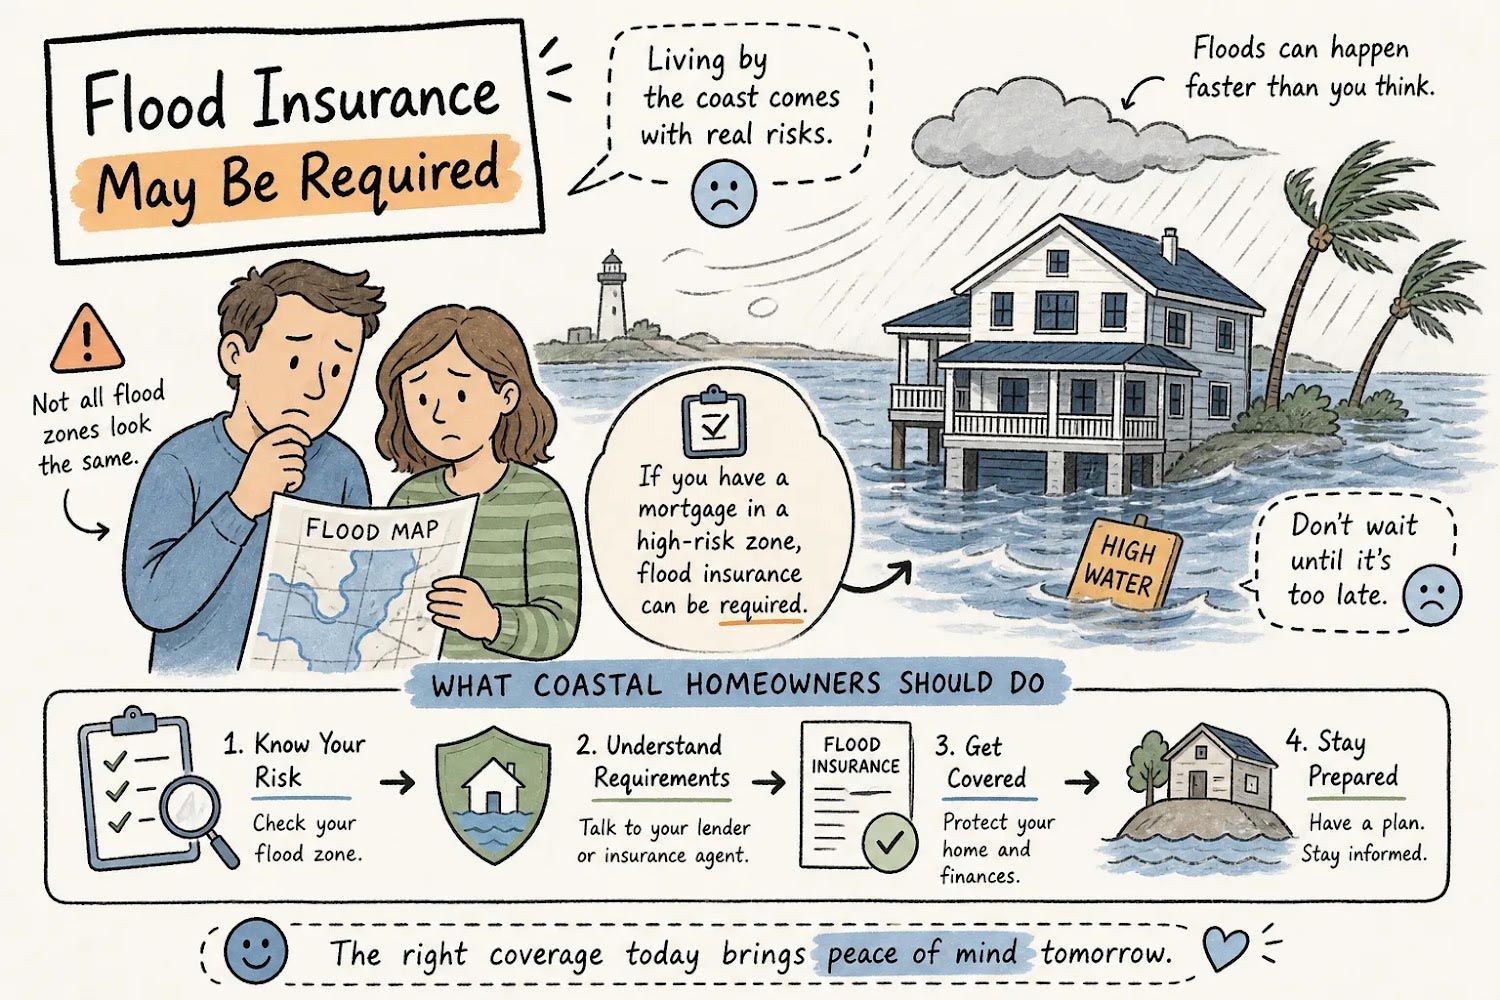
Flood insurance explainer infographic with a house, worried couple, and tips about flood risk and coverage
By Brad Spurgeon • November 16, 2026
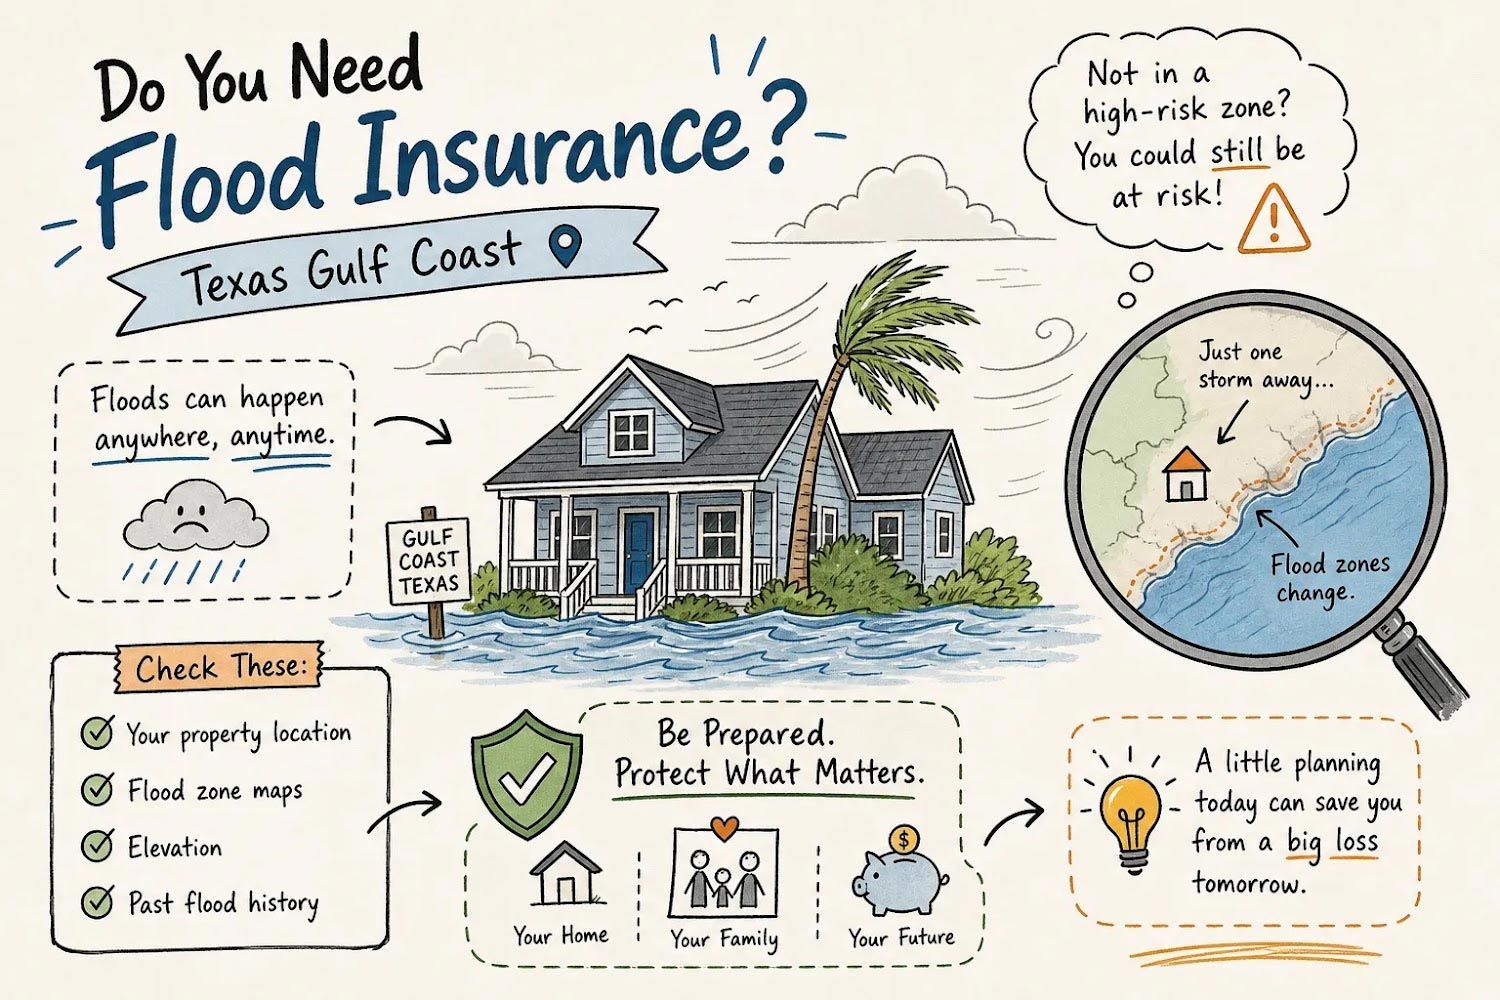
Flood insurance is required for properties located in a FEMA-designated Special Flood Hazard Area when the mortgage is federally backed or made by a federally regulated lender. Both conditions must be true at the same time. Having a federally backed loan does not trigger the requirement on its own, and being in a high-risk flood zone does not trigger it either if your financing is fully private. When both boxes are checked, coverage is mandatory for the life of the loan, and your lender enforces it. For Texas Gulf Coast homeowners, flood risk does not arrive alone. Storm surge, windstorm exposure, and hurricane activity all layer on top of the basic flood question, and the gaps between standard insurance policies can leave a claim partially or entirely uncovered. This article walks through the key situations that trigger mandatory flood coverage, how to verify your flood zone, and how to build a complete coastal insurance strategy.
Collage of travel scrapbook pages with “Cover the Gap,” a couple by the sunset, and a desert road trip theme
By Brad Spurgeon • November 16, 2026
Gap coverage insurance pays the difference between what you still owe on your car loan or lease and what your insurer actually pays out after a total loss. Guaranteed asset protection, the full name behind the acronym, is the product that closes that hole. If you financed or leased a vehicle in the last few years, this article is worth reading before you assume you're fully covered.
Flood insurance infographic for Texas Gulf Coast homes, with storm surge map and preparedness tips.
By Brad Spurgeon • November 16, 2026
Does my property require flood insurance? If you have a federally backed mortgage and your home sits in a FEMA-designated AE or VE flood zone, flood insurance is required by federal law. That is the short answer. If you are not sure which zone your property falls into, or you have heard conflicting things from your lender, your real estate agent, and your neighbor, conflicting guidance is common along the Texas Gulf Coast due to frequent remapping and local ordinance variability. The Gulf Coast carries unique flood exposure. Roughly 23,000 to 25,000 residential properties in Galveston County alone are mapped inside FEMA Special Flood Hazard Areas, according to a residence-level FEMA-zone analysis. The question homeowners here face is rarely as simple as "do I need it?" More often, it is "does the law require it, and is what I have actually enough?" This guide walks through the exact steps to check your flood zone, understand your lender's requirements, weigh NFIP against private coverage, and figure out your next move.
November 11, 2026
Flooding can cause extensive property damage, leaving homeowners with important decisions about repairs, documentation, and insurance claims. For residents of Texas City, TX, understanding when to report flood damage is especially valuable because coastal storms and heavy rainfall can create unexpected flooding risks.
November 11, 2026
Living along the Texas Gulf Coast means preparing for powerful winds, hurricanes, and unpredictable weather conditions. For homeowners in Texas City, TX, having windstorm insurance is an important step, but understanding additional coverage options can make a meaningful difference. Windstorm insurance riders may provid
November 10, 2026
A burst pipe can release significant amounts of water into a home, damaging floors, walls, furniture, and personal belongings within minutes. For homeowners in Texas City, TX, understanding how insurance responds to unexpected plumbing problems is an important part of protecting their property. Knowing which types of w
November 10, 2026
Protecting a home along the Texas Gulf Coast requires understanding how different insurance policies respond to property damage. For homeowners in Texas City, TX, comparing homeowners insurance and windstorm insurance is especially important because coastal properties may have unique coverage requirements. Knowing how
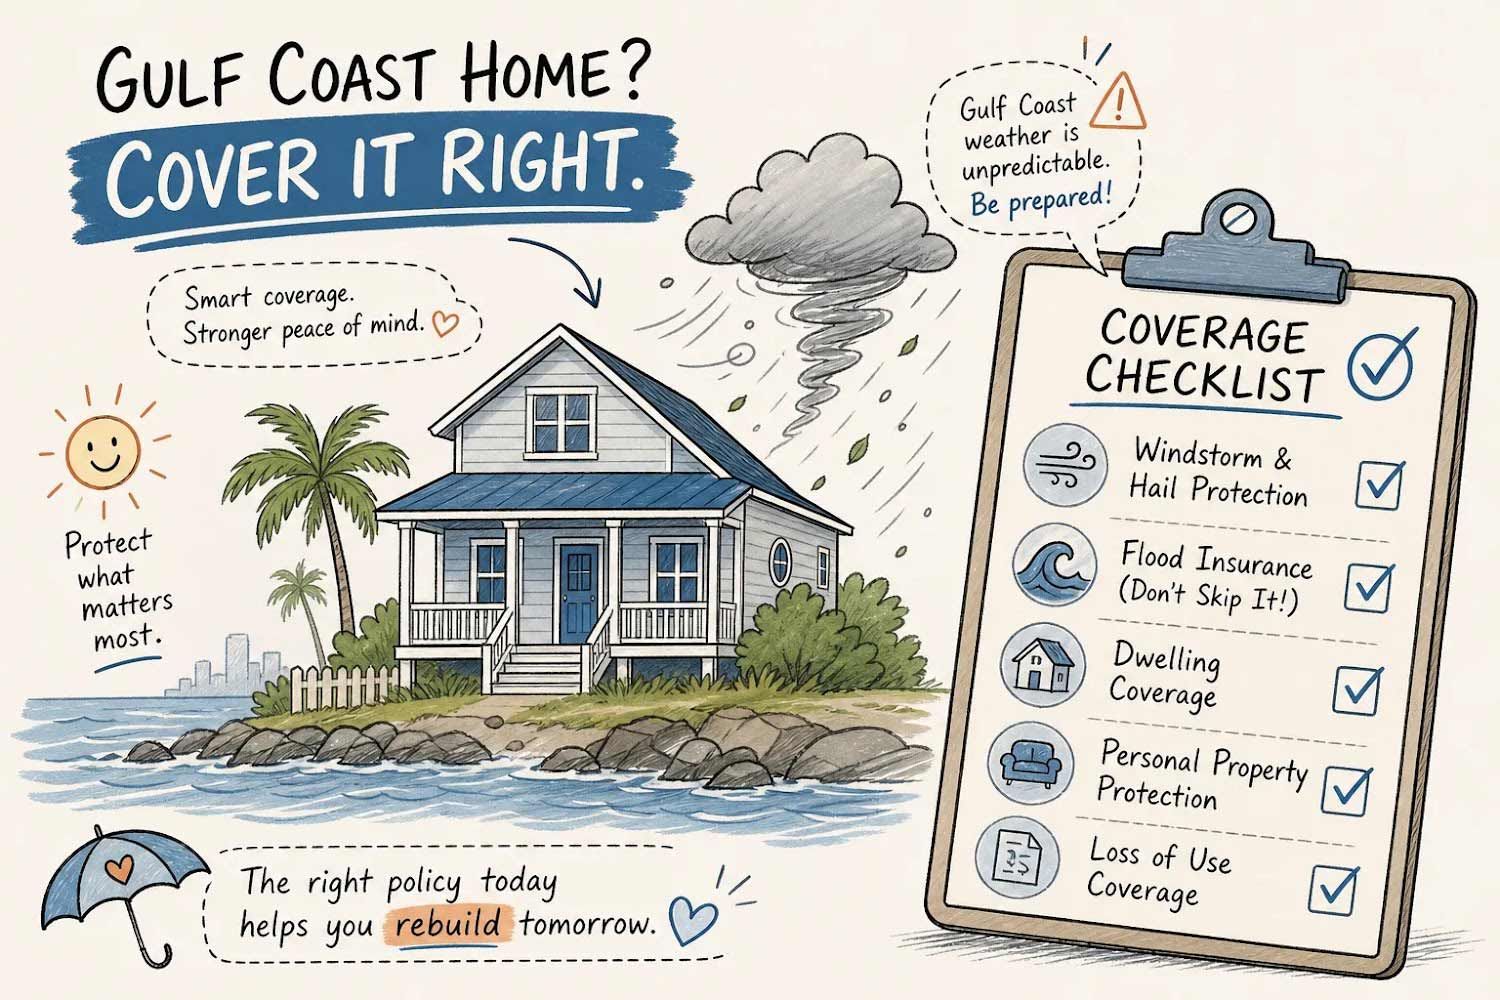
Illustrated coastal home under storm clouds with roof and drainage checklist for hurricane preparedness
By Brad Spurgeon • November 2, 2026
When buying on the Gulf Coast, understanding home owners insurance in Texas is essential, because a standard HO-3 policy covers fire, theft, and many everyday perils, but excludes windstorm, hail, and flood in most coastal counties. That means a single hurricane can trigger three separate claims under three separate policies, and if you only carry one policy, two of those losses come out of your own pocket. This checklist walks through what each layer covers, what it costs in 2026, and which option closes all three gaps most efficiently. Whether you're closing on a home next week or reviewing a policy you've had for years, the sequence below gives you a clear path forward.
TW login screen with woman at laptop, smiling and pointing at a sign-in panel with security icons and house illustration
By Brad Spurgeon • November 2, 2026
If you're searching for a TW login and you live on the Texas Gulf Coast, you're likely trying to reach one of two portals: the Texas Windstorm Insurance Association (TWIA) policyholder site or your insurance agency's online client account. TWIA uses "TW" prominently in its name and branding, and it's the essential portal for managing windstorm and coastal home coverage. Knowing which portal you need, and what to expect at the sign-in screen, makes the whole process much simpler. This guide covers the most common TW portals Gulf Coast homeowners land on, how to log into each one, how to fix errors that block access, how to recover a forgotten password, and how to verify you're on a legitimate page before you type a single credential. And if you still can't get through, Brad Spurgeon Insurance Agency Inc., a third-generation family-owned agency serving the Texas Gulf Coast since 1986, can walk you through it directly.
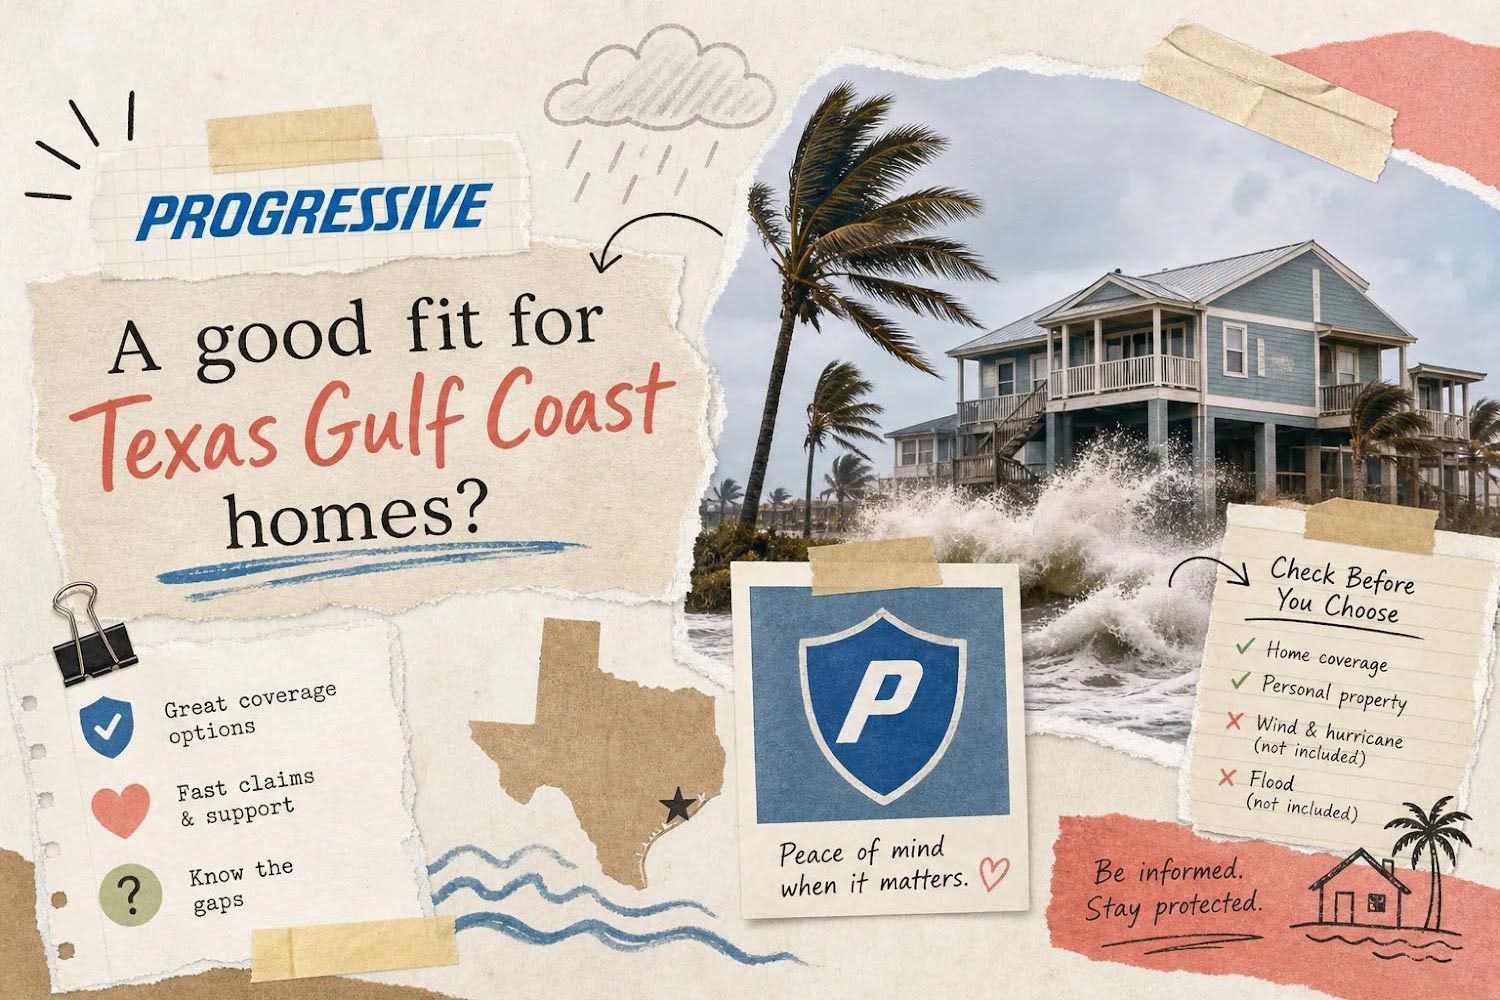
Progressive ad: “A good fit for Texas Gulf Coast homes?” with beach house, storm surf, and map graphic
By Brad Spurgeon • October 29, 2026
Progressive home insurance offers standard HO-3 coverage that works well for most American homeowners, but for Texas Gulf Coast properties, that base policy typically excludes the two biggest threats in the region: windstorm damage and flooding. Those aren't minor omissions for a home in Galveston County or along the Brazoria coastline. They're exactly what a hurricane or tropical storm delivers. Texas already carries some of the highest home insurance premiums in the country, and coastal ZIP codes push that figure even further above the national average. Spending that much on a policy that leaves windstorm and flood damage uncovered is a critical mistake. This article breaks down what progressive home insurance actually includes, where it falls short for coastal properties, and what a complete coverage picture looks like.
Show More