What Happens When You Don’t Have Enough Home Coverage?

December 10, 2025
A large, multi-story white house with dormer windows sits on a grassy lawn under a blue, cloudy sky.

Your home is one of your biggest investments—financially and emotionally. But many homeowners don’t realize they’re underinsured until disaster strikes. Whether it’s a house fire, storm damage, or a major plumbing failure, inadequate home coverage can turn an already stressful event into a financial crisis.


Understanding what happens when you don’t have enough home insurance is essential for protecting your property, your wallet, and your peace of mind. This guide explains the risks of being underinsured and how to make sure your policy truly safeguards your home.


What Does It Mean to Be Underinsured?

Being underinsured means your homeowner’s insurance policy does not provide enough coverage to fully repair or rebuild your home after a loss.

This often happens because homeowners:

  • Select coverage based on their home’s market value, not its replacement cost
  • Forget to update their policy after renovations or additions
  • Choose lower coverage limits to reduce premiums
  • Don’t fully understand included (and excluded) protections


In fast-growing areas or coastal regions like Texas City, TX, repair and labor costs can rise quickly—making accurate coverage more important than ever.


What Happens When Your Home Is Underinsured?

1. You May Have to Pay Thousands—Or More—Out of Pocket

If the cost to rebuild your home exceeds your coverage limit, you are responsible for the remainder. Even a small gap can add up fast.

Example:

If your home requires $300,000 to rebuild but you’re only insured for $220,000, you must pay the additional $80,000 yourself.


2. You Could Face a Coinsurance Penalty

Many homeowners policies include a coinsurance clause, which requires you to insure your home for a specific percentage of its replacement cost (usually 80%–100%).

If you fall below that threshold—even by accident—you may receive only a partial payout for your claim.


3. You May Not Have Enough Coverage for Detached Structures

Detached garages, sheds, fencing, and other outdoor features are often covered as a percentage of your dwelling amount. If your dwelling coverage is too low, every other structure’s coverage automatically drops as well.


4. Your Personal Belongings May Be Underprotected

Your personal property coverage is typically set as a percentage of your dwelling limit. Underinsuring your home also underinsures your belongings—including furniture, electronics, clothing, and valuables.


5. Temporary Living Expenses Might Not Be Fully Covered

If your home becomes uninhabitable, loss of use coverage helps pay for hotel stays or temporary housing. But if your main policy limit is too low, these benefits may cap out quickly—leaving you to cover the remaining costs.


6. Renovations or Improvements May Not Be Covered

Many homeowners complete upgrades—new kitchens, flooring, room additions—without notifying their insurance carrier. If your home value increases but your coverage doesn’t, your policy will not reflect the true cost of repairs.


7. Mortgage Requirements Could Be Impacted

Lenders require adequate insurance to protect their investment. If they determine your coverage is too low, they may:

  • Require additional insurance
  • Place costly lender-issued coverage on your policy
  • Delay refinancing or home-equity approvals


For homeowners in Texas City, TX, choosing adequate home coverage is especially important due to storm risks, rising construction costs, and ongoing property development. Ensuring your policy reflects accurate replacement costs can help prevent financial hardship after a major loss.


How to Make Sure You Have Enough Home Coverage

  • Insure Your Home to Its Full Replacement Cost
    This is the amount needed to rebuild—not sell—your home.

  • Review Your Policy Every Year
    Costs change, and your insurance should too.

  • Update Your Carrier After Renovations
    Even small improvements affect your replacement value.

  • Inventory Your Belongings
    Photo or video documentation makes claim processing easier.

  • Consider Extended or Guaranteed Replacement Cost Coverage
    These upgrades provide protection if rebuilding costs exceed your limits.

  • Ask About Ordinance & Law Coverage
    This covers the extra costs of bringing your home up to current building codes after a loss.


The Long-Term Impact of Being Underinsured

Choosing lower coverage to save money may feel smart in the short term—but it can lead to:

  • Significant debt
  • Delayed repairs
  • Incomplete rebuilding
  • Loss of property value
  • Financial strain for your family


Adequate home insurance ensures you can rebuild your life—not just your house—after a major loss.


Conclusion

Not having enough home coverage can leave you financially vulnerable when disaster strikes. From out-of-pocket repair costs to coinsurance penalties and insufficient personal property protection, the consequences can be overwhelming.


By reviewing your policy regularly, understanding your replacement costs, and adjusting your coverage as needed, you can protect your home, your investment, and your future.


At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by 
CLICKING HERE. 


Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.

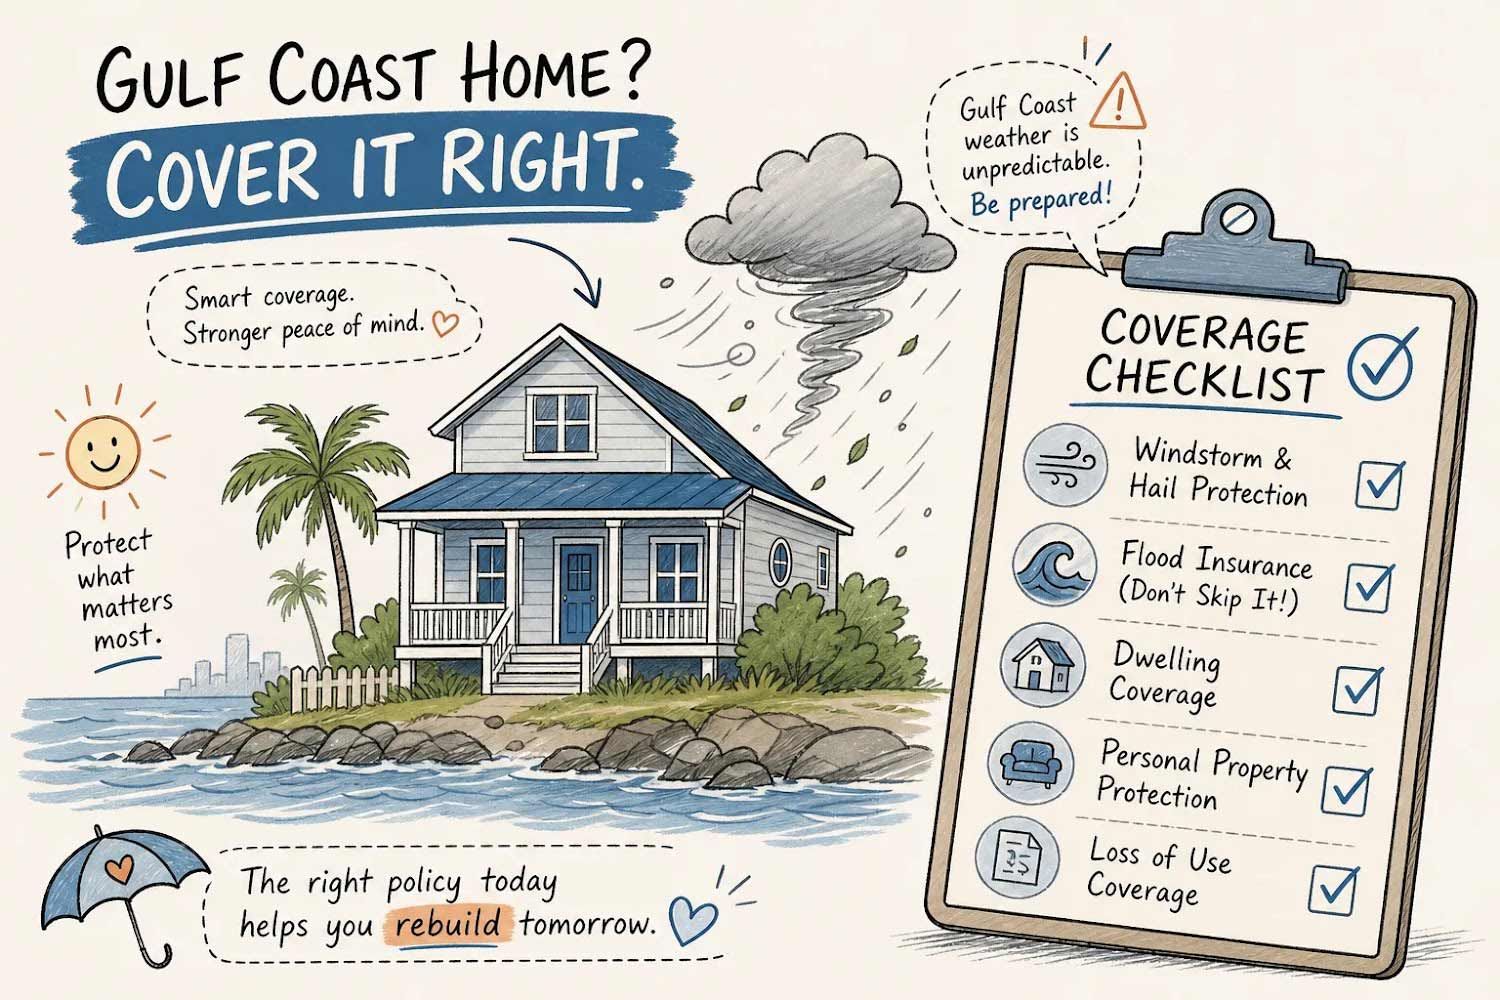
Illustrated coastal home under storm clouds with roof and drainage checklist for hurricane preparedness
By Brad Spurgeon • November 2, 2026
When buying on the Gulf Coast, understanding home owners insurance in Texas is essential, because a standard HO-3 policy covers fire, theft, and many everyday perils, but excludes windstorm, hail, and flood in most coastal counties. That means a single hurricane can trigger three separate claims under three separate policies, and if you only carry one policy, two of those losses come out of your own pocket. This checklist walks through what each layer covers, what it costs in 2026, and which option closes all three gaps most efficiently. Whether you're closing on a home next week or reviewing a policy you've had for years, the sequence below gives you a clear path forward.
TW login screen with woman at laptop, smiling and pointing at a sign-in panel with security icons and house illustration
By Brad Spurgeon • November 2, 2026
If you're searching for a TW login and you live on the Texas Gulf Coast, you're likely trying to reach one of two portals: the Texas Windstorm Insurance Association (TWIA) policyholder site or your insurance agency's online client account. TWIA uses "TW" prominently in its name and branding, and it's the essential portal for managing windstorm and coastal home coverage. Knowing which portal you need, and what to expect at the sign-in screen, makes the whole process much simpler. This guide covers the most common TW portals Gulf Coast homeowners land on, how to log into each one, how to fix errors that block access, how to recover a forgotten password, and how to verify you're on a legitimate page before you type a single credential. And if you still can't get through, Brad Spurgeon Insurance Agency Inc., a third-generation family-owned agency serving the Texas Gulf Coast since 1986, can walk you through it directly.
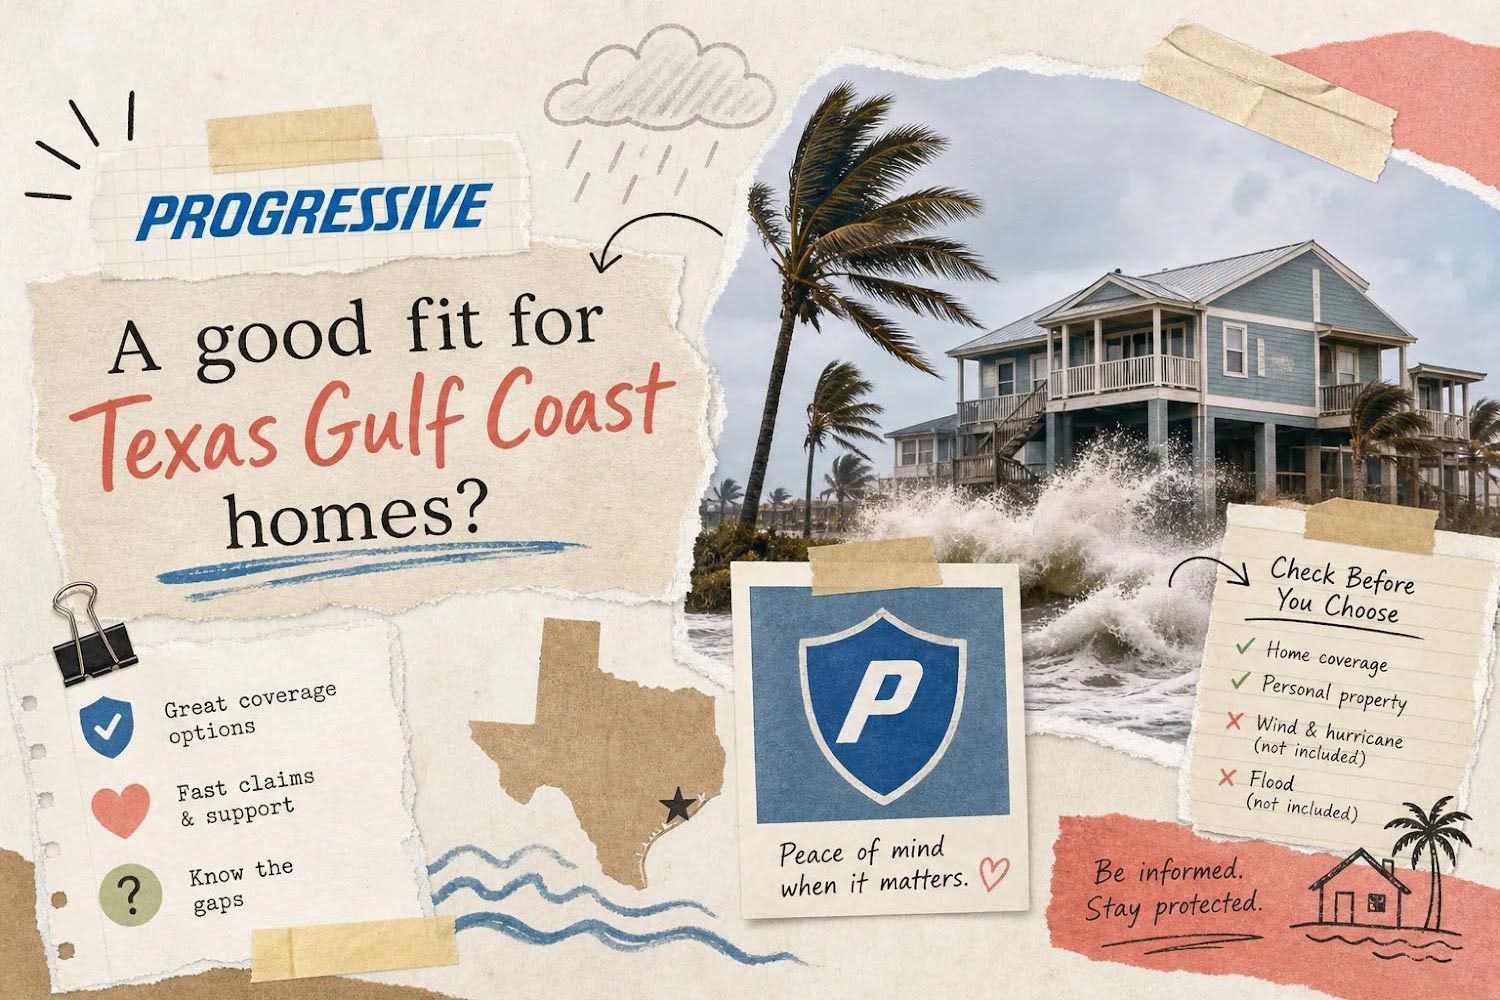
Progressive ad: “A good fit for Texas Gulf Coast homes?” with beach house, storm surf, and map graphic
By Brad Spurgeon • October 29, 2026
Progressive home insurance offers standard HO-3 coverage that works well for most American homeowners, but for Texas Gulf Coast properties, that base policy typically excludes the two biggest threats in the region: windstorm damage and flooding. Those aren't minor omissions for a home in Galveston County or along the Brazoria coastline. They're exactly what a hurricane or tropical storm delivers. Texas already carries some of the highest home insurance premiums in the country, and coastal ZIP codes push that figure even further above the national average. Spending that much on a policy that leaves windstorm and flood damage uncovered is a critical mistake. This article breaks down what progressive home insurance actually includes, where it falls short for coastal properties, and what a complete coverage picture looks like.
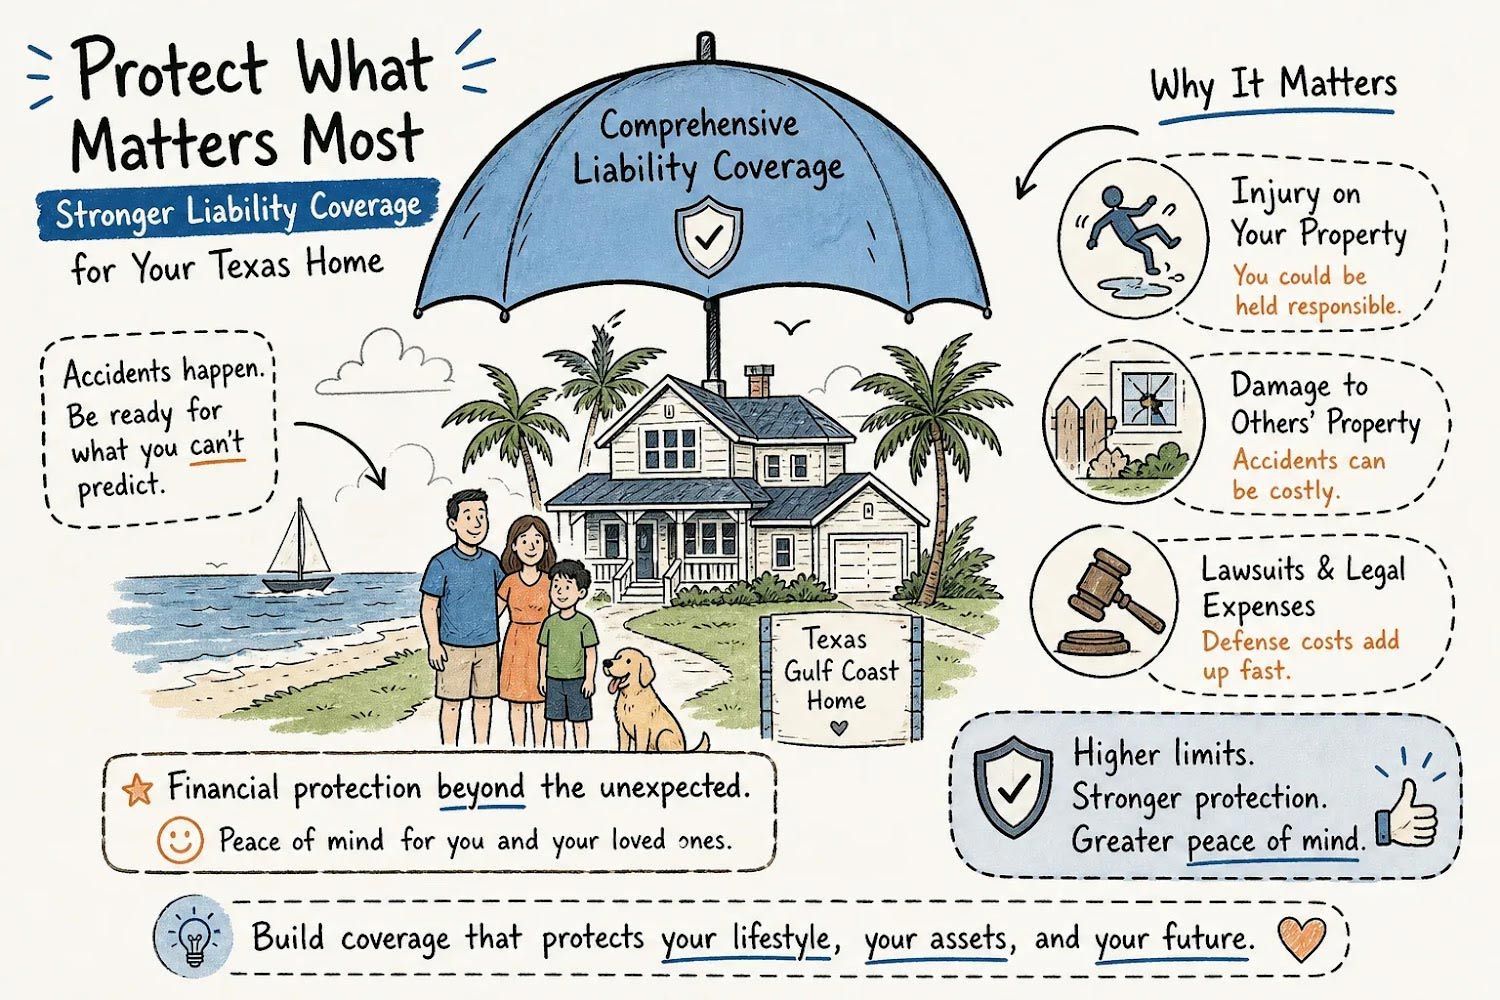
Infographic on flood insurance, showing a house, umbrella, and hurricane tips for protecting belongings and finances.
By Brad Spurgeon • October 29, 2026
Comprehensive personal liability coverage, known as Coverage E in your homeowners or renters policy, pays when someone else is injured on your property or you accidentally damage their property and you're legally responsible. It also covers your legal defense costs, attorney fees, and court judgments up to your policy limit. This guide breaks down exactly what you're covered for, what slips through the gaps, and how to build a comprehensive liability protection stack that actually holds up when a claim lands. Whether you're a first-time buyer in Texas City or a long-time Gulf Coast homeowner juggling a boat, a dog, and a rental unit, getting these limits right matters more here than almost anywhere else in the country.
Coastal home insurance ad with beach house, couple talking, and text “Ask Now, Protect Your Coastal Home”
By Brad Spurgeon • October 22, 2026
What are the most important questions to ask an insurance agent before buying coastal home insurance? Most buyers never think to ask them until after a storm. Many coastal homebuyers report spending more time negotiating kitchen countertops than understanding their insurance policy. That's a reasonable way to live, until a named storm makes landfall and the claim comes back short of what you needed. The policy was there. The coverage wasn't. Wind excluded. Flood not purchased. Deductible never translated into a real dollar amount. The policy looked fine on paper. In practice, it had gaps a storm could drive a boat through. This article gives you the questions that change that. Six categories. Each one designed to reveal whether the agent in front of you truly understands Gulf Coast exposure, or is simply filling in a form.
Handmade collage for
By Brad Spurgeon • October 22, 2026
Progressive home insurance is one of the most recognized products in the country, and that familiarity makes it easy for coastal homeowners to assume the policy covers everything it should. Many homeowners assume the standard policy handles all their risks, wind, water, and everything a Gulf Coast storm can throw at a house. It often leaves critical gaps. Gulf Coast homes face windstorm, flood, and hurricane risks that standard policies routinely exclude, and discovering those exclusions after a storm can lead to large out-of-pocket costs. This checklist walks through what a Progressive homeowners policy actually includes, where it leaves coastal buyers exposed, what it costs in Texas, and how to close the gaps before storm season arrives. We've been working with Gulf Coast homeowners from our base in Texas City since 1986.
October 19, 2026
Flooding can disrupt business operations, damage expensive equipment, and create financial losses that extend well beyond the initial cleanup. For commercial property owners, retailers, and service providers along the Texas Gulf Coast, understanding flood exposure is an important part of risk management. Knowing which
October 19, 2026
A small fire can become a serious emergency in moments. Whether it starts in the kitchen, garage, or another part of the house, knowing how to respond can help protect your family and property.
October 15, 2026
Strong winds from thunderstorms, hurricanes, and tropical storms can cause significant property damage. Missing roof shingles, broken windows, damaged siding, and fallen trees are just a few problems homeowners may discover after severe weather.
October 15, 2026
Flooding can happen quickly, leaving families with little time to protect their homes and reach safety. Heavy rainfall, overflowing waterways, tropical storms, and storm surge can create dangerous conditions, particularly in coastal communities.
Show More