What Is Open Peril Coverage?

June 13, 2022
An exterior view of a 24-hour restaurant at night


In general terms, perils are considered as serious or immediate danger. And in insurance, perils have the same-like definition.


Perils are defined as an event that could cause damage or loss to your home or property in your insurance coverage. It includes human-made or triggered incidents like fire, theft, vandalism, and many more. Hence the existence of peril coverage, which is supposed to protect your home and other properties from these disasters. 


However, there are two common peril coverages: open and named. This article will help you get deep into their definition and differences. 


Get Deep With Open Peril Coverage 

Often called an all-risk coverage, open perils coverage is a form of home or property insurance. It shields against almost every damage except those excluded in the policy. 


Even though dubbed as something that covers “all” risks, there are still some exceptions. And your insurance company surely discussed with you all the exceptions. For a simple refresher, the following incidents are excluded in open perils coverage:


  • Flood.
  • Mudslides.
  • Sewer backups.
  • Power outage.
  • Rust and corrosion.
  • Mechanical breakdowns.
  • Earthquakes.
  • Boiler explosions.
  • Employee theft.
  • Fungus damage.
  • Pests or animals.
  • Pollution.

Most of these mentioned above are natural disasters or are considered unavoidable. 


Difference Between Named Perils and Open Perils

If you’re on the lookout for perils coverage, the two you will encounter the most are open perils and named perils. While the previous claims to be an all-risk and covers nearly every possible damage or loss, named perils are limited. Named perils only pay for specific perils mentioned in your plan. Hence it’s less expensive. 


Aside from coverage and price, what open perils has that separates it from the latter is that it’s not up to you to provide proof. For named perils, you have to be the one to provide your agency evidence that the listed perils caused damage. If you fail to provide, you have to shoulder the expenses. 


However, the latter reason is just a matter of convenience. Choosing between the two depends on how high-risk you think your properties are. If you think you’re more prone to damage, open perils coverage is better. But, if not, named perils can already do the work.


Conclusion

The key differences between named and open perils coverage are price, convenience, and risk coverage. Thus, the decision of which one’s better will only be decided by you. 


At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get the insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by CLICKING HERE. The coverage discussed in this article is not guaranteed. Please call our agents, we are happy to help you learn more about your plan and make sure you have the coverage you need.

October 15, 2026
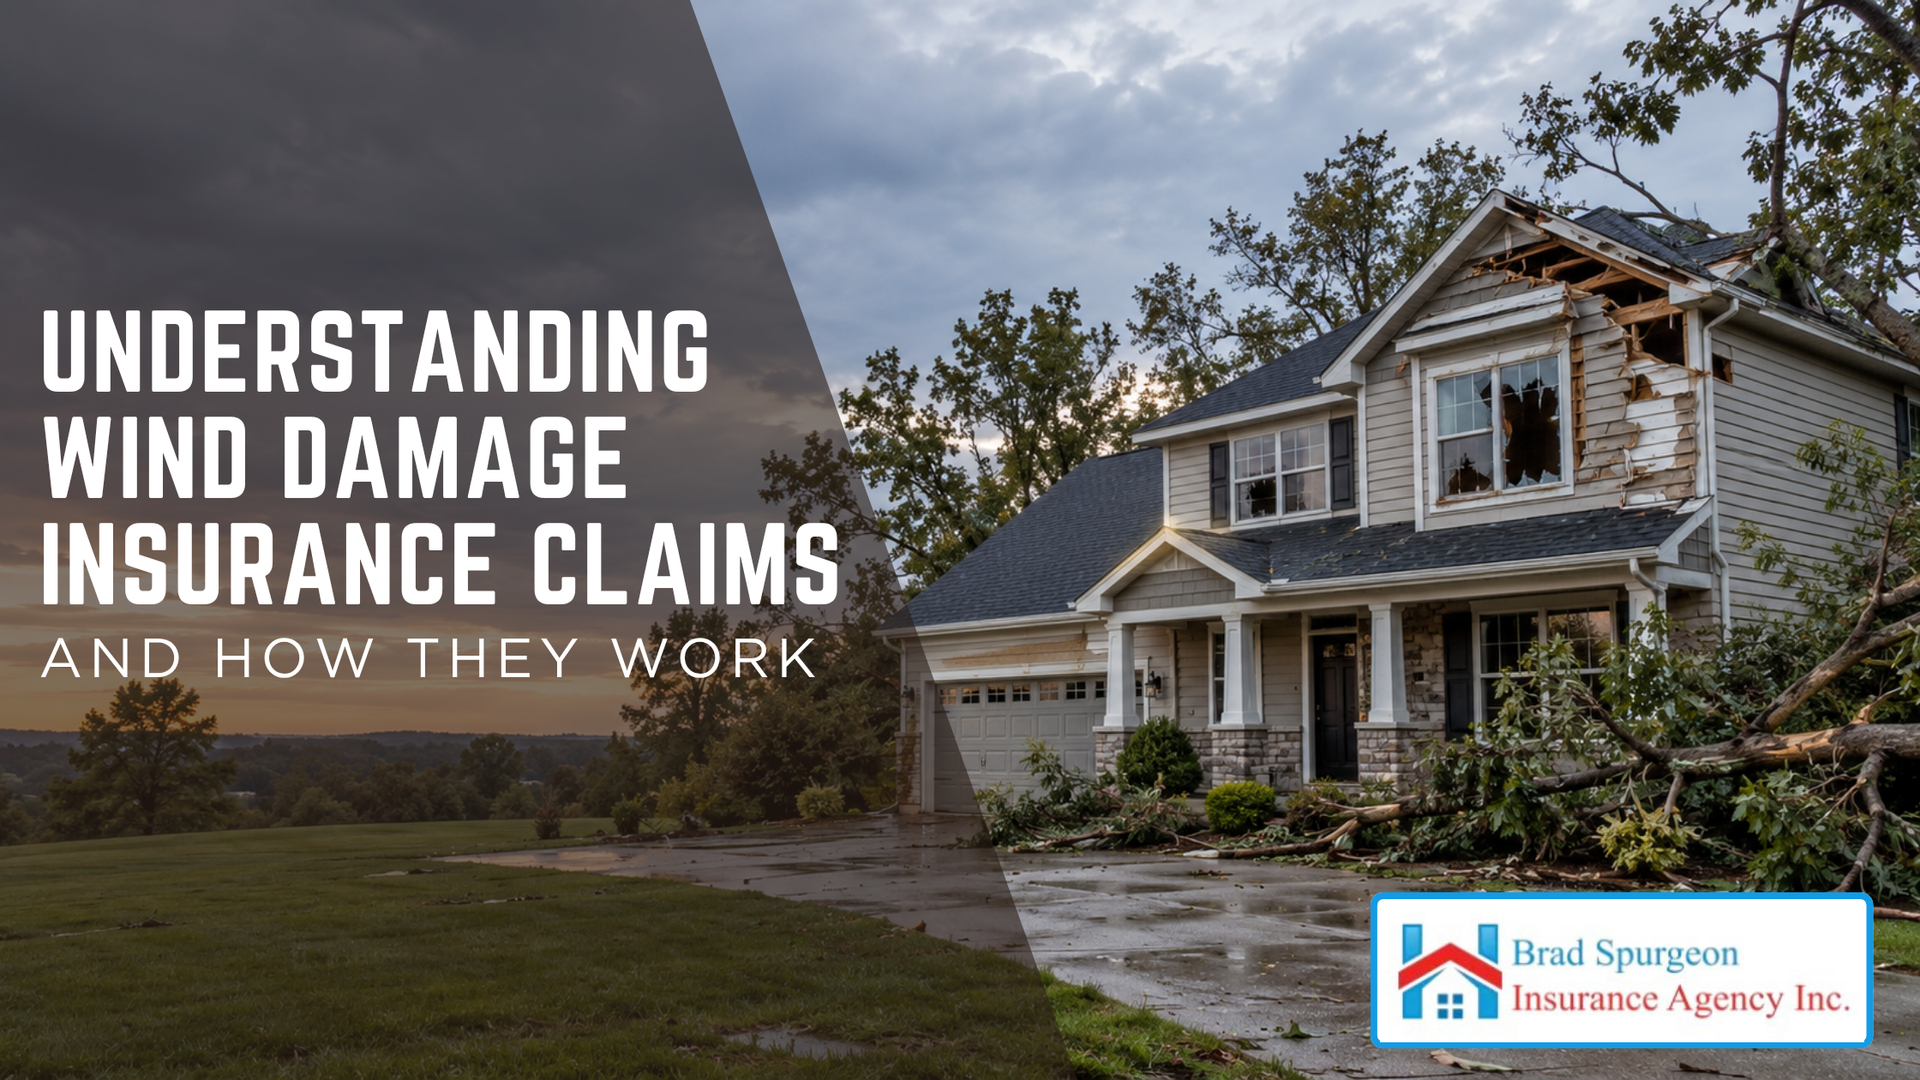
Strong winds from thunderstorms, hurricanes, and tropical storms can cause significant property damage. Missing roof shingles, broken windows, damaged siding, and fallen trees are just a few problems homeowners may discover after severe weather.
October 15, 2026
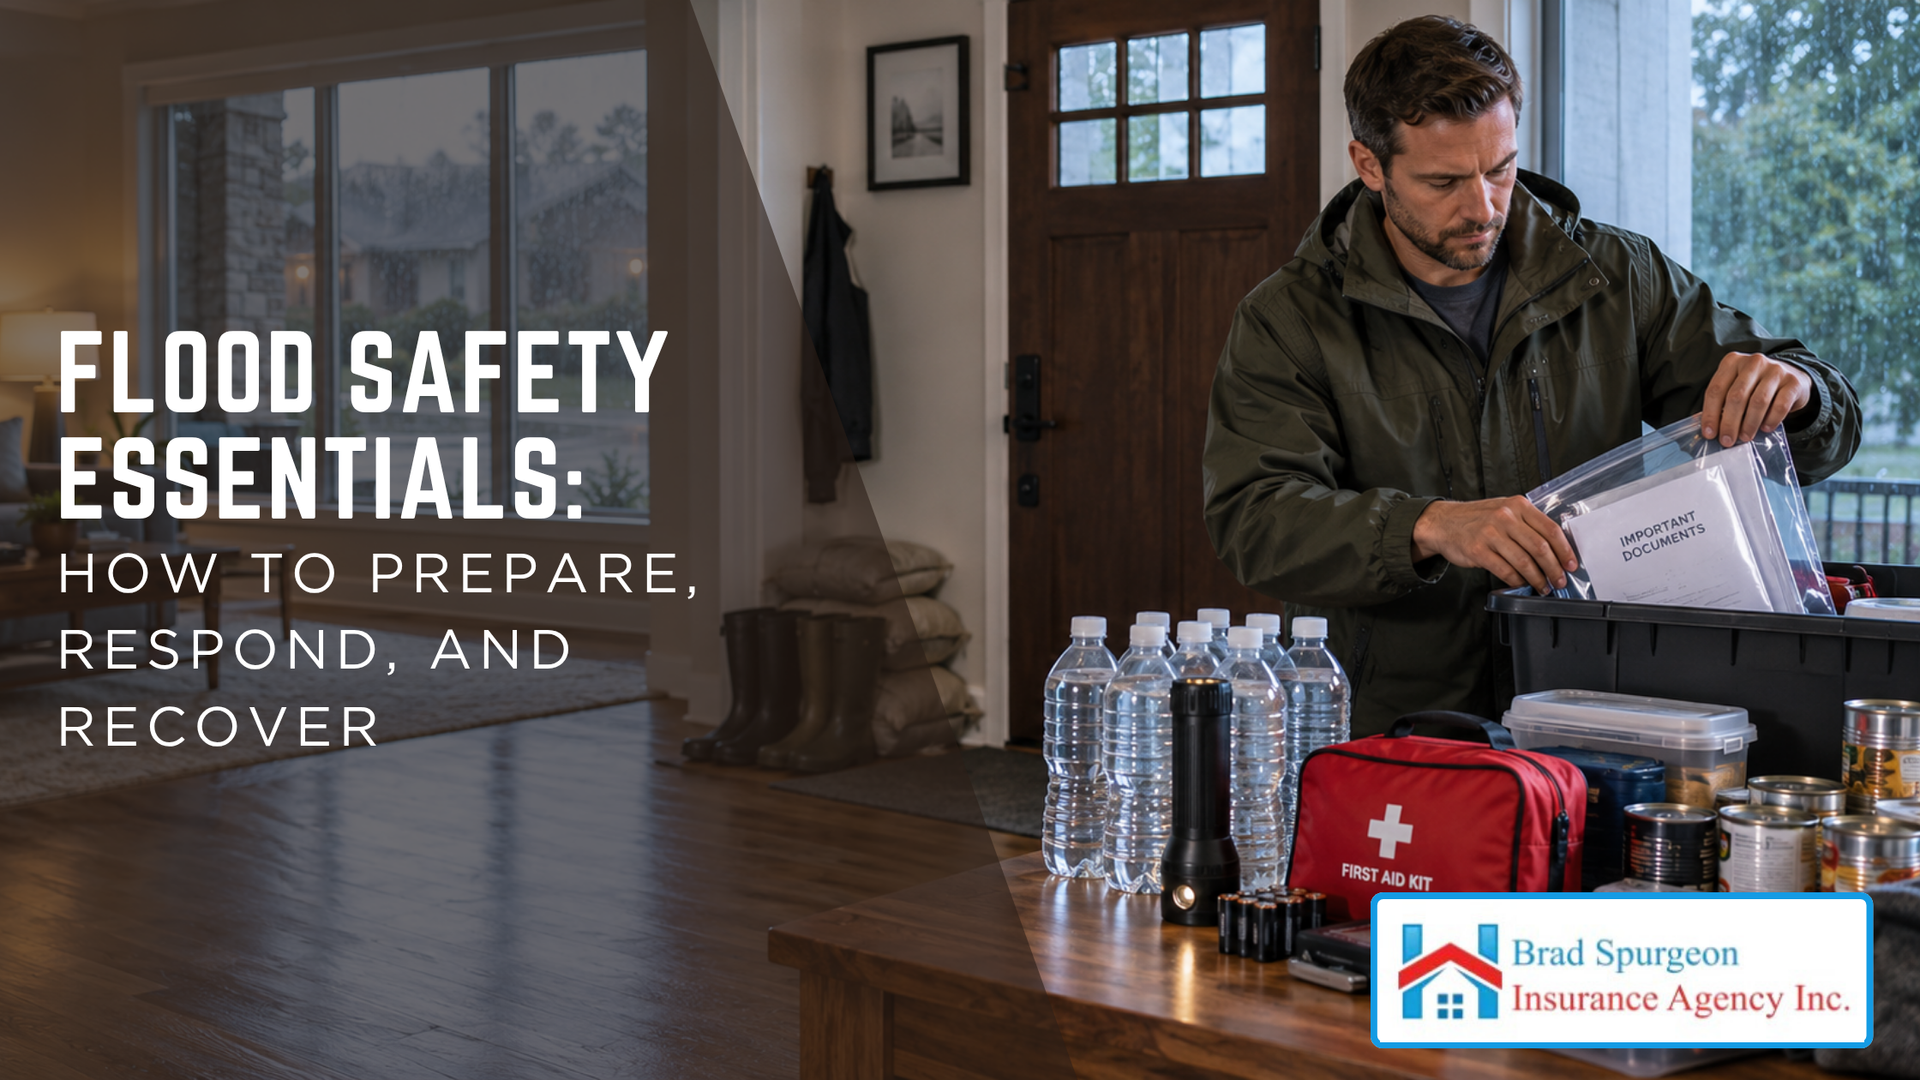
Flooding can happen quickly, leaving families with little time to protect their homes and reach safety. Heavy rainfall, overflowing waterways, tropical storms, and storm surge can create dangerous conditions, particularly in coastal communities.
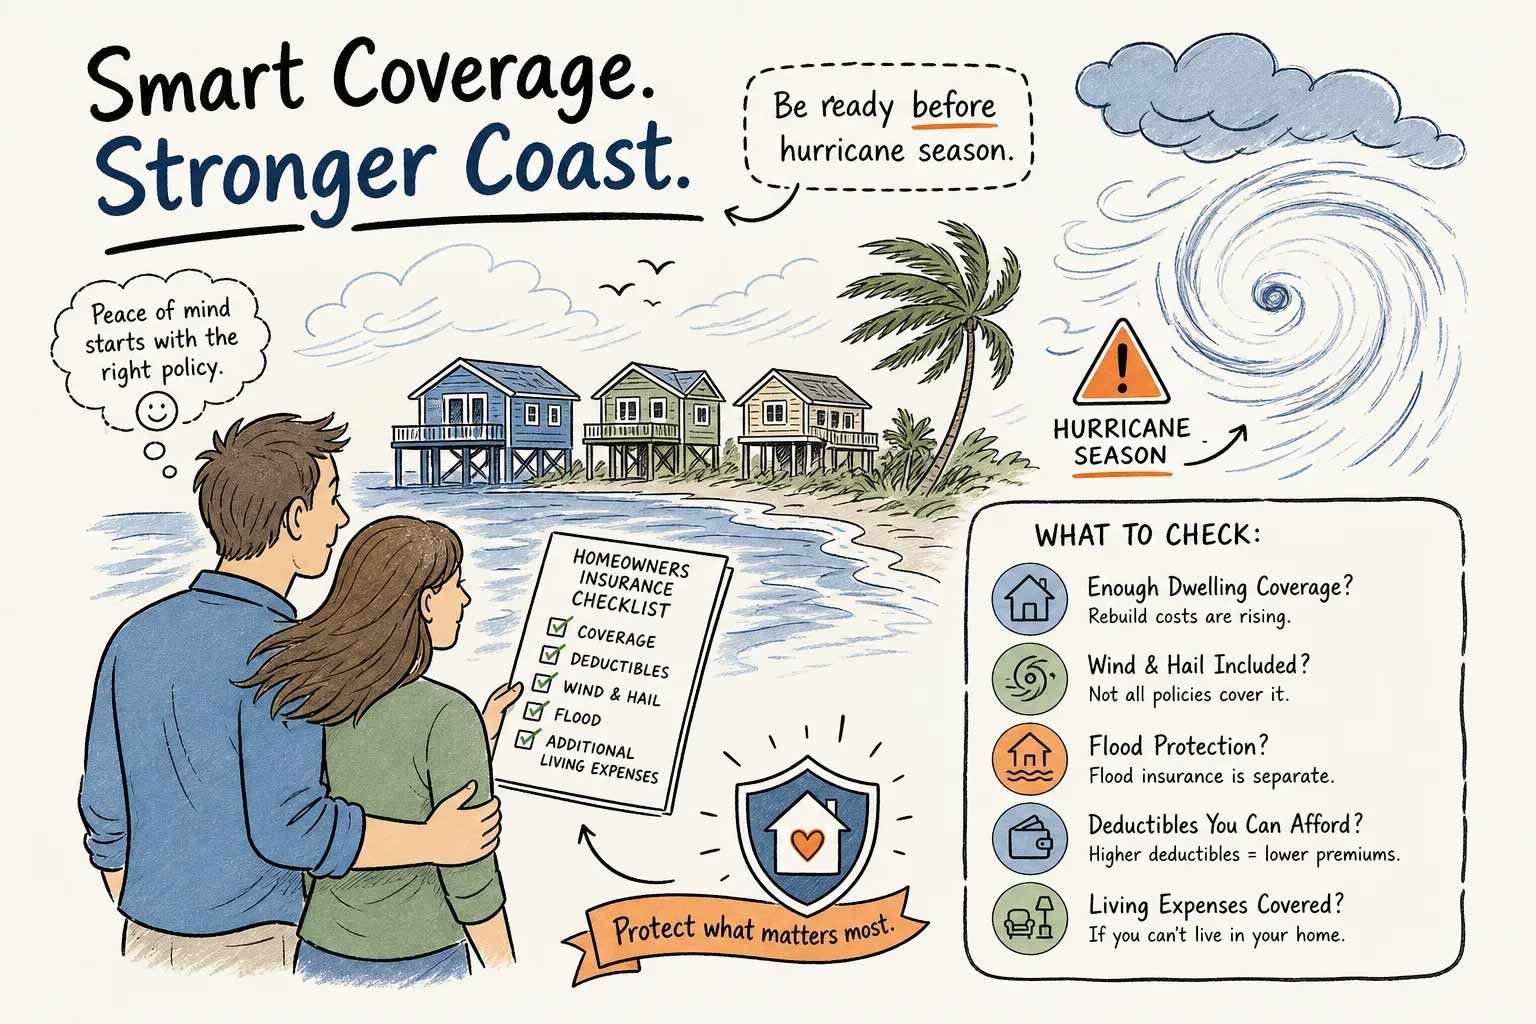
Coastal flood-preparedness infographic with couple, storm clouds, rising water, and checklist for home protection
By Brad Spurgeon • October 12, 2026
A homeowner in Texas City had been paying her homeowners insurance premiums faithfully for years. When a named storm rolled through Galveston County and tore shingles off her roof, she filed her claim confident her policy had her back. What she didn't know, and what nobody had told her, was that windstorm damage had been quietly excluded from her standard policy. The payout she expected? It wasn't coming. That conversation, the one that happens after a hurricane instead of before it, is exactly what we work to prevent at Brad Spurgeon Insurance Agency Inc. We're a family agency that has been serving Texas City and the Gulf Coast for decades, and we've seen this scenario more times than we'd like. The good news: once you understand how homeowners insurance actually works on the coast, protecting yourself completely is straightforward. This article walks you through what's covered, what's not, and the specific steps to get fully protected before hurricane season starts.
Texas Windstorm Certification banner with house, checklist form, and orange moon on blue background
By Brad Spurgeon • October 9, 2026
How to get, find or fix a Texas windstorm certificate (WPI-8 / WPI-8-E) for TWIA coverage. Updated for the 2024 building code. Local agent guide.
September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
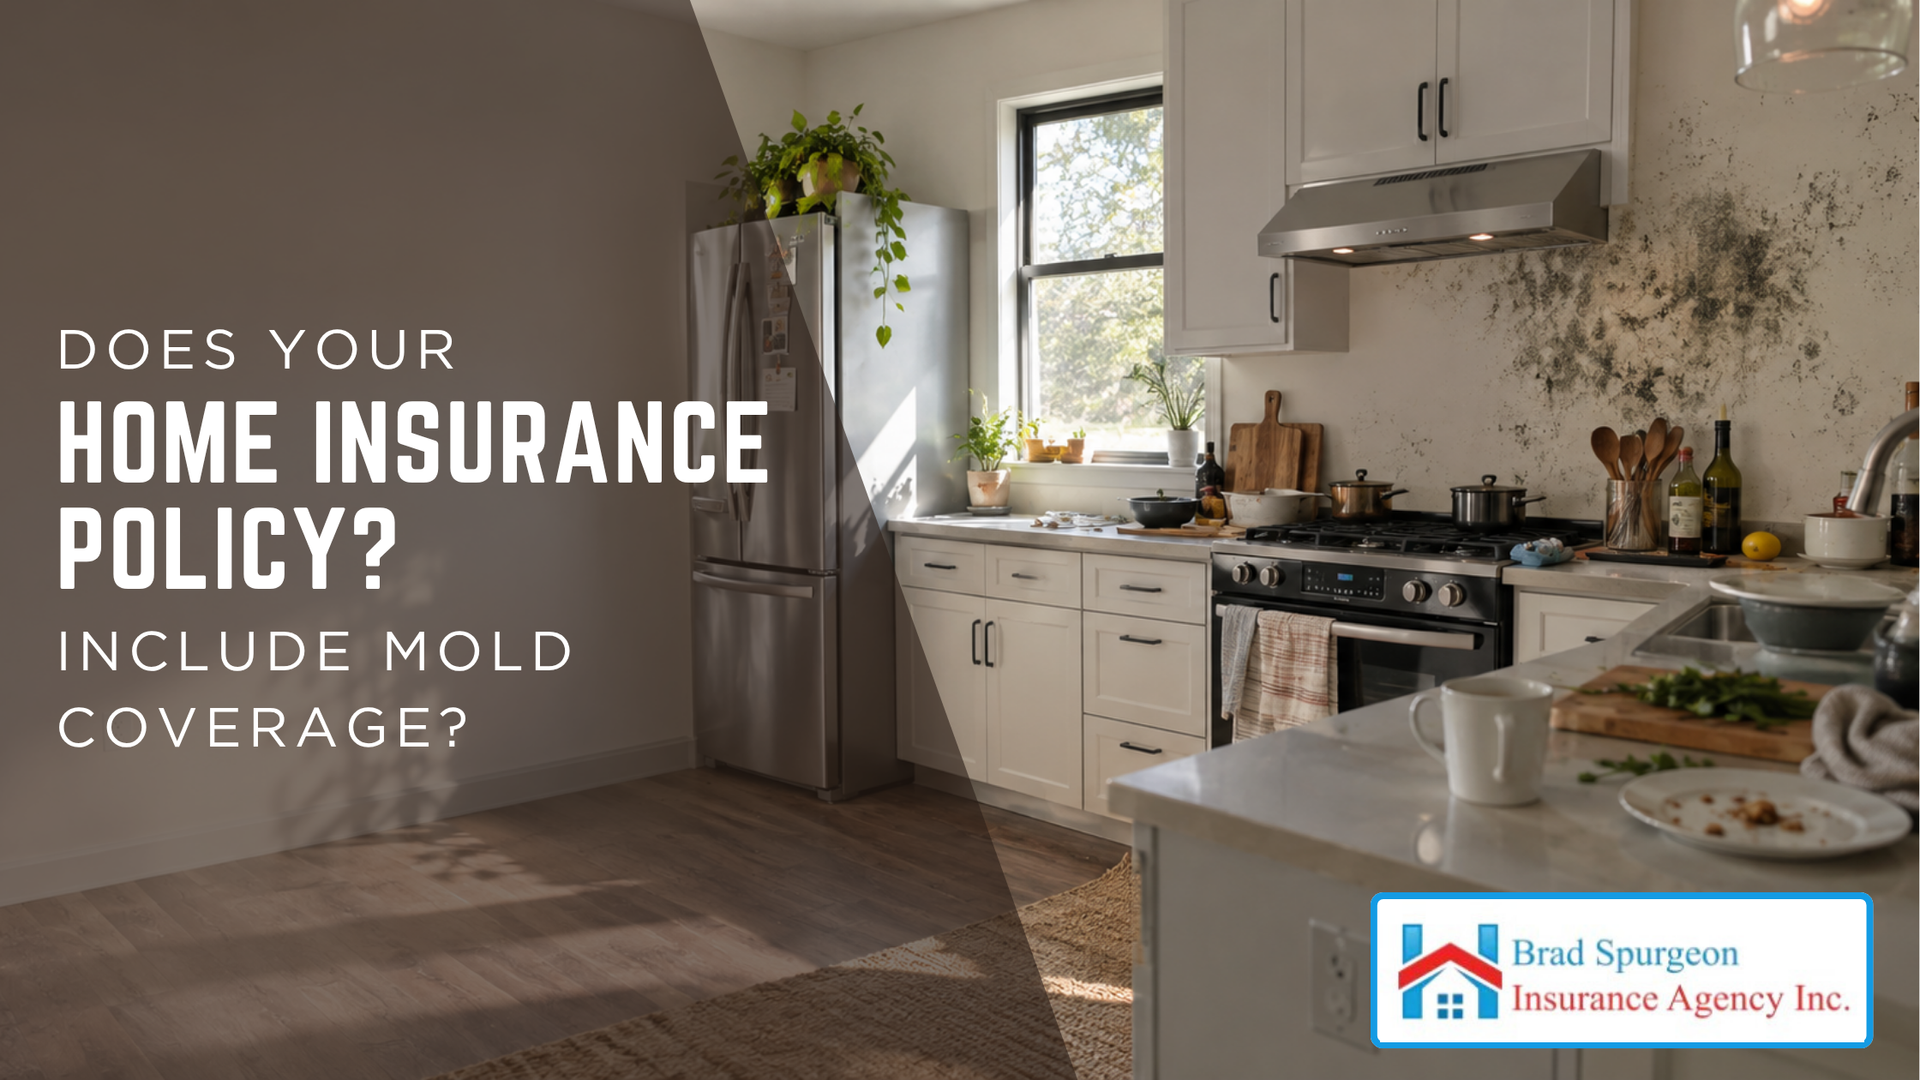
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
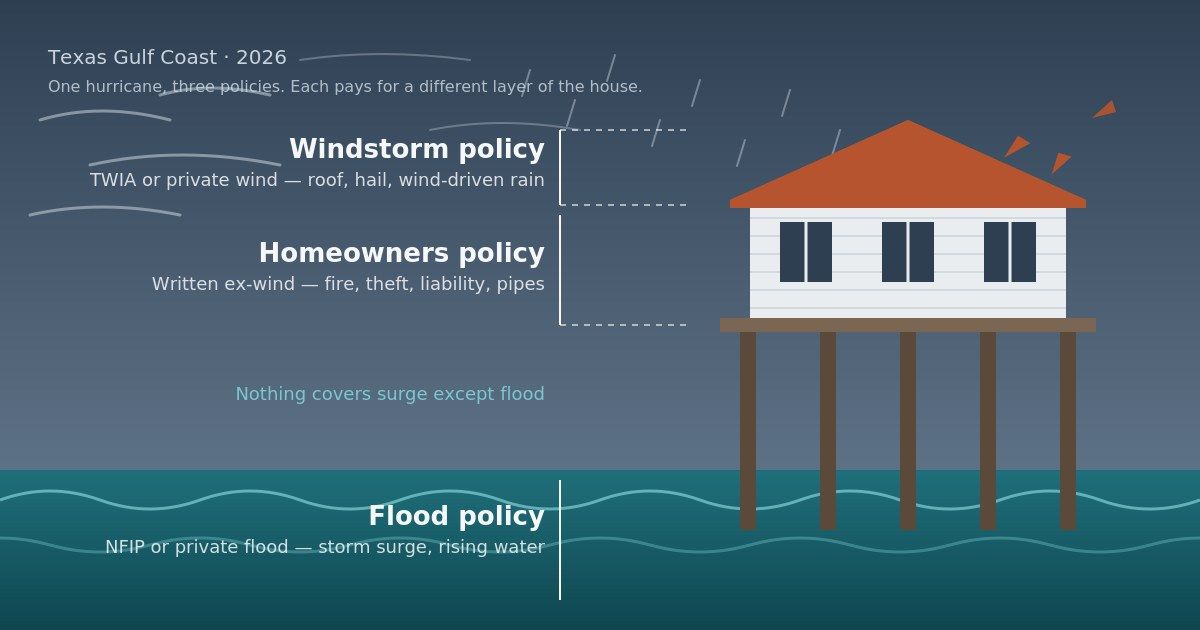
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
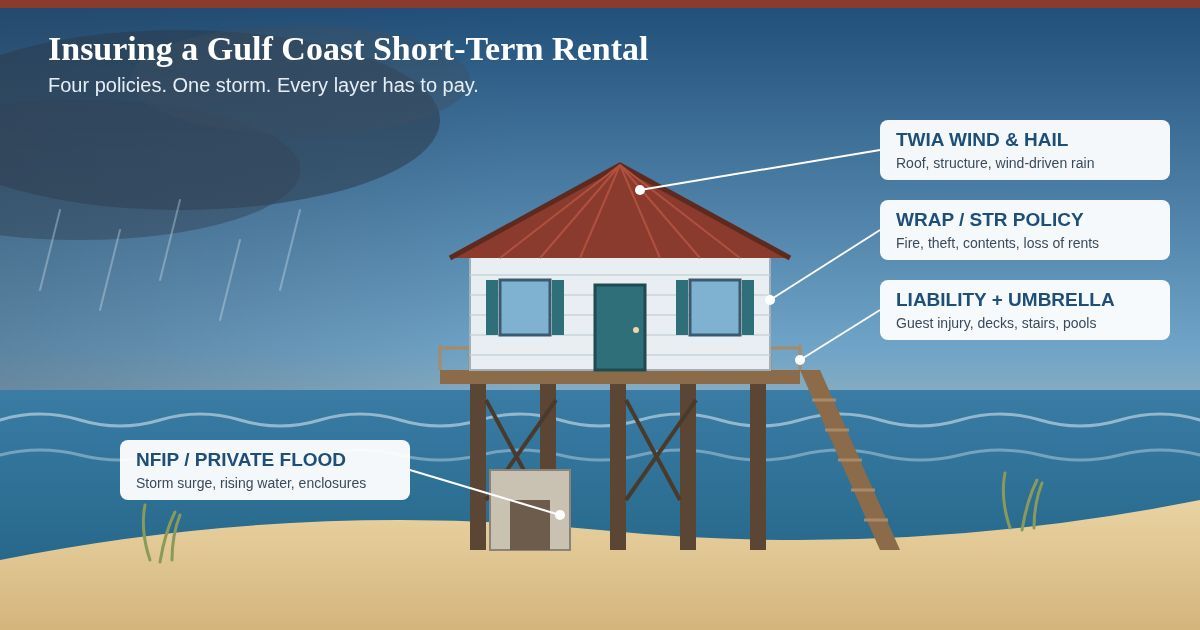
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
Show More