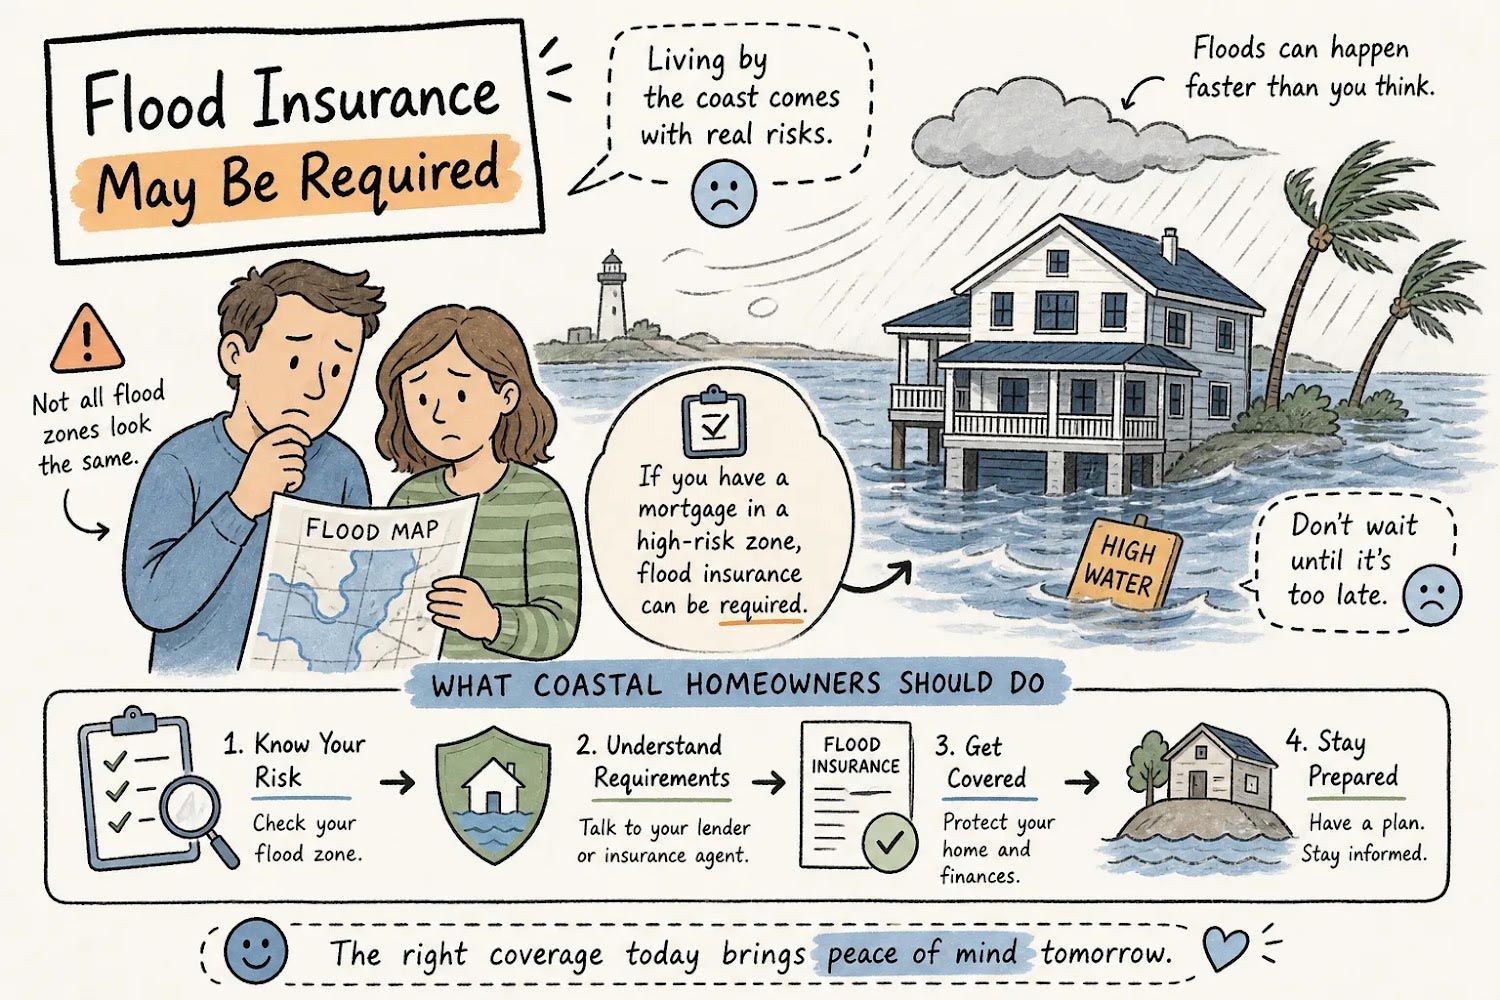
Flood insurance is required for properties located in a FEMA-designated Special Flood Hazard Area when the mortgage is federally backed or made by a federally regulated lender. Both conditions must be true at the same time. Having a federally backed loan does not trigger the requirement on its own, and being in a high-risk flood zone does not trigger it either if your financing is fully private. When both boxes are checked, coverage is mandatory for the life of the loan, and your lender enforces it. For Texas Gulf Coast homeowners, flood risk does not arrive alone. Storm surge, windstorm exposure, and hurricane activity all layer on top of the basic flood question, and the gaps between standard insurance policies can leave a claim partially or entirely uncovered. This article walks through the key situations that trigger mandatory flood coverage, how to verify your flood zone, and how to build a complete coastal insurance strategy.
Gap coverage insurance pays the difference between what you still owe on your car loan or lease and what your insurer actually pays out after a total loss. Guaranteed asset protection, the full name behind the acronym, is the product that closes that hole. If you financed or leased a vehicle in the last few years, this article is worth reading before you assume you're fully covered.
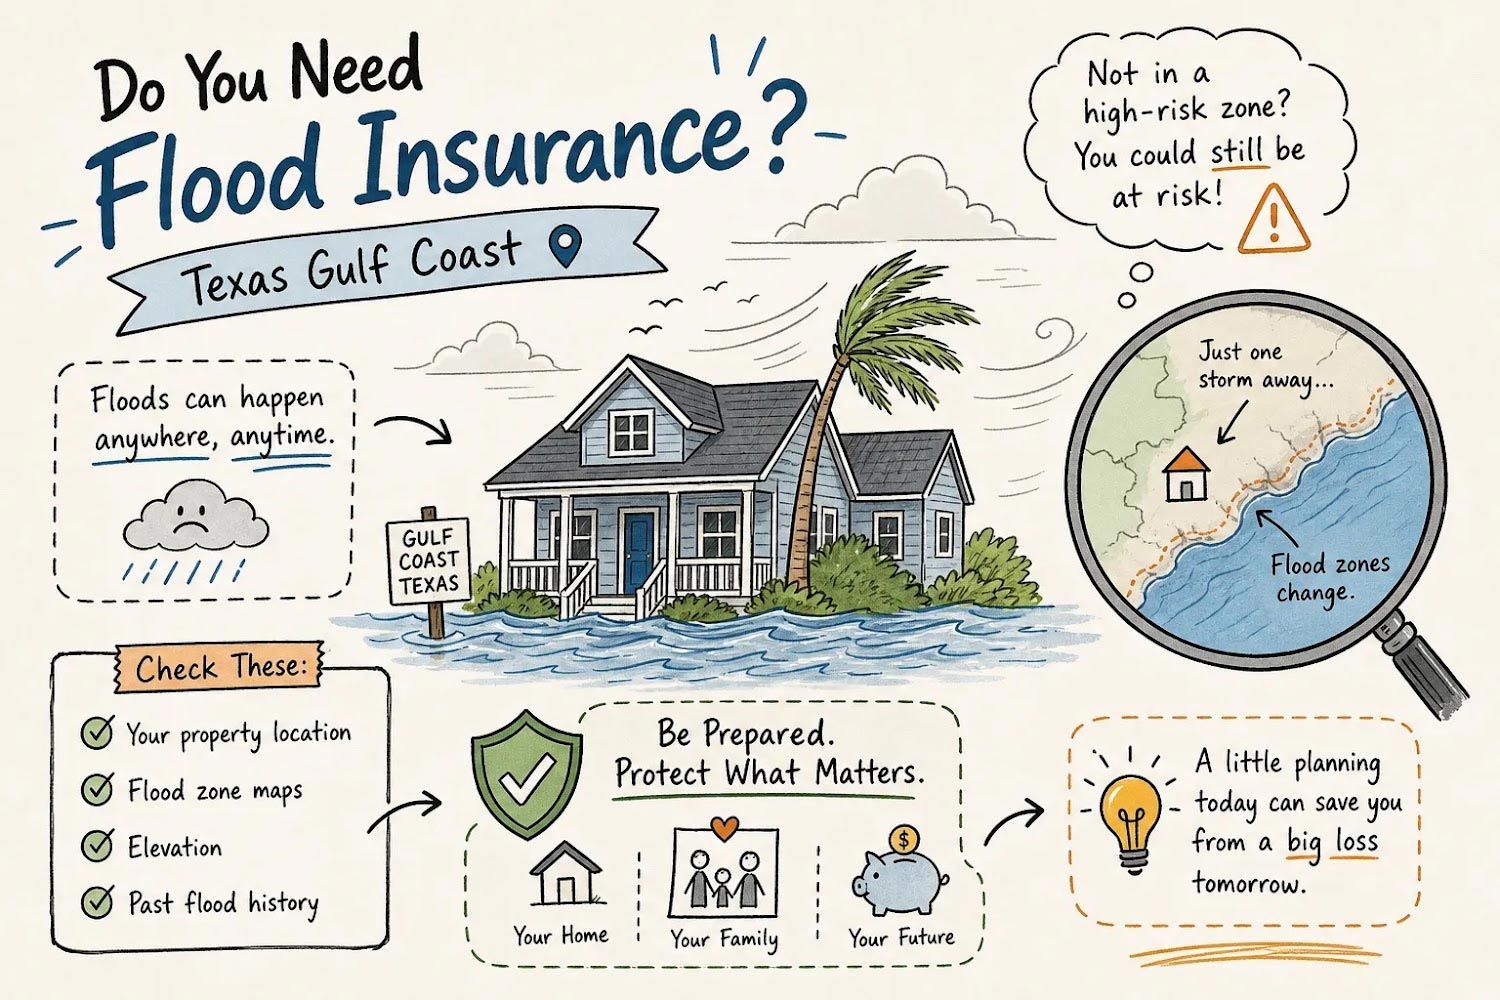
Does my property require flood insurance? If you have a federally backed mortgage and your home sits in a FEMA-designated AE or VE flood zone, flood insurance is required by federal law. That is the short answer. If you are not sure which zone your property falls into, or you have heard conflicting things from your lender, your real estate agent, and your neighbor, conflicting guidance is common along the Texas Gulf Coast due to frequent remapping and local ordinance variability. The Gulf Coast carries unique flood exposure. Roughly 23,000 to 25,000 residential properties in Galveston County alone are mapped inside FEMA Special Flood Hazard Areas, according to a residence-level FEMA-zone analysis. The question homeowners here face is rarely as simple as "do I need it?" More often, it is "does the law require it, and is what I have actually enough?" This guide walks through the exact steps to check your flood zone, understand your lender's requirements, weigh NFIP against private coverage, and figure out your next move.
Flooding can cause extensive property damage, leaving homeowners with important decisions about repairs, documentation, and insurance claims. For residents of Texas City, TX, understanding when to report flood damage is especially valuable because coastal storms and heavy rainfall can create unexpected flooding risks.
Living along the Texas Gulf Coast means preparing for powerful winds, hurricanes, and unpredictable weather conditions. For homeowners in Texas City, TX, having windstorm insurance is an important step, but understanding additional coverage options can make a meaningful difference. Windstorm insurance riders may provid
A burst pipe can release significant amounts of water into a home, damaging floors, walls, furniture, and personal belongings within minutes. For homeowners in Texas City, TX, understanding how insurance responds to unexpected plumbing problems is an important part of protecting their property. Knowing which types of w
Protecting a home along the Texas Gulf Coast requires understanding how different insurance policies respond to property damage. For homeowners in Texas City, TX, comparing homeowners insurance and windstorm insurance is especially important because coastal properties may have unique coverage requirements. Knowing how
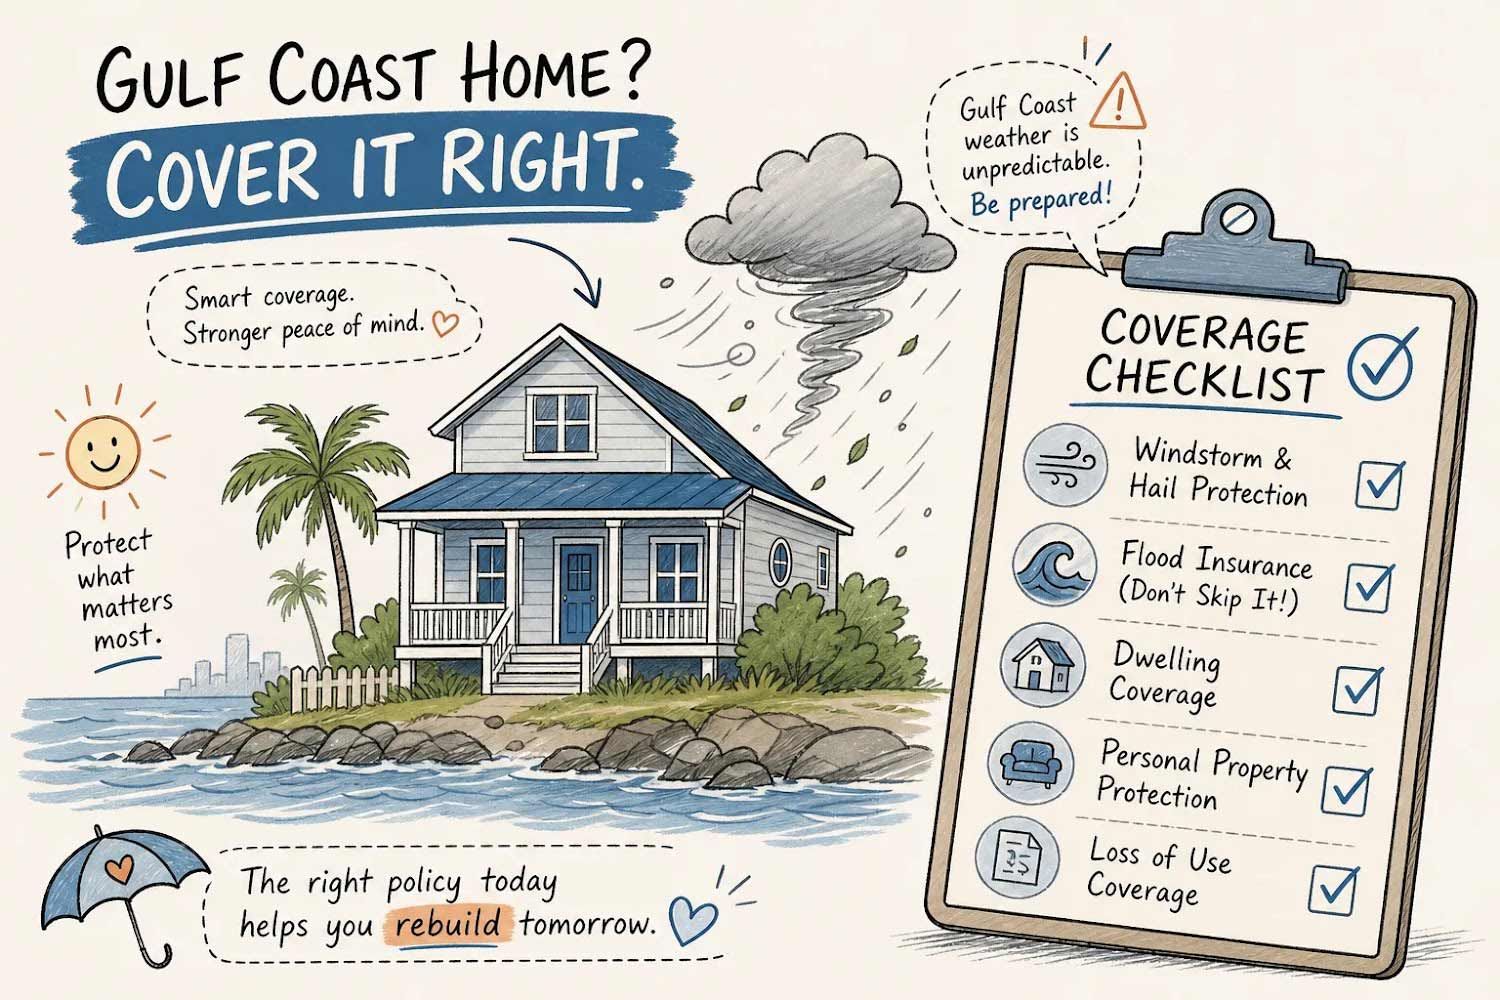
When buying on the Gulf Coast, understanding home owners insurance in Texas is essential, because a standard HO-3 policy covers fire, theft, and many everyday perils, but excludes windstorm, hail, and flood in most coastal counties. That means a single hurricane can trigger three separate claims under three separate policies, and if you only carry one policy, two of those losses come out of your own pocket. This checklist walks through what each layer covers, what it costs in 2026, and which option closes all three gaps most efficiently. Whether you're closing on a home next week or reviewing a policy you've had for years, the sequence below gives you a clear path forward.
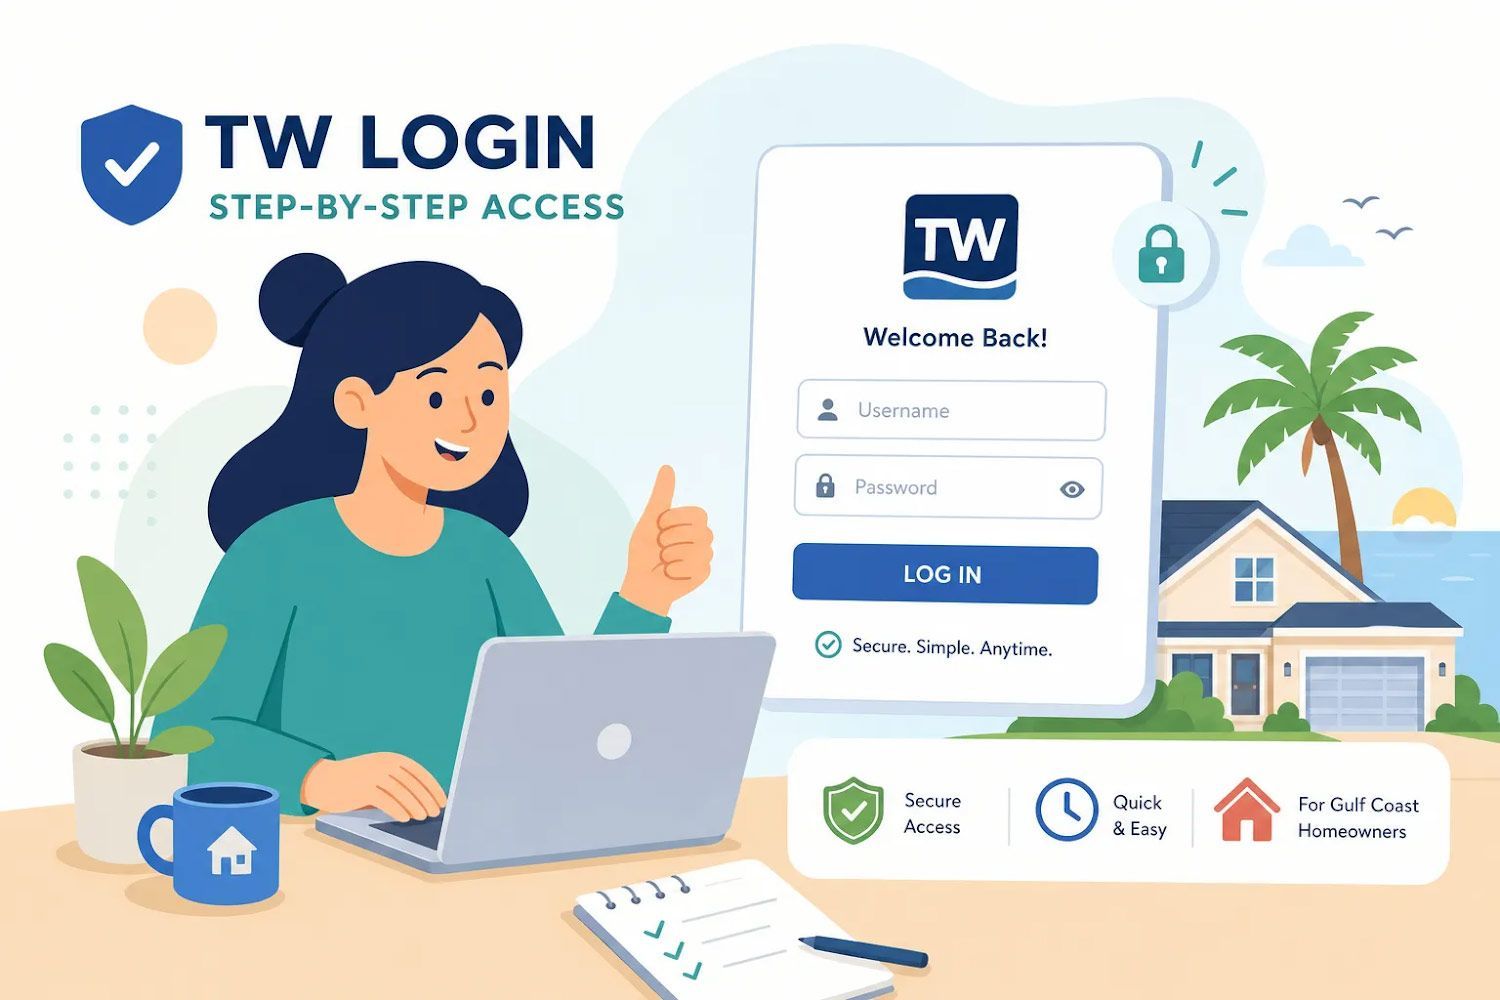
If you're searching for a TW login and you live on the Texas Gulf Coast, you're likely trying to reach one of two portals: the Texas Windstorm Insurance Association (TWIA) policyholder site or your insurance agency's online client account. TWIA uses "TW" prominently in its name and branding, and it's the essential portal for managing windstorm and coastal home coverage. Knowing which portal you need, and what to expect at the sign-in screen, makes the whole process much simpler. This guide covers the most common TW portals Gulf Coast homeowners land on, how to log into each one, how to fix errors that block access, how to recover a forgotten password, and how to verify you're on a legitimate page before you type a single credential. And if you still can't get through, Brad Spurgeon Insurance Agency Inc., a third-generation family-owned agency serving the Texas Gulf Coast since 1986, can walk you through it directly.
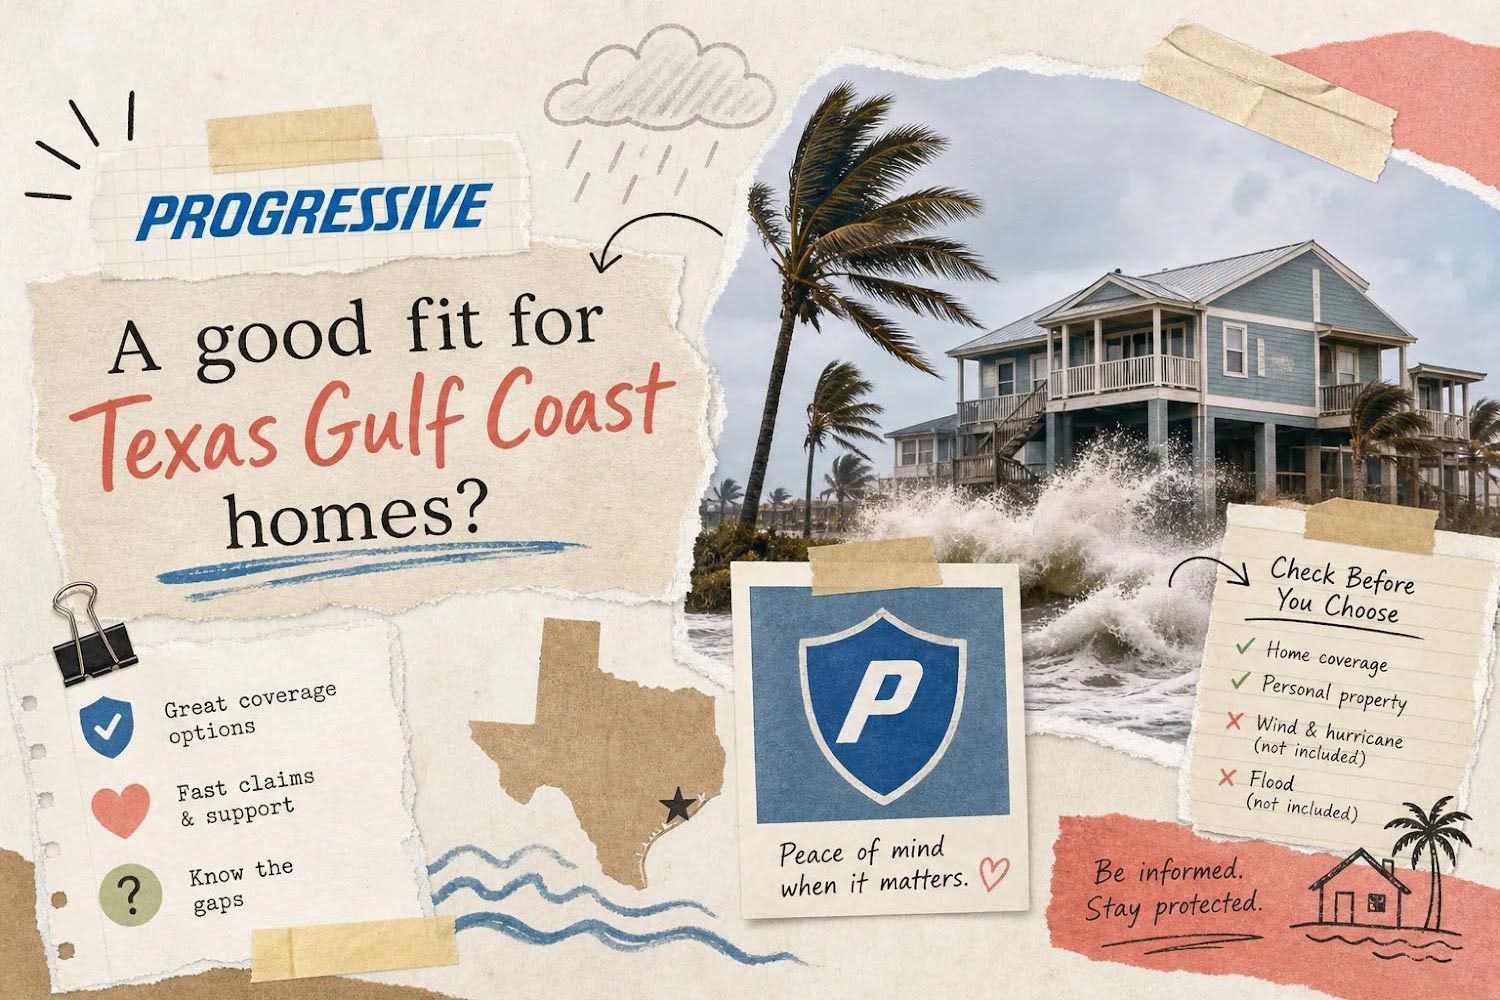
Progressive home insurance offers standard HO-3 coverage that works well for most American homeowners, but for Texas Gulf Coast properties, that base policy typically excludes the two biggest threats in the region: windstorm damage and flooding. Those aren't minor omissions for a home in Galveston County or along the Brazoria coastline. They're exactly what a hurricane or tropical storm delivers. Texas already carries some of the highest home insurance premiums in the country, and coastal ZIP codes push that figure even further above the national average. Spending that much on a policy that leaves windstorm and flood damage uncovered is a critical mistake. This article breaks down what progressive home insurance actually includes, where it falls short for coastal properties, and what a complete coverage picture looks like.