Insurance industry steady going into 2026: A positive outlook for life and nonlife

Brad Spurgeon • March 18, 2026

The global insurance industry is currently operating at a trillion-dollar scale, with the 2025 market valued at $8.33 trillion and projected to climb past $11.6 trillion by 2030. In the U.S. alone, the market stood at $2.27 trillion with forecasts pointing toward nearly $4.95 trillion by 2035.


Whether you're looking at life or nonlife sectors, the trend lines for 2026 are pointing toward stability. We aren't seeing the aggressive, vertical spikes of the last few years; instead, the industry is entering a more sustainable, steady-state phase. Here,
Brad Spurgeon Insurance Agency breaks down the factors driving stability and what to watch in the year ahead.


Starting From a Position of Stability

The current optimism among industry specialists rests on a "three-pillar" foundation of stability:


1. The Property and Casualty (P&C) Surplus

The year 2026 begins with record capital surpluses for P&C insurers, who have some of their most robust balance sheets in a decade. While 2025 was a standout year, 2026 is expected to see a slight normalization. 


Due to a very quiet hurricane season and massive rate hikes, the industry hit a combined ratio of about 94% last year, which was the best in 15 years. However, estimates show
2026 will not keep the trend going as strongly. Instead, it will more likely go back to 2024 levels, which indicates a softer market.


While 2026 likely won't be as profitable as 2025, it is still expected to underwrite profitability. For an industry that often struggles to break even on claims, lining up with a solid year like 2024 is a win.


2. A Steady Global Reinsurance Market

Reinsurance acts as the industry’s ultimate safety net, and when this segment of the market is in panic mode, all other segments suffer. This year, data from Moody’s shows the global reinsurance market has stabilized, and emergency prices have reached a plateau (still not significantly dropping, though).


This allows primary insurers to secure the coverage they need without being forced to pass massive price spikes on to their policyholders.


3. Life Insurance Optimism

The 2010-2021 period was not friendly for the life insurance industry. For over a decade, interest rates were near zero. With interest rates now stabilizing at more "normal" levels, these companies finally have access to better-paying bonds (4% to 4.2%). This shift is fueling a wave of optimism for the life and annuity sector that we haven't seen in over a decade.


Insurance Industry Goes All In on AI

As we navigate 2026, the insurance industry is moving beyond the "pilot program" phase of artificial intelligence and into full-scale integration. The real impact is now being felt in the day-to-day precision of underwriting and risk assessment. 


In the P&C sector, AI is now a functional tool helping carriers manage increasingly complex climate risks. This is especially true for "agentic AI," a 2026 breakthrough that allows systems to react to live geospatial data and make autonomous decisions. By leveraging satellite imagery and IoT sensors, carriers can now model catastrophe triage with unprecedented speed, predicting losses before claims teams even reach the ground.


More importantly, AI-driven fraud analytics are on track to provide a massive financial lift. Estimates from Deloitte suggest that by 2032, these advanced systems could save the P&C industry as much as $160 billion by identifying fraudulent patterns in real time before claims are even paid.


The End of the Hard Market

According to Deloitte’s 2026 Global Insurance Outlook, the industry is entering a period of moderating growth. Following several years of aggressive rate hikes—what specialists call a "hard market"—we are now seeing the signs of a "soft market." Global growth in the life sector is expected to settle around 2.4%, down from its 2024 peak.


This shift marks a move from "easy" to "expert" mode for insurance leaders. In a soft market, profitability isn't handed to you by rising rates; it has to be earned through operational efficiency and modern workflows. While investment income remains a solid cushion, carriers that fail to adopt AI-driven tools will find themselves struggling to compete as the pricing momentum slows.


The Soft-Market Transition and Word of Caution

We may be in a period of relative market stability and steady growth, but compared to 2025, momentum has clearly slowed. 


Luckily, investment income remains strong. That cushion allows insurers to stay profitable even when underwriting results are flat, which helps explain why most projections for 2026 remain positive.


That said, stability doesn’t eliminate risk. To stay competitive and prepared for the next market shift, insurers need to modernize their workflows, and in today’s market, this means AI adoption. AI-driven tools position carriers to respond faster, make sharper decisions, and adapt quickly when conditions change.

Progressive ad: “A good fit for Texas Gulf Coast homes?” with beach house, storm surf, and map graphic
By Brad Spurgeon • October 29, 2026
Progressive home insurance offers standard HO-3 coverage that works well for most American homeowners, but for Texas Gulf Coast properties, that base policy typically excludes the two biggest threats in the region: windstorm damage and flooding. Those aren't minor omissions for a home in Galveston County or along the Brazoria coastline. They're exactly what a hurricane or tropical storm delivers. Texas already carries some of the highest home insurance premiums in the country, and coastal ZIP codes push that figure even further above the national average. Spending that much on a policy that leaves windstorm and flood damage uncovered is a critical mistake. This article breaks down what progressive home insurance actually includes, where it falls short for coastal properties, and what a complete coverage picture looks like.
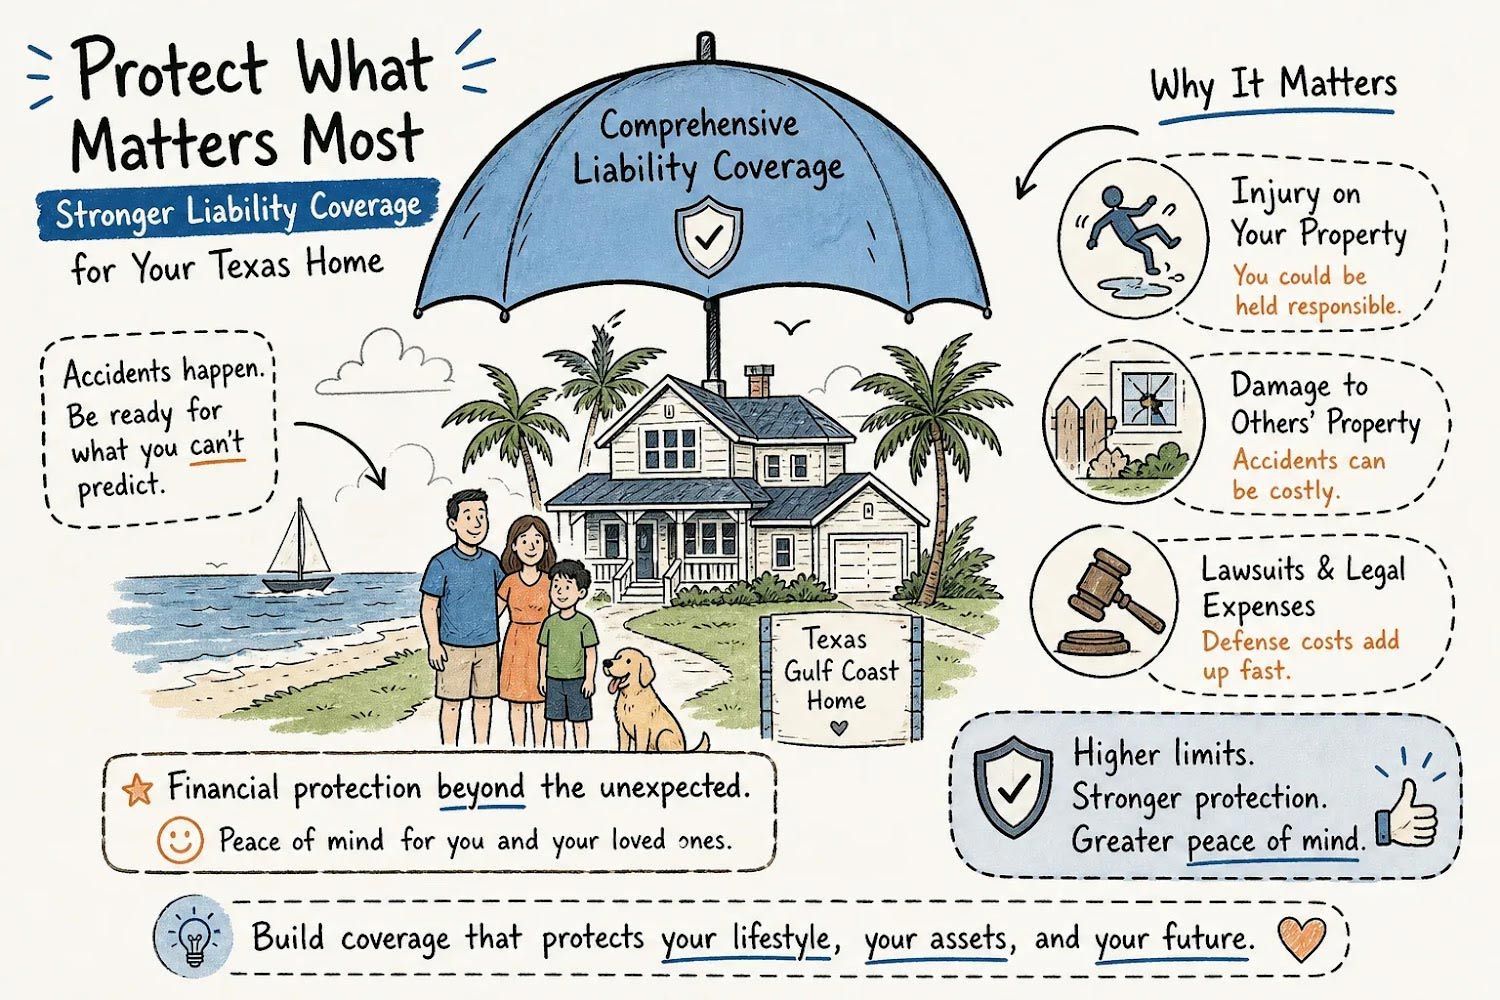
Infographic on flood insurance, showing a house, umbrella, and hurricane tips for protecting belongings and finances.
By Brad Spurgeon • October 29, 2026
Comprehensive personal liability coverage, known as Coverage E in your homeowners or renters policy, pays when someone else is injured on your property or you accidentally damage their property and you're legally responsible. It also covers your legal defense costs, attorney fees, and court judgments up to your policy limit. This guide breaks down exactly what you're covered for, what slips through the gaps, and how to build a comprehensive liability protection stack that actually holds up when a claim lands. Whether you're a first-time buyer in Texas City or a long-time Gulf Coast homeowner juggling a boat, a dog, and a rental unit, getting these limits right matters more here than almost anywhere else in the country.
Coastal home insurance ad with beach house, couple talking, and text “Ask Now, Protect Your Coastal Home”
By Brad Spurgeon • October 22, 2026
What are the most important questions to ask an insurance agent before buying coastal home insurance? Most buyers never think to ask them until after a storm. Many coastal homebuyers report spending more time negotiating kitchen countertops than understanding their insurance policy. That's a reasonable way to live, until a named storm makes landfall and the claim comes back short of what you needed. The policy was there. The coverage wasn't. Wind excluded. Flood not purchased. Deductible never translated into a real dollar amount. The policy looked fine on paper. In practice, it had gaps a storm could drive a boat through. This article gives you the questions that change that. Six categories. Each one designed to reveal whether the agent in front of you truly understands Gulf Coast exposure, or is simply filling in a form.
Handmade collage for
By Brad Spurgeon • October 22, 2026
Progressive home insurance is one of the most recognized products in the country, and that familiarity makes it easy for coastal homeowners to assume the policy covers everything it should. Many homeowners assume the standard policy handles all their risks, wind, water, and everything a Gulf Coast storm can throw at a house. It often leaves critical gaps. Gulf Coast homes face windstorm, flood, and hurricane risks that standard policies routinely exclude, and discovering those exclusions after a storm can lead to large out-of-pocket costs. This checklist walks through what a Progressive homeowners policy actually includes, where it leaves coastal buyers exposed, what it costs in Texas, and how to close the gaps before storm season arrives. We've been working with Gulf Coast homeowners from our base in Texas City since 1986.
October 19, 2026
Flooding can disrupt business operations, damage expensive equipment, and create financial losses that extend well beyond the initial cleanup. For commercial property owners, retailers, and service providers along the Texas Gulf Coast, understanding flood exposure is an important part of risk management. Knowing which
October 19, 2026
A small fire can become a serious emergency in moments. Whether it starts in the kitchen, garage, or another part of the house, knowing how to respond can help protect your family and property.
October 15, 2026
Strong winds from thunderstorms, hurricanes, and tropical storms can cause significant property damage. Missing roof shingles, broken windows, damaged siding, and fallen trees are just a few problems homeowners may discover after severe weather.
October 15, 2026
Flooding can happen quickly, leaving families with little time to protect their homes and reach safety. Heavy rainfall, overflowing waterways, tropical storms, and storm surge can create dangerous conditions, particularly in coastal communities.
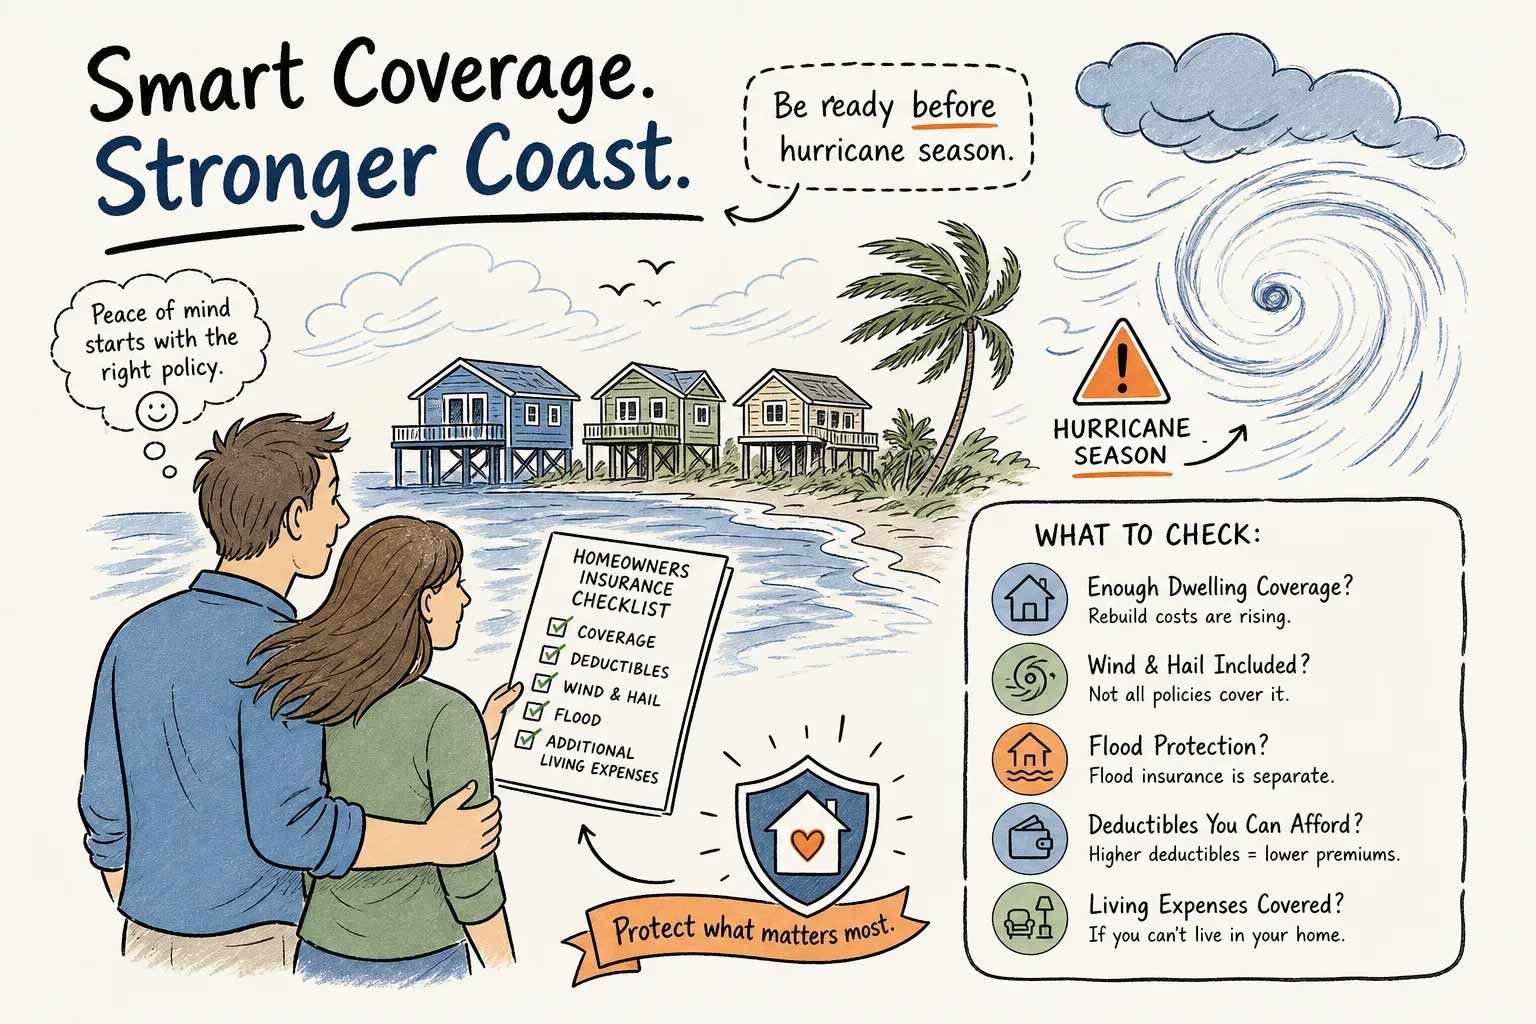
Coastal flood-preparedness infographic with couple, storm clouds, rising water, and checklist for home protection
By Brad Spurgeon • October 12, 2026
A homeowner in Texas City had been paying her homeowners insurance premiums faithfully for years. When a named storm rolled through Galveston County and tore shingles off her roof, she filed her claim confident her policy had her back. What she didn't know, and what nobody had told her, was that windstorm damage had been quietly excluded from her standard policy. The payout she expected? It wasn't coming. That conversation, the one that happens after a hurricane instead of before it, is exactly what we work to prevent at Brad Spurgeon Insurance Agency Inc. We're a family agency that has been serving Texas City and the Gulf Coast for decades, and we've seen this scenario more times than we'd like. The good news: once you understand how homeowners insurance actually works on the coast, protecting yourself completely is straightforward. This article walks you through what's covered, what's not, and the specific steps to get fully protected before hurricane season starts.
Texas Windstorm Certification banner with house, checklist form, and orange moon on blue background
By Brad Spurgeon • October 9, 2026
How to get, find or fix a Texas windstorm certificate (WPI-8 / WPI-8-E) for TWIA coverage. Updated for the 2024 building code. Local agent guide.
Show More