Insurance Tips for Vacant Homes

January 4, 2021
A modern, well-lit living room with a beige sofa, white kitchen, and a fireplace


A homeowner must maintain insurance under an average mortgage, where the homeowner is liable for damages incurred even when the home is vacant. However, the right insurance coverage can pay for incidents like robbery or vandalism for vacant homes. Here are the things that you must note if you want to maximize your vacant home’s insurance.


What is Being “Vacant”?

As defined by the court, a home is “vacant” if it does not have enough furniture for a resident living there. If there are no kitchen appliances, table, chairs, and at least one bed for sleeping, your insurer might have to apply for vacancy exclusions to the loss. In this case, you might need to spend thousands of dollars on attorney fees to contest your insurer’s decision.


How Long Does Vacant Home Coverage Last?

Don’t wait for your vacant home to get vandalized before checking your insurance policy, as most homeowner’s insurance policies on vacant homes only last for 30 to 60 days. If you moved out more than a month ago, your house might have been already uninsured even if you have paid the premium for your policy, where you have to deal with these problems:


  • Insurance policies will not cover vandalism and glass breakage.
  • Insurers will not continue to insure a vacant home, nor are they willing to accept insurance for houses with canceled or non renewed policies due to vacancy reasons. Otherwise, the premium cost will be four to five times higher than before.

Why Vacant Home Insurance Matters

If you had no way to prevent your home from being vacant, you need to obtain an insurance policy for your unoccupied, higher risk, empty house. However, only two insurer types are willing to insure this circumstance: specialty companies and surplus line carriers.


If your home does not have insurance during its vacancy, you will be liable to fix the damages in the event of vandalism, which can imperil the short sale. As the short sale does not benefit the insurer, they can foreclose any time they want.


Conclusion

Having vacant home insurance can avoid anything that could impose risks on the short sale. It is better to deal with sales the fall short than a foreclosure as it has a lesser effect on your credit reports.


At Brad Spurgeon Insurance Agency Inc., we put our clients first by offering them policies that they can afford. Having insurance is a necessity nowadays, and we're here to help you out. Learn more about our products and services by calling our agency at (409) 945-4746. You can also request a free quote by CLICKING HERE.

September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
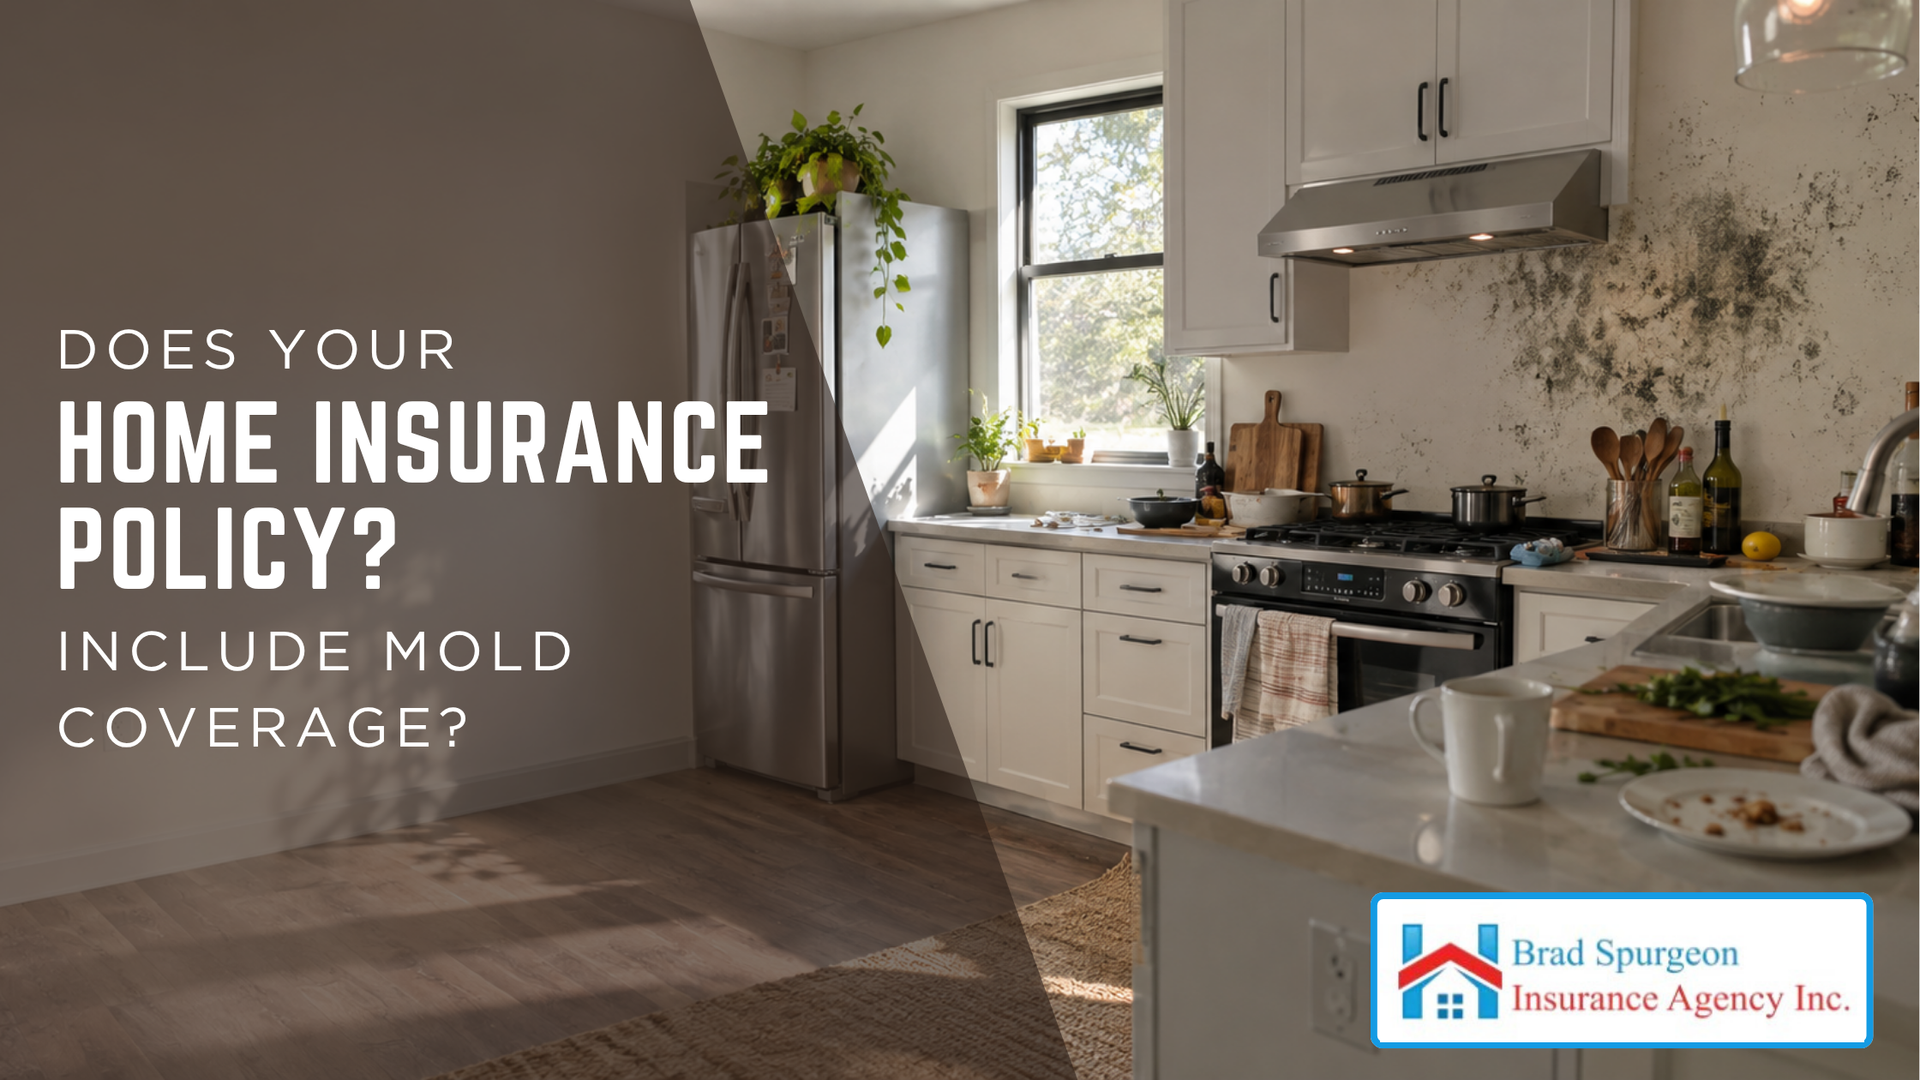
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
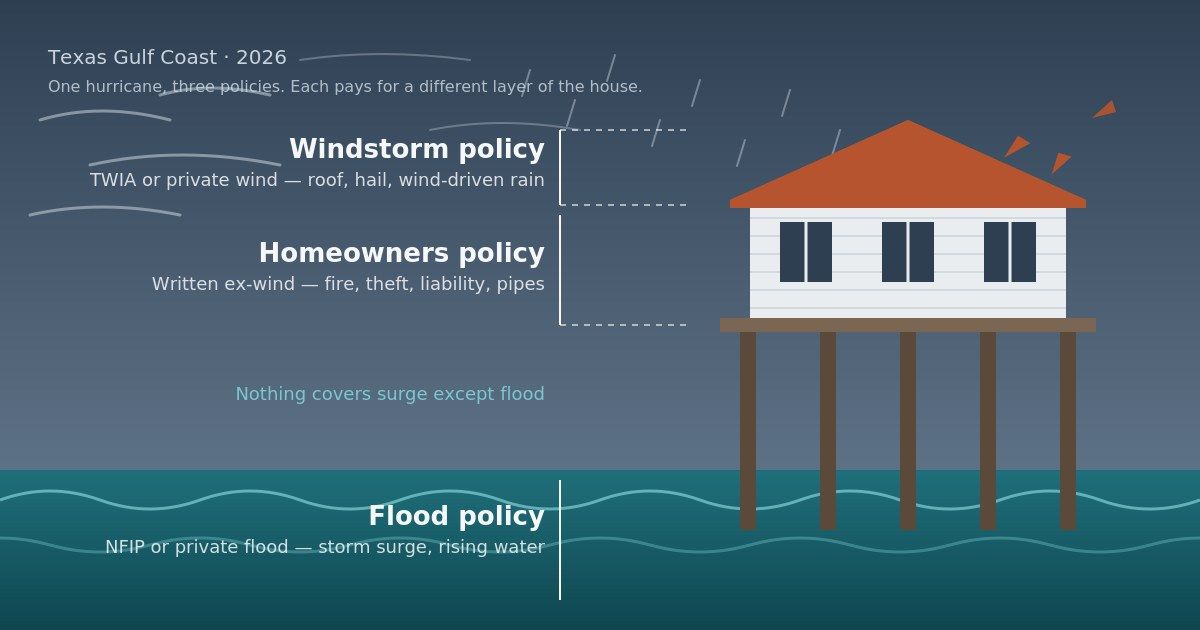
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
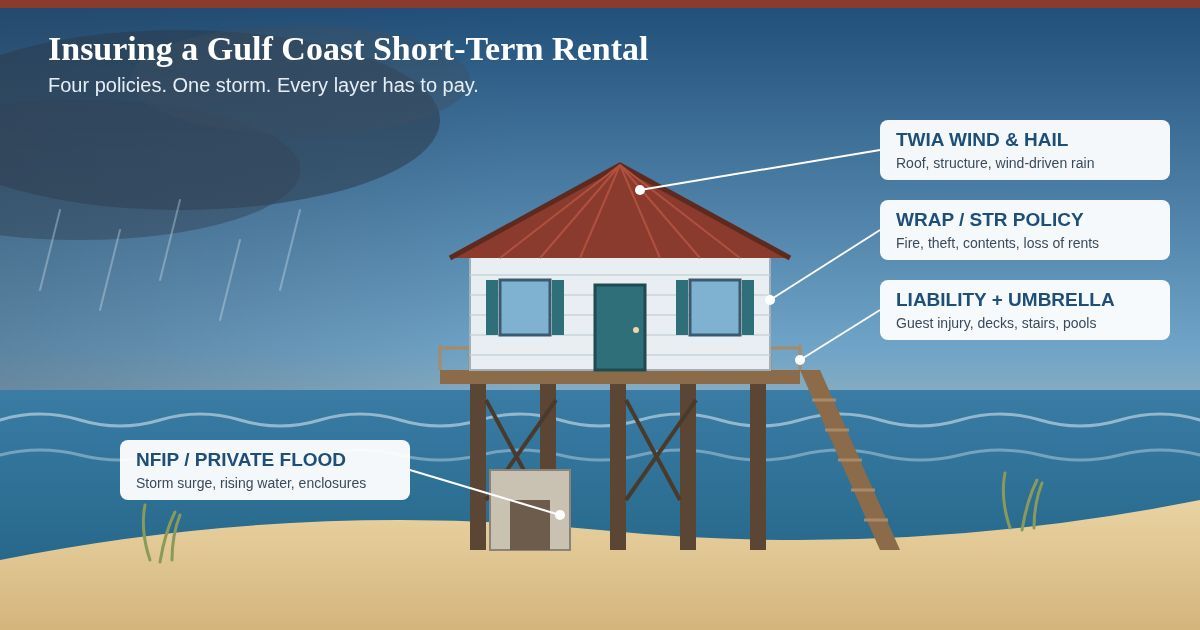
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
August 25, 2026
Learn why TWIA requires WPI-8 certification, which Texas coastal homes need it, key exceptions, and what to do if your certificate is missing.
A smiling parent sits on a couch and lifts a happy young child
August 19, 2026
Kids explore everything, and that curiosity is part of what makes childhood fun — but it also means everyday spaces in your home can hide risks you might not think twice about as an adult. A few thoughtful changes around the house can prevent the kinds of accidents that send families to the emergency room every year.
A view of two suburban houses
August 17, 2026
It's a question we hear often in Texas City, especially once a tropical system starts showing up in the forecast: can I still get flood insurance now, or is it too late? The honest answer is that it depends on your policy type and timing, and understanding how flood insurance waiting periods work can save you from a co
An American Red Cross emergency kit with supplies like water, a flashlight, goggles, and a poncho for flood survival.
August 10, 2026
Living near the Texas Gulf Coast means flooding isn't a rare or distant threat — it's a real possibility every hurricane season, and sometimes even after a heavy afternoon thunderstorm. Whether you're right along the water or a few miles inland, knowing how to prepare, evacuate, and recover safely can make all the diff
Show More