4 Insurance Mistakes That Homeowners Need To Avoid

August 8, 2017
Three people in business attire sit together in a meeting

​

As we enter the beginning of hurricane season this year it’s time to consider the ramifications of weather conditions and how they can be a major cause of home damage in the near future.


​All hurricanes are sure to result in stories by homeowners who discovered that their coverage do not meet their expectations and that they need to shell out huge amounts of money for repair. This is why you need to review your insurance policy and read the fine print carefully.


What You Want to Avoid

When reviewing your homeowner’s insurance policy, make sure not to make these mistakes and make sure you correct them as you go.


Mistake #1: Not Enough Insurance for Rebuilding Your House

Not having enough insurance to include reconstruction expenses if your house gets wrecked is a big mistake according to experts. Studies claim that over 50 percent of homes in the U.S. are underinsured.This is due to homeowners opting for insurance that would cover their mortgage.


Covering your mortgage is fine, but it doesn’t cover the whole value of the house nor does it consider its appreciated value. There are also those homeowners who get insurance worth their homes current value. However, this does not always equate to the cost that you need to rebuild your house.


How to Avoid It?

When choosing an insurance policy, make sure to include future events such as major damages in the house and reconstruction as well as the labors and materials needed for it. You may also opt for an extended replacement coverage where the company pays you more than 100 percent of the policy value for home reconstruction.


Mistake #2: Not Making Sure that You Have Flood Insurance

This is not a standard coverage that is part of your policy. Homeowners who live in coastal areas like most of our clients or those that are near lakes and other bodies of water should definitely get this. However, even those who do not live near the water may also opt for this coverage as they can also suffer from severe flooding during storms.


Flood coverage is easy to get and is accepted by most insurance companies today. The price depends on your area and its risks of flooding.


How to Avoid it?

Ask your agent if they can give you flood insurance along with your current policy or give our agency a call anytime.


Mistake #3: Assuming That You Have a Flat Rate Deductible

You may think that you only need to shell out a few bucks along with your insurance coverage to repair your home due to damages caused by natural disasters. This is a mistake that most homeowners make.


When it comes to natural disasters, your policy’s deductible usually turns out to be a fraction of your whole coverage. This means that it can range from 1 to 15 percent of the total value of your policy depending on the incident.


For example, if you have a policy with a $200,000 coverage and your house gets damaged because of an earthquake, you could be slapped with a $20,000 deductible upon filing your claim.


How to Avoid It?

Make sure to ask your insurance agent if their company has different deductibles. If that’s the case, ask for a policy with a flat-rate deductible and don’t settle for anything else.


Mistake #4: Not having Sewer Back-Up or Mold Coverage

Most home insurance policies do not have this kind of coverage, or if they do, they have claim limitations.


How to Avoid It?

Ask your insurance company about these extra coverages as it is not very expensive and is worth having. If your house is in a humid place, chances are you need mold protection more than ever. When it comes to sewer back-up, you can never go wrong in trying to prevent sewer spillage in your homes during heavy rains.


At the Brad Spurgeon Insurance Agency, we take pride in making sure our clients are well protected at prices they can afford. To learn more about how we can help you please contact our agency at (409) 945-4746 or Click Here to request a free quote.

September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
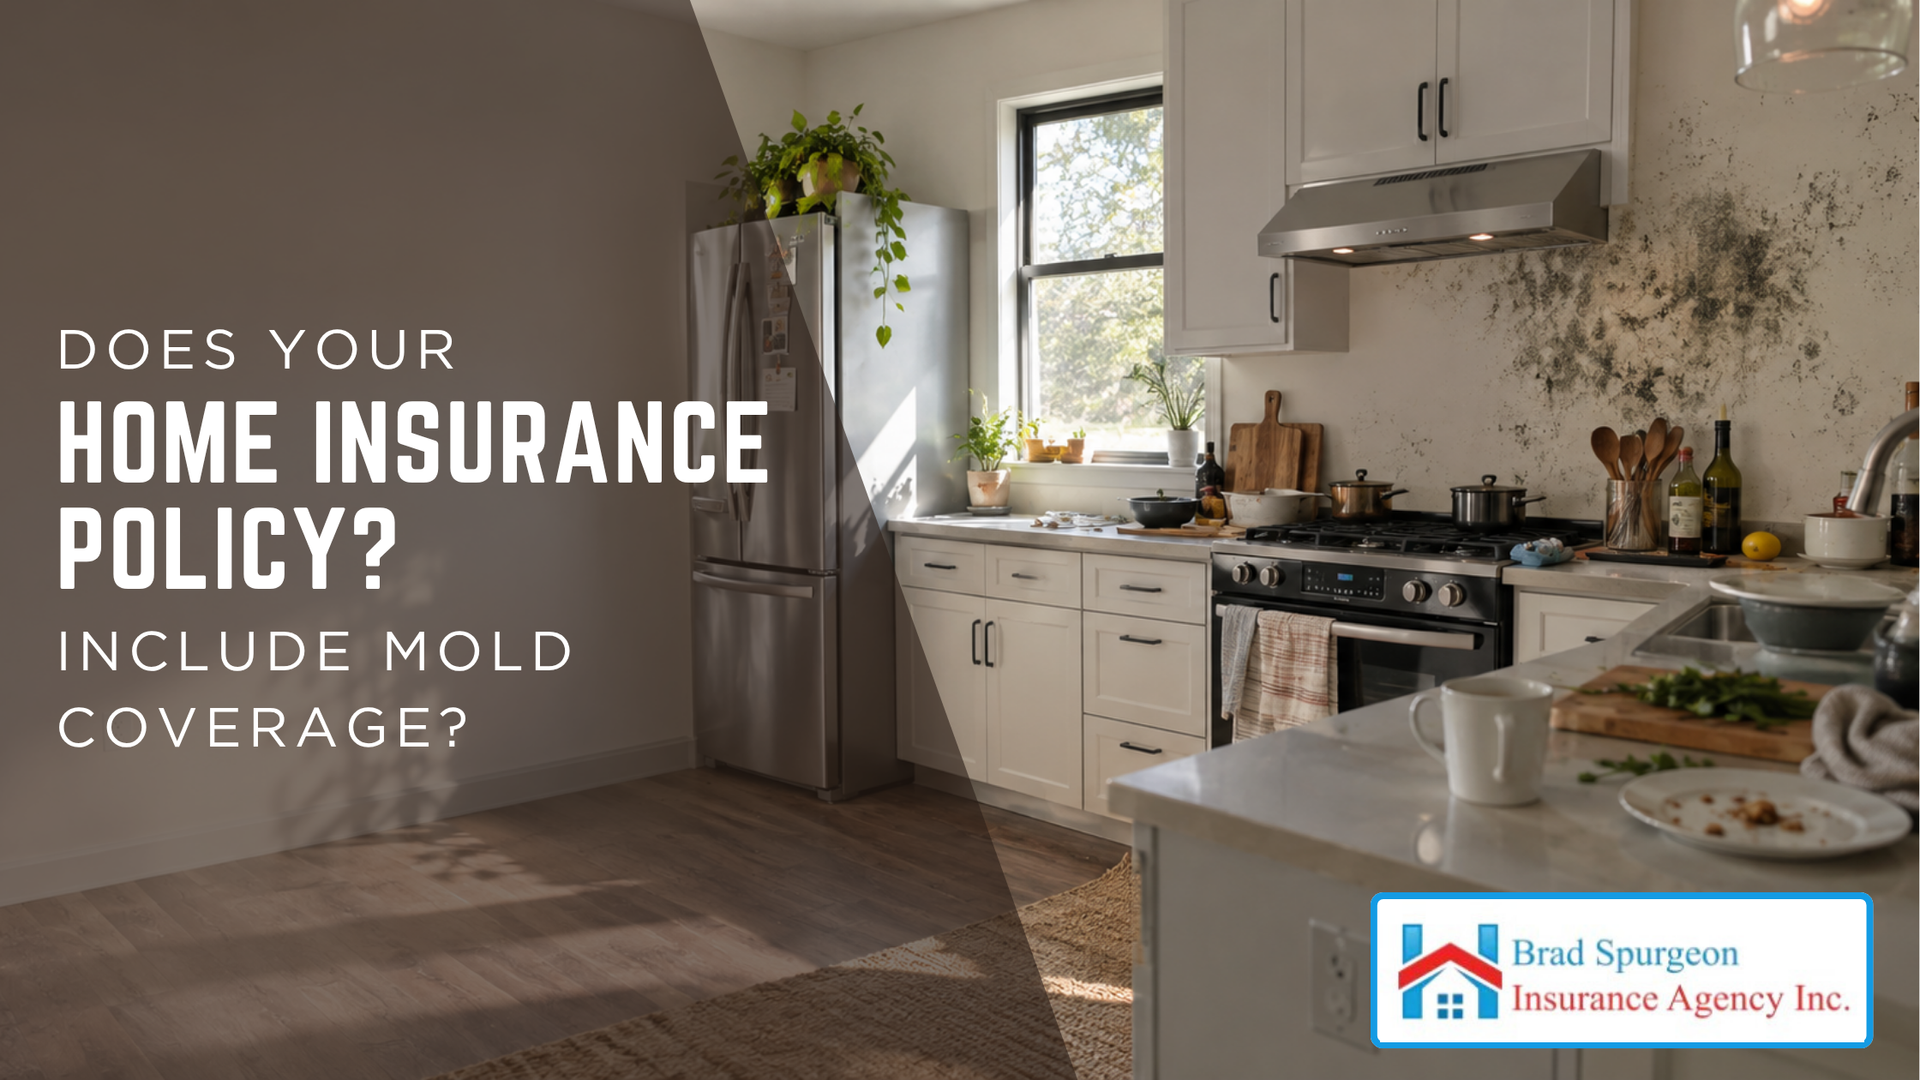
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
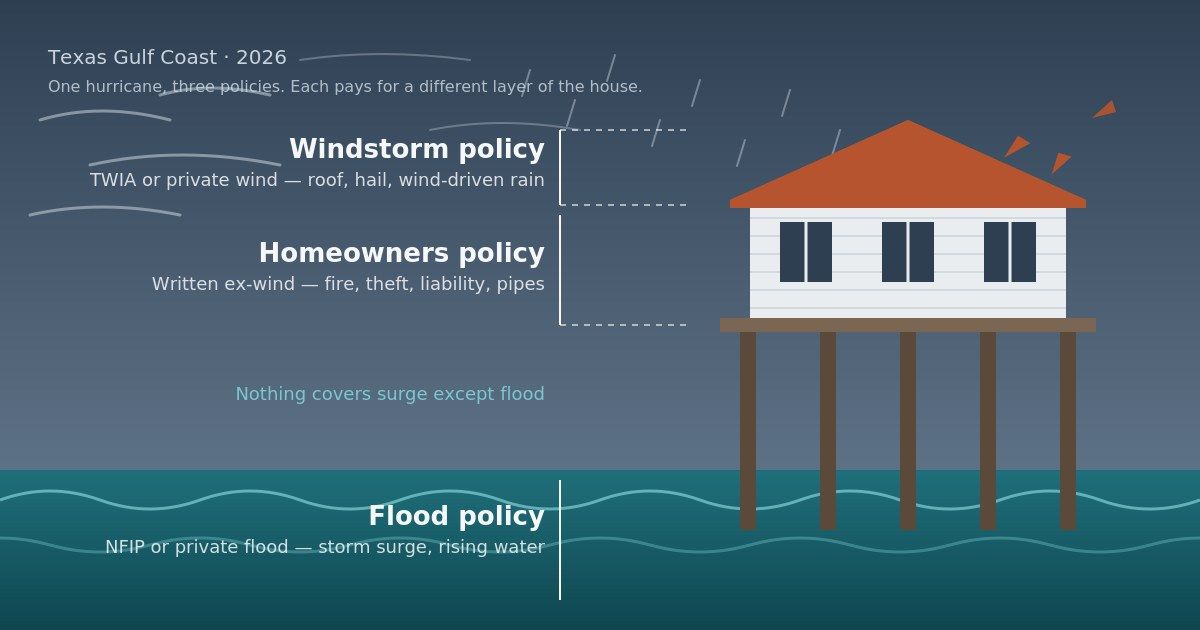
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
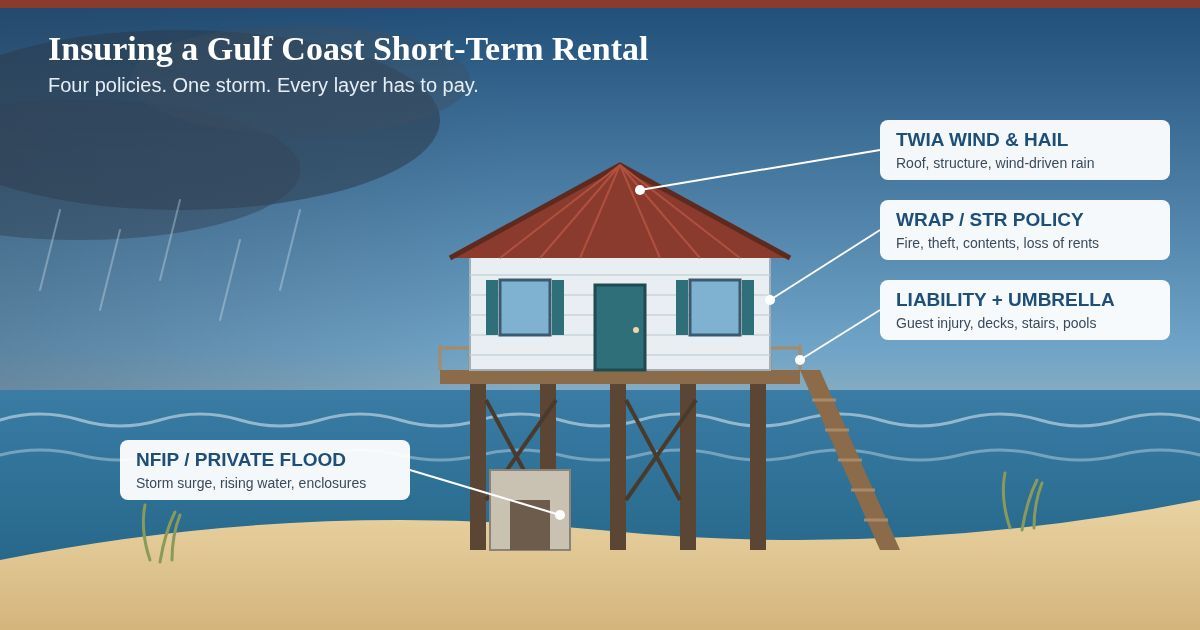
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
August 25, 2026
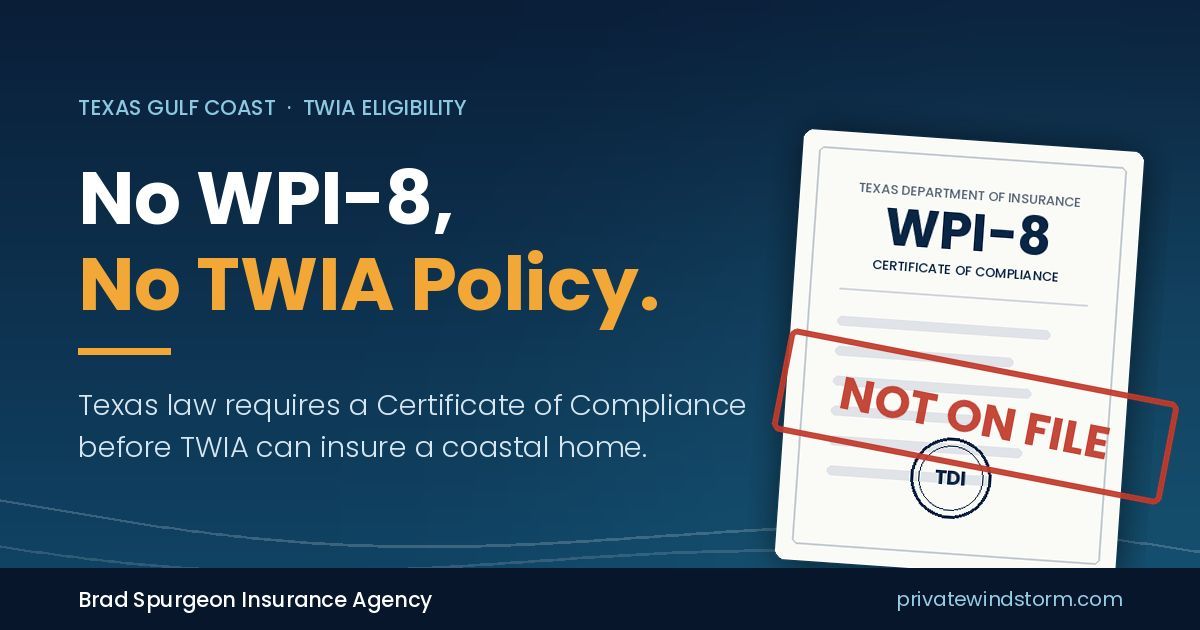
Learn why TWIA requires WPI-8 certification, which Texas coastal homes need it, key exceptions, and what to do if your certificate is missing.
A smiling parent sits on a couch and lifts a happy young child
August 19, 2026
Kids explore everything, and that curiosity is part of what makes childhood fun — but it also means everyday spaces in your home can hide risks you might not think twice about as an adult. A few thoughtful changes around the house can prevent the kinds of accidents that send families to the emergency room every year.
A view of two suburban houses
August 17, 2026
It's a question we hear often in Texas City, especially once a tropical system starts showing up in the forecast: can I still get flood insurance now, or is it too late? The honest answer is that it depends on your policy type and timing, and understanding how flood insurance waiting periods work can save you from a co
An American Red Cross emergency kit with supplies like water, a flashlight, goggles, and a poncho for flood survival.
August 10, 2026
Living near the Texas Gulf Coast means flooding isn't a rare or distant threat — it's a real possibility every hurricane season, and sometimes even after a heavy afternoon thunderstorm. Whether you're right along the water or a few miles inland, knowing how to prepare, evacuate, and recover safely can make all the diff
Show More