How Flood Insurance And Government Aid Work Together After A Disaster

October 13, 2025
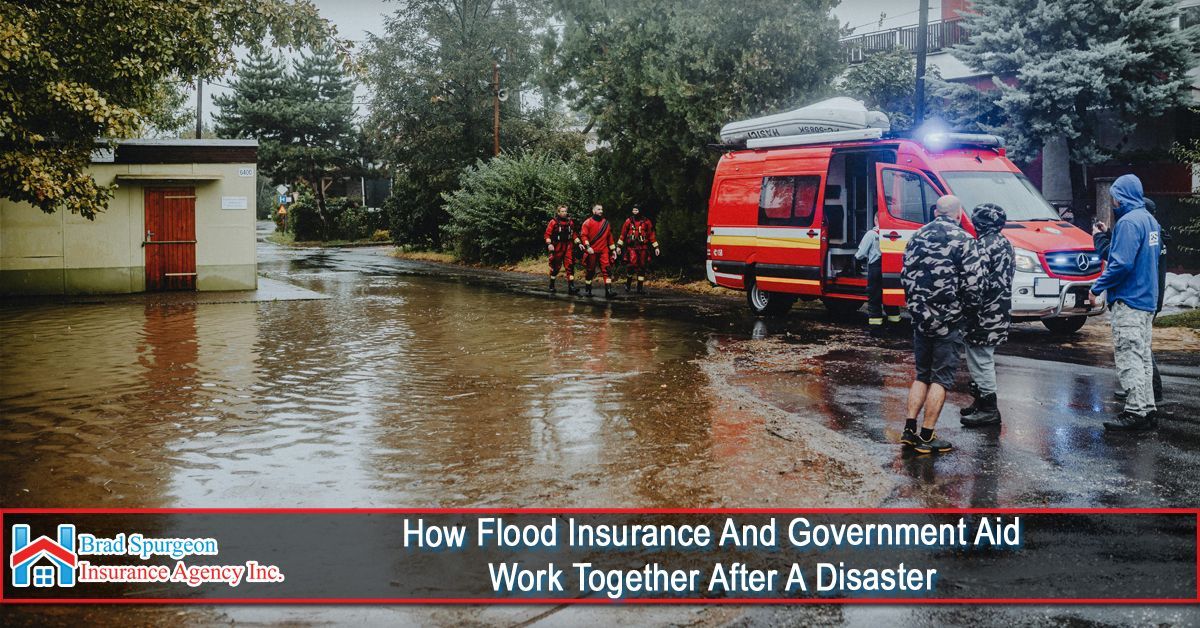
Emergency responders stand by a red rescue vehicle on a street flooded with brown water after a disaster.

Flooding can strike with little warning—and when it does, the aftermath can be devastating. Even a few inches of water can cause thousands of dollars in property damage, and homeowners are often left wondering how they’ll recover. Many assume that government disaster aid will cover the costs, but the truth is, flood insurance and federal assistance work very differently—and they often complement each other rather than overlap.


Understanding how these two forms of protection work together can help you make better financial and recovery decisions, especially if you live in a flood-prone coastal area like Texas City, Texas.


Understanding Flood Insurance

Flood insurance is a specialized policy that provides financial protection against damage caused by flooding—something standard homeowners or renters insurance doesn’t cover.


In most cases, flood insurance is purchased through the National Flood Insurance Program (NFIP), which is managed by FEMA. Some private insurers also offer flood policies, but the NFIP remains the most common source for homeowners in flood-risk zones.


What Flood Insurance Covers

A standard NFIP policy offers two primary types of coverage:


1. Building Property Coverage

Covers damage to the physical structure of your home, including:

  • Foundation, walls, and roof
  • Electrical and plumbing systems
  • Appliances like water heaters, furnaces, and built-in dishwashers
  • Permanently installed carpeting and cabinets


2. Personal Property (Contents) Coverage

Covers personal belongings such as:

  • Furniture, clothing, and electronics
  • Curtains, rugs, and smaller appliances
  • Portable air conditioners and microwaves


Note: Flood insurance usually does not cover temporary housing, vehicles, or items stored outside the home.


Why Flood Insurance Is So Important

Flooding is one of the most common natural disasters in the United States, yet many homeowners are unprepared. Just one inch of floodwater can cause more than $25,000 in damage.


If you live near coastal or low-lying areas—like Texas City, Texas—you’re especially vulnerable to hurricanes, tropical storms, and heavy rainfall events that can lead to severe flooding.


Flood insurance:

  • Provides guaranteed coverage regardless of federal disaster declarations
  • Pays claims faster than federal aid (usually within weeks, not months)
  • Offers peace of mind knowing you’re financially protected before disaster strikes


How Government Aid Works After a Flood

Government disaster aid, typically managed by the Federal Emergency Management Agency (FEMA), becomes available only after a Presidential Disaster Declaration.


While this assistance can be helpful, it’s important to understand its limitations:


Types of Government Aid

1.Grants:

  • Small amounts of money to cover temporary housing or emergency repairs.
  • Usually do not exceed a few thousand dollars per household.
  • Do not have to be repaid, but are not designed to restore your home completely.


2.Low-Interest Loans (through the SBA):

  • Offered by the U.S. Small Business Administration (SBA) to homeowners, renters, and businesses.
  • Must be repaid with interest, though rates are typically lower than private loans.
  • Can help cover rebuilding costs, replacing belongings, or repairing property damage.


3.Temporary Housing Assistance:

  • Covers rent or hotel costs if your home is uninhabitable after a disaster.
  • Short-term and limited in scope.


Flood Insurance vs. Federal Aid: Key Differences

Comparison table highlighting differences between flood insurance and government aid across five categories.

How They Work Together

Flood insurance and government aid aren’t competitors—they’re complementary safety nets. In fact, FEMA often encourages homeowners to carry flood insurance because it reduces reliance on federal aid.


Here’s how they can work hand in hand:

  1. Immediate Recovery: Your flood insurance can provide funds quickly to begin repairs.
  2. Supplemental Assistance: If losses exceed your coverage or certain costs aren’t covered (like temporary housing), FEMA or SBA programs can fill the gap.
  3. Future Protection: After a disaster, maintaining flood insurance may make you eligible for additional assistance or improved recovery options.


Example:

A homeowner in Texas City, Texas, files a flood claim for $75,000 in damage. Their NFIP policy pays for repairs, while FEMA provides a small grant for temporary housing during reconstruction.


Who Benefits Most from Flood Insurance

Flood insurance is beneficial for:

  • Homeowners in coastal or flood-prone areas (like along Galveston Bay or nearby Texas City)
  • Renters who want to protect their personal belongings
  • Businesses with valuable inventory or equipment in flood zones
  • Homeowners with federally backed mortgages in high-risk flood areas (where insurance is required by law)


Even if you’re outside a designated flood zone, you’re still at risk—nearly 25% of all flood claims come from moderate- to low-risk areas.


Tips for Coordinating Flood Insurance and Government Aid

  1. Purchase flood insurance early. There’s typically a 30-day waiting period before coverage takes effect.
  2. Document all damages. Take photos, keep receipts, and file claims promptly.
  3. Apply for FEMA aid if needed. Even if you have flood insurance, FEMA assistance can supplement uncovered costs.
  4. Stay informed about updates. Both the NFIP and FEMA periodically adjust coverage limits and assistance programs.
  5. Work with a local insurance agent. Agents familiar with Texas City, Texas, can help tailor coverage based on your property’s flood risk and local building requirements.


The Bottom Line

Flood insurance and government aid serve different—but equally important—purposes. While FEMA aid can provide short-term relief, flood insurance is your most reliable long-term protection against the financial impact of a flood.


For homeowners in Texas City, Texas, where severe weather and coastal flooding are real risks, having both resources available can make recovery faster, smoother, and more secure when disaster strikes.


At Brad Spurgeon Insurance Agency Inc., we aim to provide comprehensive insurance policies that make your life easier. We want to help you get insurance that fits your needs. You can get more information about our products and services by calling our agency at (409) 945-4746. Get your free quote today by
CLICKING HERE. 


Disclaimer: The information presented in this blog is intended for informational purposes only and should not be considered as professional advice. It is crucial to consult with a qualified insurance agent or professional for personalized advice tailored to your specific circumstances. They can provide expert guidance and help you make informed decisions regarding your insurance needs.

September 15, 2026
If you own a home in Texas City, you already know windstorm insurance isn't optional, and you've probably felt the sting of the premium on your renewal notice. Years of active hurricane seasons along the Gulf have pushed rates higher across the board, but that doesn't mean you're stuck accepting whatever number your ca
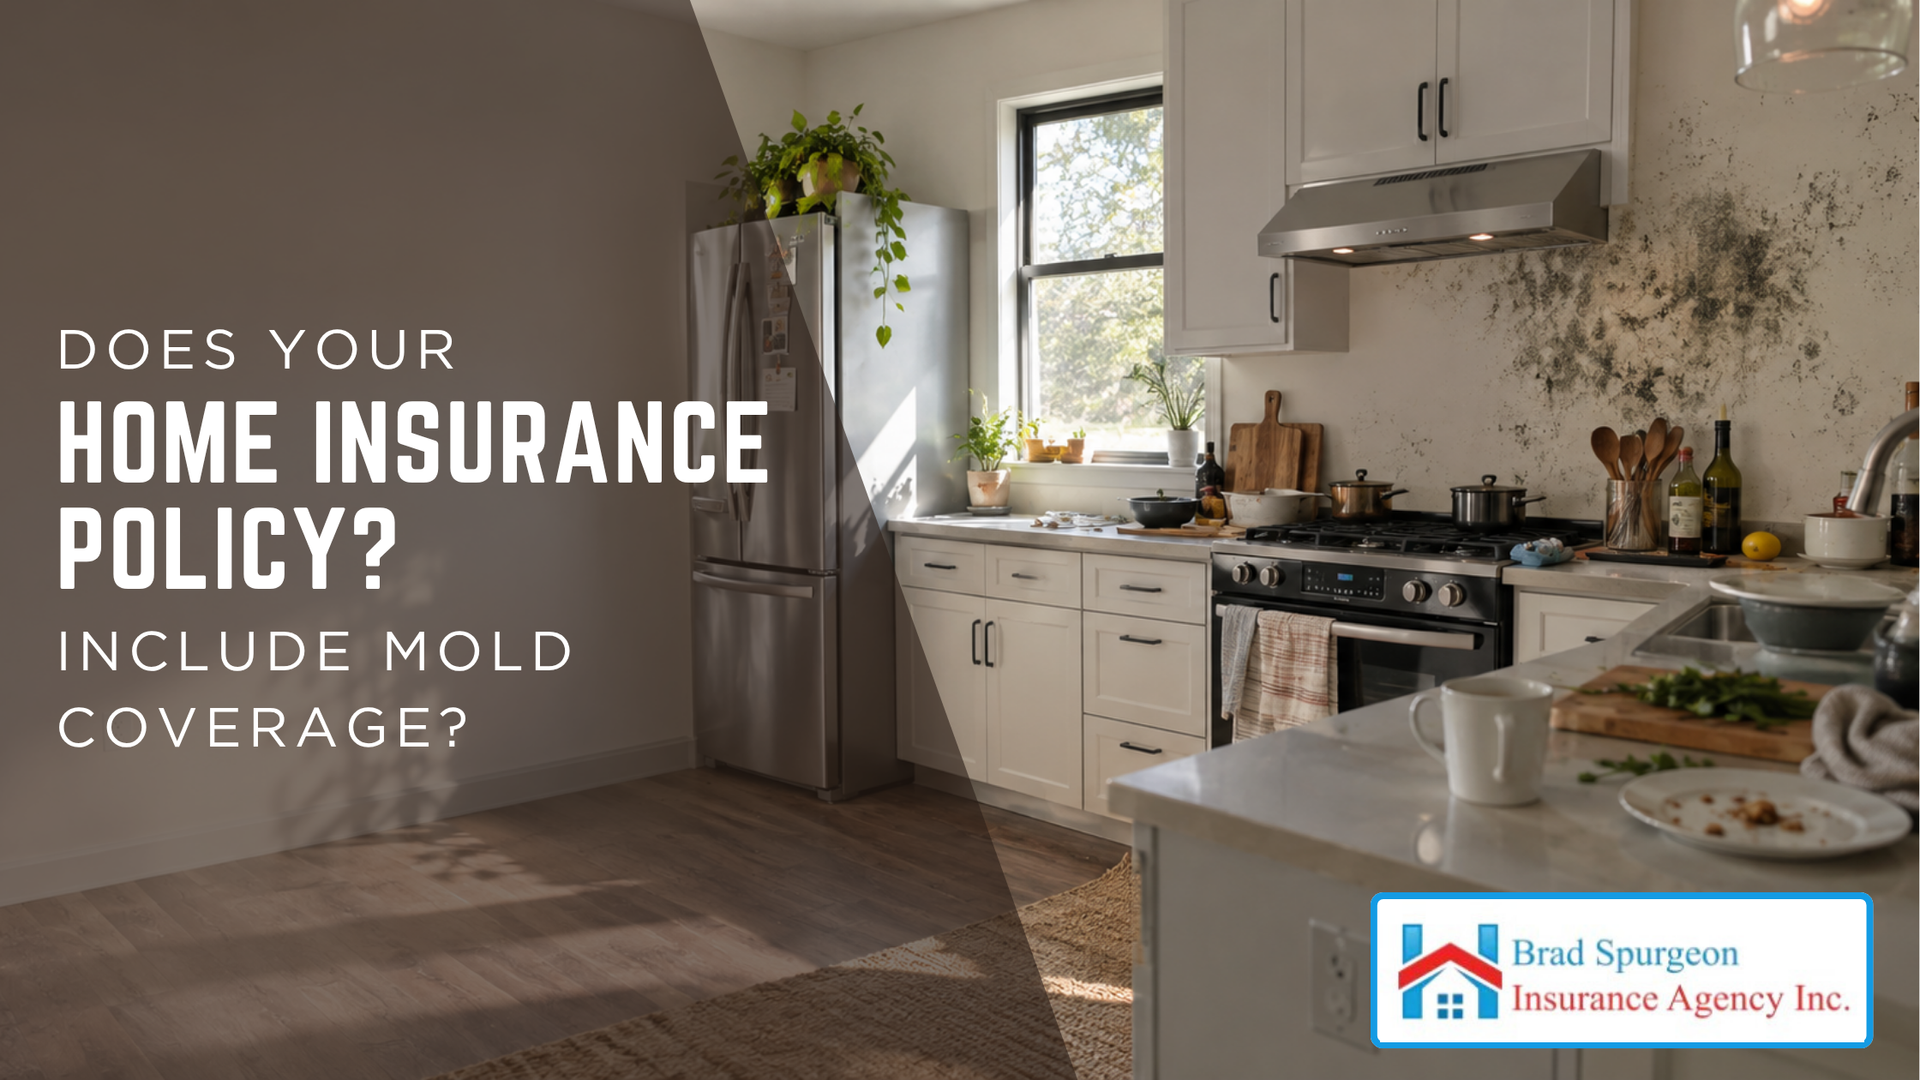
A damaged, peeling wall with dark mold growth
September 9, 2026
Mold has a way of showing up in Texas City homes when you least expect it, and Gulf Coast humidity doesn't make it any easier to avoid. Between hurricane-season moisture, everyday humidity, and the occasional leaky pipe or roof, it's one of the more common issues local homeowners run into, and also one of the more misu
September 9, 2026
Owning a home along the Texas Gulf Coast means living with a level of risk most inland homeowners never think twice about. Between hurricane season, hail storms rolling in off the Gulf, and the ever-present threat of flooding after a heavy rain, a homeowners policy here has to work harder than it does almost anywhere e
September 9, 2026
Most Texas City homeowners assume that if their house takes on water, their homeowners policy has them covered. It doesn't, and finding that out mid-claim is one of the most expensive surprises a Gulf Coast homeowner can face. Flood damage is excluded from every standard homeowners and commercial property policy in the
Home, homeowners, and flood policy comparison over a flooded house illustration
September 7, 2026
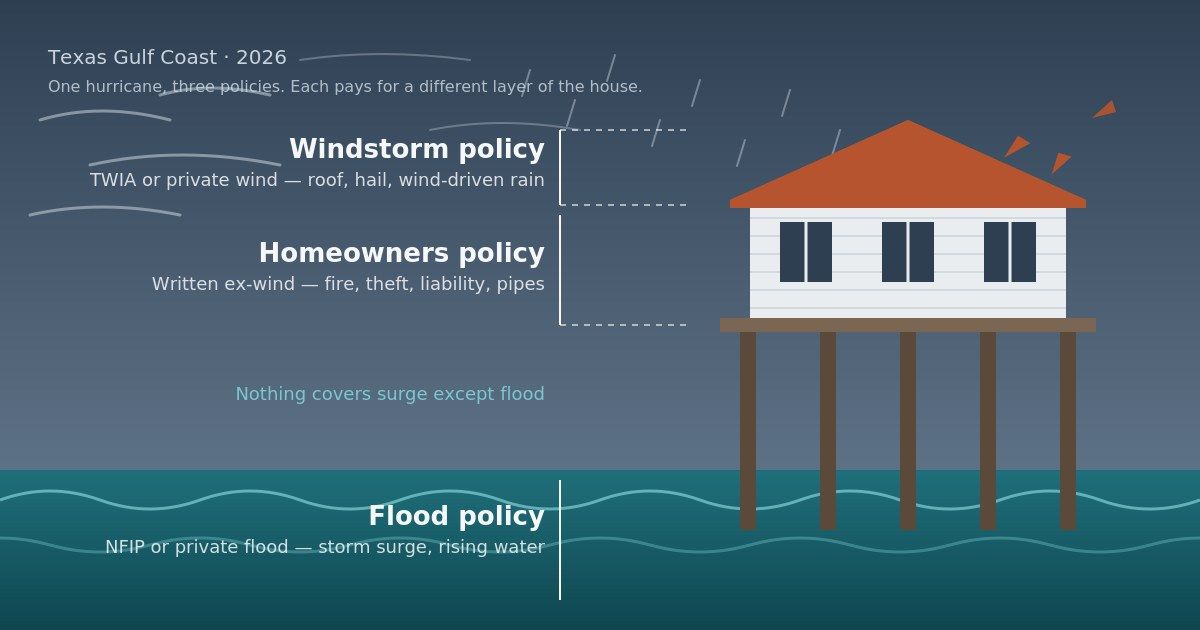
How Texas coastal homeowners actually get hurricane coverage: TWIA 2026 limits, the declination rule, WPI-8 certificates, named-storm deductibles, and the flood policy that pays for surge. Written by a Gulf Coast agent.
Flooded beach house on stilts with roof damage and insurance claim callouts about a Gulf Coast short-term rental
September 7, 2026
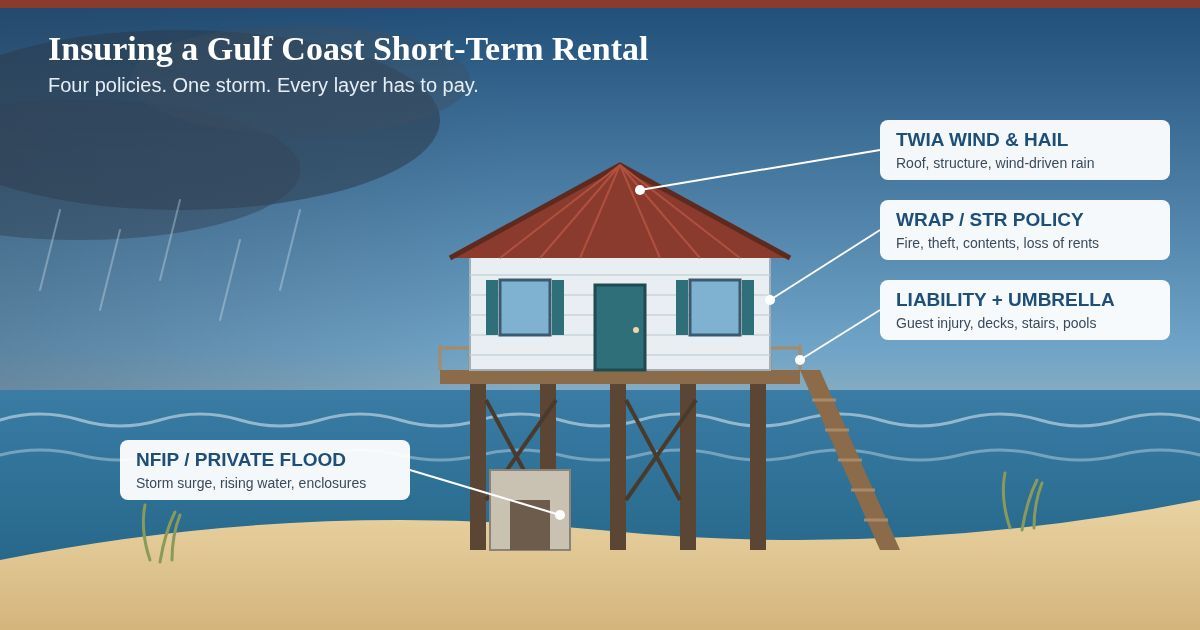
How to insure a Galveston, Crystal Beach, Surfside, or Port Aransas short-term rental: TWIA wind, NFIP flood, Fire & Liability policy, from an experienced local Gulf Coast Insurance agent.
August 25, 2026
Learn why TWIA requires WPI-8 certification, which Texas coastal homes need it, key exceptions, and what to do if your certificate is missing.
A smiling parent sits on a couch and lifts a happy young child
August 19, 2026
Kids explore everything, and that curiosity is part of what makes childhood fun — but it also means everyday spaces in your home can hide risks you might not think twice about as an adult. A few thoughtful changes around the house can prevent the kinds of accidents that send families to the emergency room every year.
A view of two suburban houses
August 17, 2026
It's a question we hear often in Texas City, especially once a tropical system starts showing up in the forecast: can I still get flood insurance now, or is it too late? The honest answer is that it depends on your policy type and timing, and understanding how flood insurance waiting periods work can save you from a co
An American Red Cross emergency kit with supplies like water, a flashlight, goggles, and a poncho for flood survival.
August 10, 2026
Living near the Texas Gulf Coast means flooding isn't a rare or distant threat — it's a real possibility every hurricane season, and sometimes even after a heavy afternoon thunderstorm. Whether you're right along the water or a few miles inland, knowing how to prepare, evacuate, and recover safely can make all the diff
Show More